Category: Retirement Planning

  • Planning Your Retirement Budget to Ensure Financial Peace of Mind

    Planning Your Retirement Budget to Ensure Financial Peace of Mind

    Retirement is a big milestone, and planning your budget carefully can make all the difference in enjoying a comfortable and stress-free future. With rising living costs and complex schemes, understanding how to create a solid retirement budget is essential. Luckily, Singapore offers support like the Merdeka Generation Package, which can help ease some financial burdens. Whether you’re nearing retirement or already planning, knowing how to manage your finances well ensures peace of mind and a more fulfilling retirement journey.

    Key Takeaway

    Creating a clear retirement budget involves understanding your income sources, estimating expenses, and taking advantage of government schemes like the Merdeka Generation Package. Planning ahead ensures you can enjoy your golden years without financial worries, supported by Singapore’s social safety nets and personal savings.

    Understanding the Importance of Retirement Budget Planning

    A well-thought-out retirement budget is the foundation of a stable and enjoyable retirement. It helps you identify how much money you’ll need to cover daily living, healthcare, leisure, and unexpected costs. Without a proper plan, there’s a risk of running out of funds or having to cut back on essential activities.

    Singaporeans approaching retirement often wonder if their savings will last or if they can tap into schemes like the Merdeka Generation Package. Knowing your income sources, such as CPF payouts, pensions, and any part-time work, alongside your expenses, allows you to set realistic targets. Proper planning also helps you avoid common pitfalls, like underestimating healthcare costs or overspending on non-essentials.

    Steps to Create Your Retirement Budget

    Developing a successful retirement budget involves a systematic approach. Here are three practical steps to get started:

    1. Assess your current financial situation
    2. List all income sources: CPF payouts, pension, rental income, part-time work.
    3. Review your savings, investments, and any government support like the Merdeka Generation Package.

    4. Estimate your retirement expenses

    5. Cover essentials: housing, utilities, groceries, transportation.
    6. Plan for healthcare costs: insurance premiums, Medisave, outpatient visits.
    7. Allocate for leisure, travel, hobbies, and emergencies.

    8. Adjust and optimise your budget

    9. Identify areas to cut back if needed.
    10. Maximise government subsidies and benefits.
    11. Consider strategies like downsizing or renting out property to supplement income.

    Practical tips for effective budget planning:

    • Use a simple spreadsheet to track income and expenses.
    • Regularly review and update your budget as circumstances change.
    • Seek advice from financial planners or community resources if unsure.

    Key Spending Areas in Retirement

    Understanding your spending list helps you allocate funds wisely. Here are common expense categories:

    • Housing and utilities
    • Food and groceries
    • Healthcare and Medisave contributions
    • Transportation, including public transport concessions
    • Leisure activities and hobbies
    • Travel and holidays
    • Emergency fund for unexpected costs

    Items to consider when estimating expenses:

    • Medical bills and insurance premiums
    • Dental and vision care
    • Home maintenance or rent
    • Personal care and grooming
    • Technology and communication tools

    Leveraging Singapore’s Support Schemes

    Singapore offers several schemes that can lighten your financial load. The Merdeka Generation Package is a key benefit, providing subsidies for healthcare, increased MediSave top-ups, and other financial support. To be eligible, you must have been born in 1950 to 1959 and meet certain criteria.

    Other schemes include the Community Health Assist Scheme (CHAS), which offers subsidies at participating clinics, and housing grants if you’re considering downsizing or moving.

    “Maximising your government benefits can significantly reduce your healthcare and living costs, freeing up more funds for your lifestyle and leisure activities.” — Financial Advisor

    Simplifying complex schemes:

    • Check your eligibility early and apply for schemes like the Merdeka Generation Package and CHAS.
    • Keep track of renewal dates and required documents.
    • Consult official resources or community centers for assistance.

    Practical Retirement Budget Tips

    • Start saving early and consistently. Use CPF and supplementary plans for long-term growth.
    • Keep a buffer for unexpected expenses, especially healthcare.
    • Consider part-time work or passive income sources to extend your funds.
    • Regularly review your expenses against your income sources.
    • Take advantage of discounts and subsidies available to seniors.
    Technique What it achieves Common mistake
    Budget tracking Keeps expenses in check Underestimating healthcare costs
    Prioritising essentials Ensures basic needs are met Overspending on leisure
    Using subsidies Reduces out-of-pocket expenses Missing application deadlines

    Navigating Healthcare Costs

    Healthcare can be a significant part of retirement expenses. Medisave, a compulsory savings scheme, helps you pay for hospitalisation and certain outpatient treatments. The Merdeka Generation Package enhances this by offering additional subsidies and Medisave top-ups.

    To make the most of healthcare support:
    – Regularly check your Medisave balance.
    – Use CHAS at approved clinics for subsidies.
    – Consider supplementary insurance if needed.
    – Plan for long-term care, including possible assisted living.

    Tips for managing healthcare costs:

    • Be proactive in health screenings.
    • Maintain a healthy lifestyle to reduce medical expenses.
    • Confirm if your specialist or treatment qualifies for subsidies.

    Planning for Leisure and Lifestyle

    Retirement isn’t just about finances; it’s about enjoying life. Budgeting for hobbies, social activities, and travel ensures a fulfilling retirement. Many community centres and schemes offer discounts or subsidies on activities that keep you active and engaged.

    Remember to balance your spending:
    – Allocate a portion of your budget for enjoyable activities.
    – Explore affordable options for travel and entertainment.
    – Use PAssion Card discounts and senior activity programmes.

    Final Thought: Making Your Retirement Money Work for You

    Effective retirement budget planning combines understanding your income, estimating expenses, and making the most of available support. It’s a continuous process that adapts as your needs change. Regularly reviewing your financial plan helps you stay on track and avoid surprises.

    By taking small, deliberate steps today, you can secure a retirement filled with comfort, health, and happiness. Use the available schemes and subsidies wisely, plan for the unexpected, and remember that good financial habits today pave the way for peace of mind tomorrow.

    Turning Your Retirement Budget into a Life of Fulfillment

    Retirement is a new chapter, and with a clear budget, it can be your most enjoyable one. Implementing these straightforward steps and making use of Singapore’s social schemes ensures you’re prepared for whatever lies ahead. Keep your goals in mind, stay flexible, and enjoy the journey towards a worry-free retirement.

  • Smart Strategies to Maximise Your Retirement Savings in Singapore

    Smart Strategies to Maximise Your Retirement Savings in Singapore

    Retirement planning can feel overwhelming, especially with a maze of schemes and options available. Yet, with a clear approach, you can significantly boost your savings and enjoy your golden years comfortably. Understanding the right strategies helps you make smarter financial decisions today, securing your future tomorrow. Whether you are just starting or refining your plan, knowing how to optimise your resources is key to achieving peace of mind and financial independence.

    Key Takeaway

    Maximising your retirement savings in Singapore involves understanding government schemes like CPF, planning early, diversifying investments, and regularly reviewing your finances. A strategic approach helps you build a reliable income stream and enjoy a comfortable retirement.

    Understanding the landscape of retirement savings in Singapore

    Singapore’s retirement system is built around the Central Provident Fund (CPF), which forms the backbone of most retirement plans. But it is just one component. To ensure a well-rounded strategy, you need to combine CPF maximisation with other savings and investment options. Recognising the various schemes, benefits, and potential pitfalls can help you develop a plan that works specifically for your needs.

    Key retirement savings strategies in Singapore

    1. Start early and contribute regularly

    The most effective way to grow your retirement funds is to begin saving as soon as possible. The power of compounding means that even small, consistent contributions can grow significantly over time. For instance, if you start contributing to your CPF at age 25, your savings will have more years to accumulate interest compared to starting at 45. Regular contributions also help you develop disciplined financial habits, ensuring you stay on track.

    1. Maximise your CPF contributions and benefits

    Your CPF account is a vital pillar of your retirement savings. To get the most out of it, consider these steps:

    • Contribute the maximum allowed, especially to your Ordinary and Special Accounts
    • Take advantage of schemes like the Retirement Sum Top-Up to boost your CPF
    • Explore the benefits of CPF Life, which provides lifelong payouts starting from age 65
    • Keep track of your contribution limits using the CPF mobile app or online dashboards

    • Diversify with additional investments

    While CPF is a solid foundation, diversifying your savings into other assets enhances growth and reduces risk. Options include:

    • Investing in the Supplementary Retirement Scheme (SRS), which offers tax benefits
    • Building a portfolio of stocks, bonds, or unit trusts suited to your risk appetite
    • Considering annuities or insurance products that provide guaranteed income streams
    • Regularly reviewing and rebalancing your investments to adapt to market changes

    Simplifying complex schemes and benefits

    Many in Singapore are unaware of the full potential of schemes like the Merdeka Generation Package or the Silver Support Scheme. These programs provide additional financial support that can supplement your retirement income.

    “Understanding and claiming your entitled benefits can make a significant difference in your retirement planning. Take the time to review eligibility criteria and application procedures to maximise these schemes.” — Financial expert

    For example, the Merdeka Generation Package offers healthcare subsidies and other benefits to seniors born before 1952. To ensure you’re getting the most out of these programs, regularly check your eligibility and update your details with relevant agencies. Learning how these benefits synergise with your savings plan helps you craft a resilient financial strategy.

    Practical steps to boost your retirement funds

    Here are three actionable processes to help you strengthen your retirement savings:

    1. Review your current finances and identify areas where you can increase savings or reduce expenses.
    2. Set specific savings goals based on your desired retirement lifestyle and estimate future expenses.
    3. Automate your contributions to CPF and investment accounts to ensure consistency.

    Additional tips include:

    • Use the CPF Retirement Calculator to project your payouts
    • Consider delaying the start of CPF Life payouts to increase monthly benefits
    • Invest in health insurance plans that complement your CPF Medisave and government subsidies
    • Maintain an emergency fund to prevent dipping into retirement savings during unforeseen events

    Common mistakes to avoid

    Techniques Mistakes to Avoid
    Over-relying on CPF Ignoring supplementary savings options
    Neglecting early contributions Starting retirement planning late
    Failing to diversify investments Putting all funds into high-risk assets
    Not reviewing plans regularly Forgetting to update beneficiary details

    Sticking to a disciplined, well-rounded approach prevents costly errors and ensures steady progress toward your retirement goals.

    Tips for making your savings work harder

    • Use dollar-cost averaging to reduce market timing risks
    • Take advantage of government schemes like the Silver Support Scheme if eligible
    • Consider property downsizing or rental to generate additional income
    • Leverage tax incentives such as the SRS to optimise your savings

    How to stay on track with your retirement plan

    Regularly reviewing your financial picture ensures your strategy stays relevant. Set annual reviews to:

    • Adjust contribution amounts based on income changes
    • Reassess investment allocations
    • Update your health and insurance coverage
    • Revisit your retirement lifestyle goals

    Engaging a financial advisor can also provide personalised insights. Remember, flexibility is key — your plan should evolve along with your circumstances.

    Building a retirement-ready mindset

    Retirement planning is as much about mindset as it is about numbers. Cultivating a habit of saving early and consistently builds a strong financial foundation. Stay informed about new schemes and benefits, and take proactive steps to claim what you are entitled to.

    “The most successful retirees are those who begin planning early, stay disciplined, and adapt their strategies over time. It’s never too late to start, but the earlier, the better.” — Retirement specialist

    Your next move towards a secure retirement

    Effective retirement savings strategies in Singapore combine disciplined contributions, smart investments, leveraging government benefits, and regular plan reviews. By understanding your options and avoiding common pitfalls, you can build a financial cushion that supports your desired lifestyle.

    Take the time now to evaluate your current savings and explore ways to optimise them. Small, consistent actions today will pave the way for a more comfortable and worry-free retirement.

    Planning today for a brighter tomorrow

    Retirement is a journey that requires thoughtful planning and ongoing adjustment. Whether you are just starting or refining your approach, taking strategic steps will help you reach your goals. Remember, your future self will thank you for the effort you put in today. Stay proactive, stay informed, and enjoy the peace of mind that comes with a well-prepared retirement plan.

  • Should You Downsize Your HDB Flat for Extra Retirement Cash?

    Should You Downsize Your HDB Flat for Extra Retirement Cash?

    Your four-room flat in Toa Payoh has served you well for 30 years. The kids have moved out. You’re staring at empty bedrooms and wondering if all that space could be turned into something more useful for retirement.

    You’re not alone in this thought.

    Key Takeaway

    Downgrading your HDB flat can free up retirement funds, but it’s not the only option. The Silver Housing Bonus and Lease Buyback Scheme offer alternatives. Your choice depends on your financial needs, lifestyle preferences, and whether you qualify for government incentives. Understanding each path helps you make a decision that supports your retirement goals without regret.

    Why homeowners consider downgrading their HDB flats

    The maths is simple on paper.

    You own a larger flat worth more money. You move to a smaller, cheaper one. The difference goes into your pocket.

    For many Singaporeans approaching retirement, this cash injection looks attractive. Medical bills don’t get cheaper. Daily expenses keep climbing. CPF payouts might not stretch as far as you’d hoped.

    But money isn’t the only reason people consider this move.

    Some find maintaining a large flat exhausting. Cleaning four rooms when you only use two feels like wasted effort. Others want to move closer to children or healthcare facilities.

    The emotional side matters too. That flat holds decades of memories. Letting go isn’t easy, even when the financial case makes sense.

    Understanding the Silver Housing Bonus

    The government offers a cash incentive called the Silver Housing Bonus when you downgrade HDB for retirement.

    Here’s how it works.

    If you’re 55 or older and you sell your current flat to buy a smaller one, you can receive up to $30,000. This bonus goes straight into your CPF Retirement Account.

    The amount depends on the type of flat you’re moving to:

    • 3-room or smaller flat: $30,000
    • 4-room flat: $20,000
    • 5-room flat: $15,000

    You must meet several conditions. Both you and your spouse (if married) must be at least 55 years old. You’re moving from a larger flat type to a smaller or equal one. The remaining lease on your new flat must cover you until at least age 95.

    One important detail: you can only claim this bonus once in your lifetime.

    The bonus gets credited to your CPF Retirement Account, not your bank account. This means it boosts your monthly CPF LIFE payouts later, giving you a steady income stream rather than a lump sum to spend.

    For many seniors, this structure provides discipline. The money can’t be spent impulsively. It builds your retirement safety net month by month.

    The Lease Buyback Scheme as an alternative

    Not everyone wants to move house.

    The Lease Buyback Scheme lets you stay in your current flat while still accessing some of its value.

    Here’s the basic idea: you sell part of your flat’s remaining lease back to HDB. In return, you receive cash and continue living in the same home for the rest of your life.

    The scheme works for 3-room or smaller flats, or 4-room flats in non-mature estates.

    After selling the tail end of your lease, HDB retains a lease that covers you and your spouse until at least age 95. You get to keep living there. No packing. No goodbyes to neighbours. No adjustment to a new neighbourhood.

    The proceeds from the lease sale go into your CPF Retirement Account. Like the Silver Housing Bonus, this boosts your CPF LIFE payouts.

    One major advantage: you avoid the stress and cost of moving. No renovation. No agent fees. No months of house hunting.

    But there’s a trade-off. You receive less cash compared to selling your flat outright and buying a cheaper one. The amount depends on your flat’s value and the length of lease you’re selling back.

    The Lease Buyback Scheme suits people who value stability and emotional attachment to their home over maximising cash.

    Steps to downgrade your HDB flat properly

    If you decide moving to a smaller flat makes sense, here’s how to do it without costly mistakes.

    1. Check your eligibility for the Silver Housing Bonus. Confirm both you and your spouse meet the age requirement. Make sure the flat you’re eyeing has enough remaining lease to cover you until 95.

    2. Calculate your potential cash proceeds. Estimate your current flat’s selling price. Subtract the cost of the new flat, agent fees, renovation, and moving expenses. What’s left is your actual gain.

    3. Apply for the Silver Housing Bonus when you complete the purchase. HDB will credit the bonus to your CPF Retirement Account. You don’t need to apply separately beforehand.

    4. Plan your CPF Retirement Account top-up strategy. The proceeds from your sale, combined with the bonus, can significantly increase your monthly payouts. Understanding how much money you really need for retirement helps you decide how much to set aside.

    5. Time your move carefully. Selling and buying simultaneously can be tricky. Some people rent temporarily to avoid rushing into a bad purchase. Others use the Sale of Balance Flat scheme to secure their next home before selling.

    6. Consider healthcare access in your new location. Moving further from polyclinics or hospitals might save money but cost you convenience. If you’re part of the Merdeka Generation, your CHAS card benefits work island-wide, but proximity still matters for emergencies.

    Common mistakes that cost retirees money

    Many people rush into downsizing without thinking through the details. Here are the traps to avoid.

    Mistake Why It Hurts How to Avoid It
    Underestimating moving costs Renovation, movers, and agent fees can eat 10% of your proceeds Get written quotes before committing to the move
    Buying a flat that’s too small Cramped living makes you miserable, and you can’t claim the bonus again Visit several units and imagine daily life there
    Ignoring remaining lease length A flat with 60 years left might not meet CPF withdrawal rules Check HDB’s lease requirements for your age group
    Forgetting about Medisave needs You still need enough in Medisave for healthcare Keep sufficient funds aside; learn how much you need in Medisave
    Not comparing Lease Buyback You might get similar benefits without moving Run the numbers for both options before deciding

    One couple I know sold their Ang Mo Kio flat and bought a smaller one in Yishun. They pocketed $150,000 after all expenses. Sounds great, right?

    But they didn’t factor in the cost of new furniture. Their old sofa didn’t fit. The kitchen layout was different, so they needed new cabinets. By the time they settled in, they’d spent an extra $20,000 they hadn’t budgeted for.

    Another common mistake: assuming the cash windfall will last forever. $100,000 sounds like a lot, but if you’re 60 and live to 90, that’s only $3,300 a year. Not exactly a fortune.

    “The biggest regret I see is people who downsize too aggressively. They move from a 4-room to a 2-room flat, thinking they’ll save more. Then they realise they have no space for grandchildren to visit. The money isn’t worth the loneliness.” — Housing counsellor at a community centre

    When downsizing doesn’t make sense

    Not everyone should downgrade their HDB flat for retirement.

    If your CPF LIFE payouts already cover your expenses comfortably, you might not need the extra cash. Staying put avoids disruption and keeps you in a familiar environment.

    Some flats have poor resale value. If you own an older flat in a less desirable location, the sale price might barely cover the cost of a smaller replacement. You go through all the hassle for minimal gain.

    Location matters more as you age. If your current flat is near children, medical facilities, or a strong support network, moving could isolate you. No amount of money compensates for losing daily help or companionship.

    Health is another factor. If mobility is already an issue, the stress of moving and adjusting to a new layout might outweigh financial benefits.

    And if you’re emotionally attached to your home, forcing yourself to leave can lead to depression. Mental health affects physical health. A miserable retirement isn’t worth an extra $50,000.

    How the Lease Buyback Scheme compares

    Let’s put numbers to the two main options.

    Say you own a 4-room flat in Bedok worth $450,000. You’re 65 and considering your options.

    Option 1: Downgrade to a 3-room flat

    • Sell your 4-room flat: $450,000
    • Buy a 3-room flat: $300,000
    • Agent fees and costs: $15,000
    • Silver Housing Bonus: $30,000
    • Net cash to CPF Retirement Account: $165,000

    Option 2: Lease Buyback Scheme

    • Sell tail end of lease: $120,000 (estimate)
    • Stay in your current flat
    • No moving costs
    • Net cash to CPF Retirement Account: $120,000

    Option 1 gives you $45,000 more, but you have to move. Option 2 lets you stay put with less cash.

    Which is better?

    That depends on whether you value the extra money or the stability of staying in your home.

    For some, the $45,000 difference is significant. It could mean better healthcare, more help with daily tasks, or financial support for grandchildren.

    For others, the emotional and practical cost of moving outweighs the financial gain. They’d rather have $120,000 and stay in a familiar place than $165,000 in a new neighbourhood.

    There’s no universal right answer. Your health, family situation, and financial needs determine which path suits you.

    Practical tips to maximise your retirement funds

    Whether you choose to downgrade or use the Lease Buyback Scheme, you can stretch your money further with smart planning.

    • Top up your CPF Retirement Account beyond the bonus. If you have spare cash after the move, consider voluntary contributions. This increases your monthly payouts for life. Some people find topping up CPF after 65 helps them sleep better at night.

    • Delay withdrawing CPF if you don’t need it immediately. The longer you wait, the higher your monthly payouts become. If you’re still working part-time or have other income, letting your CPF grow pays off.

    • Coordinate with your spouse. If only one of you qualifies for Merdeka Generation benefits, plan together to maximise those subsidies. Healthcare costs can be managed better as a team.

    • Budget for one-time expenses. Moving, even to a smaller flat, comes with hidden costs. Curtains, minor repairs, and small furniture add up. Set aside 10% of your proceeds for these surprises.

    • Review your MediShield Life coverage. As you age, medical needs increase. Make sure you understand how to maximise your coverage so unexpected bills don’t drain your retirement funds.

    What about your children’s opinions?

    Your children might have strong views on whether you should downgrade.

    Some worry about you moving to a less convenient location. Others see the financial sense and encourage it. A few might even hope to inherit the flat someday.

    Here’s the thing: it’s your home and your retirement. Listen to their input, but make the decision based on your needs, not theirs.

    One common scenario: adult children offer to help financially so you don’t have to move. That’s generous, but think carefully. Do you want to depend on them? What if their circumstances change?

    Another scenario: children discourage downsizing because they use your spare room for storage or occasional stays. That’s not a good enough reason to stay in a flat that no longer serves you.

    Have honest conversations. Explain your reasoning. But don’t let guilt or family pressure override what’s best for your retirement security and happiness.

    Making your decision with confidence

    Choosing whether to downgrade your HDB flat for retirement is personal.

    Start by listing what matters most to you. Is it maximising cash? Staying in your neighbourhood? Avoiding the hassle of moving?

    Run the numbers for both downsizing and the Lease Buyback Scheme. Include all costs, not just the headline figures.

    Visit potential new flats if you’re considering a move. Spend time in the neighbourhood. Imagine your daily routine there.

    Talk to friends who’ve made similar decisions. What do they wish they’d known beforehand?

    Give yourself time. This isn’t a decision to rush. The property market will still be there in six months.

    If you’re eligible for Merdeka Generation benefits, factor those into your planning. The annual top-ups and healthcare subsidies add real value over time. Avoiding common mistakes when claiming benefits keeps more money in your pocket.

    And remember: there’s no perfect choice. Every option has trade-offs. The goal is to pick the one that aligns best with your priorities and gives you peace of mind.

    Your home, your retirement, your call

    Downgrading your HDB flat can be a smart financial move, but only if it fits your overall retirement picture. The cash boost helps, but not at the cost of your happiness or well-being.

    Some people thrive in a smaller, more manageable space. Others regret leaving a home filled with memories. You know yourself best.

    Take the time to understand your options. Crunch the numbers honestly. Consider how you want to spend your retirement years.

    Whether you move to a cosy 3-room flat or stay put with the Lease Buyback Scheme, the right choice is the one that lets you retire comfortably, confidently, and on your own terms.

  • 7 Ways to Stretch Your CPF LIFE Payouts Further After Age 65

    7 Ways to Stretch Your CPF LIFE Payouts Further After Age 65

    Your CPF LIFE payouts don’t have to stay fixed at the default amount. Many Singaporeans accept whatever monthly sum appears in their statement without realizing they have options to boost it. The truth is, a few strategic moves before and after turning 65 can add hundreds of dollars to your monthly income for life.

    Key Takeaway

    You can maximize CPF LIFE payouts through voluntary contributions, choosing the right payout plan, delaying withdrawals, and making smart top-up decisions. Even small adjustments before age 65 can significantly increase your monthly retirement income. Understanding your options and acting early gives you the best results for lifelong financial security.

    Understanding how CPF LIFE payouts actually work

    CPF LIFE payouts depend on three main factors: how much you have in your Retirement Account, which plan you choose, and when you start receiving payments.

    Your Retirement Account gets created automatically when you turn 55. Money from your Special Account and Ordinary Account transfers over to meet your Basic Retirement Sum. The more you have in this account, the higher your monthly payouts.

    Most people don’t realize the payout amount isn’t carved in stone. You have control over several levers that directly affect your monthly income.

    The system calculates your payouts based on actuarial tables, interest rates, and your chosen plan. But here’s what matters: every extra dollar you add before payouts start translates to more money every single month for the rest of your life.

    Choose the right CPF LIFE plan for your situation

    CPF offers three main plans: Standard, Basic, and Escalating. Each serves different needs.

    The Standard Plan gives you moderate monthly payouts with a decent bequest amount if you pass away early. Most Singaporeans default to this option.

    The Basic Plan provides lower monthly payouts but leaves more money for your beneficiaries. This works if you have other income sources and want to leave an inheritance.

    The Escalating Plan starts with lower payouts that increase by 2% yearly. This protects against inflation but means less money in your early retirement years.

    Here’s the practical comparison:

    Plan Initial Payout Bequest Best For
    Standard Moderate Moderate Most retirees
    Basic Lower Higher Those with other income
    Escalating Lowest initially Lower Long-term inflation protection

    You can switch plans before your payouts start. After that, you’re locked in.

    Many Merdeka Generation seniors benefit from the Standard Plan because it balances immediate income needs with legacy planning. If you’re eligible for the package, understanding your benefits can help inform your decision.

    Make voluntary contributions before turning 65

    This strategy has the biggest impact on your monthly payouts.

    You can top up your Retirement Account any time before age 65. These contributions earn guaranteed interest and directly increase your payout amount.

    Here’s how to do it:

    1. Check your current Retirement Account balance through the CPF website or app
    2. Calculate how much more you want to add (up to the Enhanced Retirement Sum)
    3. Make a cash top-up online, at a CPF Service Centre, or through GIRO
    4. Claim tax relief on the amount you contributed (up to $8,000 per year)

    The tax relief alone makes this worthwhile. If you’re in the 11.5% tax bracket, a $7,000 top-up saves you $805 in taxes while boosting your monthly income permanently.

    Your children can also top up your account and claim tax relief. Adult children helping parents maximize benefits often use this method to support retirement planning.

    The deadline matters. Contributions must reach CPF by December 31st of the year you want to claim relief for. Don’t wait until the last week as processing takes time.

    Delay your payout start date strategically

    You don’t have to start CPF LIFE payouts at 65. You can defer them up to age 70.

    Every year you wait increases your monthly payout by about 6% to 7%. That compounds significantly.

    Starting at 66 instead of 65 might give you an extra $60 to $80 monthly. Wait until 70, and you could see 30% to 35% higher payouts compared to starting at 65.

    This only works if you have other income sources to cover living expenses during the delay period. Part-time work, rental income, or savings from other accounts can bridge the gap.

    The calculation is personal. If you need the money now, start at 65. If you can afford to wait and want maximum monthly income later, deferring makes sense.

    “Delaying CPF LIFE payouts is one of the most underused strategies among retirees. The guaranteed increase beats most investment returns without any risk.” – Financial planning expert

    Manage your withdrawal decisions carefully

    At 65, you can withdraw money above your Basic Retirement Sum. This reduces your monthly payouts.

    Many people take out a lump sum for immediate expenses or peace of mind. That’s fine if you need it. But understand the trade-off.

    Every $10,000 you withdraw reduces your monthly payout by roughly $60 to $70 for life. Over 20 years, that’s $14,400 to $16,800 lost.

    Run the numbers before withdrawing. Ask yourself: do I need this money now, or would I benefit more from higher monthly income?

    Some Merdeka Generation members withdraw funds to pay off medical bills or help children with housing. Those are valid reasons. Just make the choice consciously, not automatically.

    Knowing what you can withdraw at 65 helps you plan better and avoid costly mistakes.

    Keep working and earning CPF contributions

    If you continue working past 65, your employer still contributes to your CPF. These contributions go to your Retirement Account and increase your payouts.

    Even part-time work helps. A $1,500 monthly salary generates about $255 in total CPF contributions. Over one year, that’s $3,060 added to your retirement savings.

    The contribution rates change after 55, but every bit counts. Plus, working keeps you active and socially connected.

    Many seniors take on flexible roles: tutoring, consulting, retail, or administrative work. The extra income plus CPF growth creates a double benefit.

    Your monthly payouts get recalculated annually if you continue receiving CPF contributions after payouts start. The adjustments appear automatically in your account.

    Top up after 65 if circumstances change

    Most people don’t know you can still make voluntary contributions after turning 65, even after payouts begin.

    These top-ups won’t increase your current monthly payout amount. Instead, CPF treats them as a separate pot that generates additional monthly income starting the following year.

    This works well if you receive an inheritance, sell property, or come into unexpected money. Rather than letting it sit in a low-interest savings account, you can convert it to guaranteed lifelong income.

    The process is simple:

    1. Log into your CPF account
    2. Select the voluntary contribution option
    3. Transfer the amount you want to top up
    4. CPF calculates the additional monthly payout and adds it from the next adjustment

    You still get tax relief on these contributions, subject to the annual cap.

    Deciding whether to top up after 65 requires weighing your current financial needs against long-term security.

    Coordinate with MediSave to protect your payouts

    Your CPF MediSave account works alongside your retirement planning. Keeping enough in MediSave means you won’t need to dip into CPF LIFE payouts for medical expenses.

    At 65, you need to maintain the Basic Healthcare Sum in your MediSave. This amount (currently around $68,500) covers most healthcare needs through MediShield Life and approved medical treatments.

    If your MediSave falls short, money from your Retirement Account gets transferred over. That reduces your CPF LIFE payouts.

    Avoid this by:

    • Monitoring your MediSave balance regularly
    • Using government subsidies and schemes wisely
    • Topping up MediSave if needed before it affects your Retirement Account

    Merdeka Generation members get extra healthcare subsidies that help preserve MediSave balances. Maximizing your MediShield Life coverage and understanding CHAS card benefits can significantly reduce out-of-pocket medical costs.

    Knowing how much MediSave you need prevents surprises that could drain your retirement savings.

    Common mistakes that reduce your payouts

    Understanding what not to do is just as important as knowing the right strategies.

    Mistake 1: Withdrawing everything possible at 65

    Taking the maximum lump sum feels good temporarily but permanently cuts your monthly income. Only withdraw what you genuinely need.

    Mistake 2: Not reviewing your CPF LIFE plan choice

    The default Standard Plan works for most people, but not everyone. Review your options before the deadline passes.

    Mistake 3: Forgetting about spousal planning

    If your spouse has lower CPF savings, consider topping up their account instead of yours. This balances household retirement income and maximizes tax relief.

    Mistake 4: Missing contribution deadlines

    December 31st is the hard deadline for tax relief claims. Late contributions don’t qualify for that year’s relief.

    Mistake 5: Ignoring annual statements

    CPF sends updates showing your projected payouts. Read them. They help you adjust your strategy while you still can.

    Avoiding common claiming mistakes applies to both CPF LIFE and Merdeka Generation benefits.

    Planning for different retirement timelines

    Not everyone retires at 65. Your CPF LIFE strategy should match your actual retirement age.

    Retiring before 65:

    You’ll need other savings to bridge the gap until CPF LIFE payouts start. Build up cash reserves, investments, or passive income streams.

    Consider part-time work that still allows CPF contributions. This keeps your Retirement Account growing even as you slow down.

    Retiring at 65:

    This is the standard scenario. Start your payouts on time and use the strategies above to maximize the monthly amount.

    Retiring after 65:

    Defer your payouts and keep contributing through work. This combination creates the highest possible monthly income when you finally stop working.

    The right approach depends on your health, financial needs, and personal goals. Understanding how much Merdeka Generation seniors really need provides context for your planning.

    Practical steps to take this month

    Stop thinking about maximizing CPF LIFE payouts as something you’ll handle “someday.” Take action now.

    If you’re under 55, focus on growing your Special Account and Ordinary Account balances. These feed into your Retirement Account later.

    If you’re between 55 and 64, this is your prime window. Make voluntary contributions, choose your CPF LIFE plan carefully, and decide on your payout start date.

    If you’re 65 or older, you can still make improvements. Review your withdrawal decisions, consider additional top-ups if you have spare cash, and ensure your MediSave stays healthy.

    Check your CPF statements every quarter. Log into your account and review the projected payout amounts. Small changes now create lasting differences.

    Talk to family members about coordinating strategies. If your children want to support your retirement, voluntary contributions to your CPF offer better long-term value than cash gifts.

    Making your retirement income work for you

    Your CPF LIFE payouts represent guaranteed income for life. That’s rare and valuable in retirement planning.

    By understanding how the system works and taking deliberate action, you control how much you receive each month. The difference between a passive approach and an active strategy can mean hundreds of extra dollars monthly.

    Those hundreds add up to thousands annually and tens of thousands over your retirement years. Money that covers better healthcare, helps grandchildren, funds hobbies, or simply provides peace of mind.

    The strategies here aren’t complicated. They just require attention and timely action. Review your situation, identify which approaches fit your circumstances, and implement them before the deadlines pass.

    Your future self will thank you for the extra income every single month.

  • What Happens to Your CPF Savings When You Pass Away? Estate Planning Essentials

    What Happens to Your CPF Savings When You Pass Away? Estate Planning Essentials

    Your CPF account holds decades of savings. But have you thought about where all that money goes when you’re no longer around?

    Most Singaporeans assume their CPF will automatically go to their spouse or children. The reality is more complicated. Without proper planning, your loved ones could face delays, legal complications, and unexpected tax implications. Understanding how CPF distribution works after death isn’t just about ticking boxes. It’s about protecting the people who matter most.

    Key Takeaway

    When you pass away, your CPF savings are distributed either through a CPF nomination or according to intestacy laws. Making a nomination ensures your money reaches your chosen beneficiaries faster and according to your wishes. Without one, the Public Trustee handles distribution, which can take months or years and may not align with what you intended for your family.

    Two Paths for Your CPF After Death

    Your CPF savings follow one of two routes when you die.

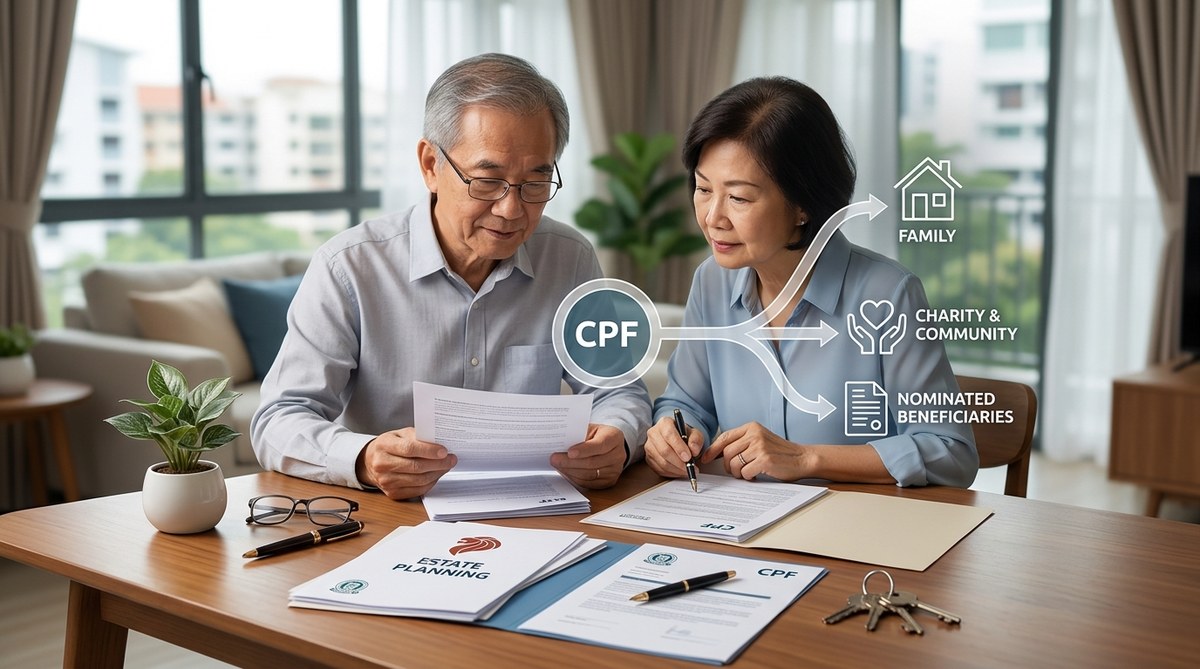
    The first path is through a CPF nomination. This is a legal document where you specify exactly who gets your CPF money and how much each person receives. You create this nomination while you’re alive, and it overrides other claims to your CPF.

    The second path applies when you haven’t made a nomination. Your CPF becomes part of your estate and gets distributed according to the Intestate Succession Act or Muslim inheritance law, depending on your religion. The Public Trustee’s Office steps in to manage the distribution.

    The difference between these two paths is significant. One gives you control. The other leaves it to legislation that might not match your wishes.

    Understanding CPF Nominations

    A CPF nomination is your direct instruction to the CPF Board about who should receive your savings.

    You can nominate anyone. Your spouse, children, parents, siblings, friends, or even charitable organisations. There’s no restriction on who qualifies as a nominee. You decide the proportion each person receives, whether that’s equal shares or different amounts.

    The nomination covers all your CPF accounts. This includes your Ordinary Account, Special Account, MediSave Account, and Retirement Account. It also covers any CPF investments you hold and any remaining funds in your CPF LIFE plan.

    Here’s what makes nominations powerful. The money goes directly to your nominees without passing through your estate. This means faster distribution, no probate delays, and no estate duty considerations for CPF savings.

    You can make two types of nominations. A general nomination splits your CPF among your chosen beneficiaries. A revocable nomination allows you to change or cancel it anytime. Once you make a nomination, it stays valid until you revoke it or circumstances change, like getting married or divorced.

    What Happens Without a Nomination

    When you die without a CPF nomination, your savings don’t vanish. But getting them becomes more complicated for your family.

    The CPF Board transfers your savings to the Public Trustee’s Office. From there, distribution follows strict legal rules. For non-Muslims, the Intestate Succession Act determines who gets what. For Muslims, the Syariah Court applies Islamic inheritance law.

    Under intestacy rules, your spouse and children typically receive priority. But the exact split depends on your family structure. If you’re survived by a spouse and children, they share the estate. If you have no spouse but have children, they split everything equally. If you have no children, your parents may receive a share.

    This process takes time. Months, sometimes years. Your family needs to apply to the Public Trustee, provide documentation, and wait for processing. During this period, they cannot access your CPF savings, even if they desperately need the funds for immediate expenses.

    The distribution might not match what you would have wanted. Perhaps you wanted to give more to a child with special needs, or less to someone who’s financially secure. Intestacy laws don’t consider these personal circumstances. They follow fixed formulas.

    How to Make a CPF Nomination

    Creating a CPF nomination is straightforward. You have three options.

    Online through CPF website

    1. Log in to your CPF account using Singpass
    2. Navigate to the “My Requests” section
    3. Select “Nominations”
    4. Fill in your nominees’ details and proportions
    5. Review and submit

    The online method is free and takes about 15 minutes. You need your nominees’ full names, NRIC or passport numbers, and relationship to you.

    At a CPF Service Centre

    Visit any CPF Service Centre with your NRIC. A staff member will help you complete the nomination form. This option works well if you prefer face-to-face guidance or have complex family situations.

    Through a lawyer

    For more complicated estates or if you want legal advice, a lawyer can help draft your nomination. This costs more but ensures everything is properly documented.

    After submission, CPF sends a confirmation letter to your registered address. Keep this document safe. Your nominees don’t receive copies, but you should inform them about the nomination so they know to claim it when the time comes.

    Who Should You Nominate

    Choosing nominees requires careful thought.

    Start with your immediate dependents. Who relies on you financially? Your spouse might need funds to maintain the household. Children pursuing education need support. Elderly parents might depend on your assistance.

    Consider each person’s financial situation. Someone with stable income and substantial savings might need less than a family member facing financial challenges. You can allocate different percentages to reflect these needs.

    Think about special circumstances. A child with disabilities might need more to cover long-term care. A spouse without CPF savings of their own might need a larger share. These personal factors matter more than equal distribution.

    You can nominate minors. If a nominee is under 18 when you die, the Public Trustee holds their share until they reach adulthood. You can also appoint a trustee to manage the funds for young children.

    Don’t forget about updating your nomination. Life changes. Marriages, divorces, births, and deaths all affect who should receive your CPF. Review your nomination every few years or after major life events.

    Common Mistakes to Avoid

    Many people make preventable errors with CPF nominations. Here’s what to watch out for.

    Mistake Why It’s a Problem How to Fix It
    Not making a nomination at all Delays distribution and removes your control Create one today, even a simple version
    Forgetting to update after divorce Your ex-spouse might still receive funds Revoke and create a new nomination immediately
    Using unclear percentages Creates confusion and potential disputes Ensure proportions add up to exactly 100%
    Not informing nominees They might not know to claim the money Tell them about the nomination and where to find documents
    Assuming your will covers CPF CPF nominations override wills Make a separate CPF nomination

    The biggest mistake is procrastination. Many people think they’ll do it later when they’re older. But accidents and illnesses don’t wait for convenient timing. Making a nomination in your 30s or 40s is just as important as doing it at 60.

    The Claiming Process for Beneficiaries

    When you pass away, your nominees need to claim the CPF savings. Here’s how the process works.

    Your family should notify CPF Board of your death. They can do this by submitting a death certificate to any CPF Service Centre or through the CPF website. The board then contacts all nominees listed in your nomination.

    Each nominee receives a notification letter. This letter explains their entitlement and provides claim forms. They need to complete these forms and submit them with supporting documents like their NRIC and proof of relationship.

    If you made a nomination, the process is relatively fast. CPF typically disburses the money within a few weeks after receiving all required documents. The funds go directly to each nominee’s bank account.

    Without a nomination, nominees must wait for the Public Trustee to complete the estate distribution. This can take six months to several years, depending on the estate’s complexity.

    For CPF LIFE members, any remaining balance gets distributed. If you were receiving monthly payouts, these stop upon death. Any funds left in your retirement account after accounting for insurance coverage go to your nominees or estate.

    CPF and Your Overall Estate Plan

    Your CPF nomination works alongside other estate planning tools, not in isolation.

    A will handles your other assets. Your property, bank accounts, investments, and personal belongings all fall under your will’s instructions. But your will cannot override a CPF nomination. These are separate legal instruments.

    Some people use a Lasting Power of Attorney (LPA) for healthcare and financial decisions while they’re alive but incapacitated. An LPA doesn’t affect what happens to your CPF after death. That’s still controlled by your nomination or intestacy laws.

    If you’re planning your retirement finances carefully, consider how your CPF fits into your overall legacy. Perhaps you want to use CPF funds for immediate family needs while leaving other assets for extended family or charity.

    Think about tax implications too. While CPF savings themselves aren’t subject to estate duty in Singapore, they form part of your overall financial picture. Proper planning ensures your beneficiaries receive maximum benefit with minimum complications.

    Special Considerations for Different Life Stages

    Your CPF nomination needs change as you move through life.

    In your 30s and 40s

    You might have young children and a mortgage. Consider nominating your spouse as the primary beneficiary to help maintain the household. Allocate portions to children with trustees managing their shares until adulthood.

    In your 50s and 60s

    Children might be financially independent now. You could adjust proportions to support elderly parents or increase your spouse’s share. This is also when many people review their CPF withdrawal options and need to align nominations with retirement plans.

    After 65

    Your CPF might be in CPF LIFE, providing monthly income. Review your nomination to ensure remaining balances go where you want. Consider how your MediSave needs might affect the amount available for distribution.

    After major life events

    Marriage automatically revokes your existing nomination. You need to create a new one. Divorce doesn’t automatically revoke it, so you must take action. The birth of children or death of a nominee also requires updates.

    Protecting Your Family’s Financial Future

    Beyond making a nomination, take these steps to ensure smooth distribution.

    Keep detailed records. Store your nomination confirmation letter with other important documents. Tell your family where to find these papers. Consider keeping copies in multiple secure locations.

    Communicate with your nominees. They should know they’re listed and understand roughly what to expect. This isn’t about exact amounts but ensuring they’re prepared to claim when necessary.

    Review annually. Set a reminder to check your nomination every year. Ask yourself if the allocations still make sense given current circumstances. Update as needed.

    Consider professional advice for complex situations. If you have multiple marriages, children from different relationships, or substantial assets, a financial planner or lawyer can help structure everything properly.

    Document your reasoning. While not legally required, leaving a note explaining your nomination choices can prevent family disputes. This is especially helpful if you’ve allocated unequal amounts or excluded certain family members.

    Making Your CPF Work Beyond Your Lifetime

    Your CPF represents years of work and careful saving. Making a nomination ensures those savings continue supporting the people you care about after you’re gone.

    The process takes less than an hour but provides lasting peace of mind. You control who benefits from your life’s work. Your family avoids unnecessary delays and legal complications during an already difficult time.

    Don’t wait for the perfect moment. Log in to your CPF account today and create or review your nomination. Your future self and your loved ones will thank you for taking this simple but crucial step in protecting their financial security.