Blog

  • How to Help Your Parents Claim All Their Merdeka Generation Benefits Without the Confusion

    How to Help Your Parents Claim All Their Merdeka Generation Benefits Without the Confusion

    Your mum just called. She’s worried about her next medical bill. Your dad mentioned something about CPF withdrawals but isn’t sure what he’s entitled to. You want to help, but between government schemes, healthcare subsidies, and retirement planning, the options feel overwhelming.

    You’re not alone. Thousands of Singaporeans in their 30s and 40s are trying to figure out how to support their parents financially without making costly mistakes or missing out on benefits that could save thousands of dollars each year.

    Key Takeaway

    Supporting your elderly parents financially starts with understanding what government benefits they already qualify for, particularly the Merdeka Generation Package, CHAS subsidies, and CPF options. Most families leave thousands of dollars unclaimed simply because they don’t know these schemes exist. This guide walks you through practical steps to assess your parents’ situation, claim all available benefits, and create a sustainable financial support plan without draining your own savings.

    Start with what your parents already have

    Before you transfer money or set up monthly allowances, take stock of what’s already available.

    Many adult children jump straight into giving cash support without realising their parents qualify for substantial government assistance. This leads to unnecessary financial strain on both generations.

    Sit down with your parents and gather these documents:

    • NRIC and birth certificates
    • CPF statements
    • MediShield Life and MediSave records
    • Bank statements from the past three months
    • Any existing subsidy cards (CHAS, PAssion Silver, Merdeka Generation)
    • Property ownership documents

    This exercise alone often reveals forgotten savings accounts, unclaimed CPF monies, or subsidy cards that expired without renewal.

    Your parents might qualify for the Merdeka Generation Package if they were born between 1950 and 1959. The package includes outpatient subsidies, MediSave top-ups, and MediShield Life premium support. Many families miss this because their parents never registered properly or lost their Merdeka Generation card.

    Check eligibility for all government schemes
    How to Help Your Parents Claim All Their Merdeka Generation Benefits Without the Confusion - Illustration 1

    Government support in Singapore is generous but fragmented. Your parents might qualify for multiple schemes simultaneously.

    Here’s a practical checklist:

    1. Verify Merdeka Generation eligibility and ensure all benefits are activated
    2. Check CHAS card tier based on household income and property value
    3. Review CPF LIFE payout options and monthly amounts
    4. Assess MediShield Life coverage and any gaps
    5. Look into Silver Support Scheme eligibility for lower-income seniors
    6. Check public transport concessions and senior citizen discounts

    The CHAS card benefits alone can save your parents hundreds of dollars monthly on GP visits, dental care, and chronic disease management.

    Most seniors qualify for higher subsidy tiers than they realise. A simple income reassessment can upgrade their card and increase savings substantially.

    Understanding CPF options at retirement age

    CPF becomes more complex after 55, and most seniors don’t fully understand their options.

    Your parents can withdraw CPF savings at 65 under specific conditions, but this isn’t always the smartest move. CPF LIFE provides guaranteed monthly payouts for life, which often beats lump sum withdrawals for long-term financial security.

    The three CPF LIFE plans offer different payout structures:

    • Standard Plan: Moderate monthly payouts with some bequest
    • Basic Plan: Higher monthly payouts with minimal bequest
    • Escalating Plan: Lower initial payouts that increase over time

    Many retirees pick the wrong plan because they don’t understand the trade-offs. If your parents need higher income now, the Basic Plan makes sense. If they want to leave more to children, the Standard Plan works better.

    You can also consider topping up your parents’ CPF to increase their monthly payouts while enjoying tax relief for yourself.

    Map out monthly income versus expenses

    Create a simple budget that shows exactly where your parents stand financially.

    List all monthly income sources:

    • CPF LIFE payouts
    • Pension or annuity payments
    • Rental income from property
    • Part-time work earnings
    • Investment dividends
    • Support from children

    Then list all expenses:

    • Housing (property tax, utilities, maintenance)
    • Food and groceries
    • Healthcare and medication
    • Insurance premiums
    • Transport
    • Personal spending and entertainment

    The gap between income and expenses tells you how much support they actually need. Many families discover the gap is smaller than expected once all government subsidies are factored in.

    If your parents struggle with budgeting, help them create a monthly budget that works on fixed income. Fixed income requires different planning than working years.

    Reduce healthcare costs before they spiral
    How to Help Your Parents Claim All Their Merdeka Generation Benefits Without the Confusion - Illustration 2

    Healthcare expenses are the biggest financial worry for most elderly Singaporeans.

    Start by managing your parents’ medical appointments strategically. Book them at CHAS-accredited clinics where subsidies apply. Consolidate specialist visits to avoid duplicate tests and unnecessary procedures.

    Make sure their MediSave is being used properly. Many seniors don’t realise how much MediSave they need and how to use it wisely for approved medical expenses.

    If your parents have chronic conditions like diabetes or high blood pressure, register them for the Chronic Disease Management Programme (CDMP). This provides additional subsidies on top of CHAS.

    “Most families overpay for healthcare simply because they don’t know which subsidies to stack. A senior with both Merdeka Generation benefits and CHAS Orange can pay as little as $5 for a GP visit that would cost $40 without subsidies.” — Community Health Assist Scheme coordinator

    Keep all medical receipts organised. If a healthcare subsidy claim gets rejected, you’ll need documentation to appeal.

    Consider housing options that free up cash

    Your parents’ home might be their biggest untapped financial resource.

    If they own an HDB flat, several schemes can convert property value into retirement income:

    The Lease Buyback Scheme allows seniors to sell part of their lease back to HDB while continuing to live there. This generates a lump sum plus monthly payouts. Should you lease back your flat depends on your parents’ age, flat value, and income needs.

    The Silver Housing Bonus pays up to $30,000 when seniors downsize to a smaller flat. Downsizing from a 4-room to a 3-room flat can also reduce conservancy charges, utilities, and maintenance costs.

    Some families consider applying for a studio apartment if their parents need less space and want to maximise cash from their current flat.

    Before making housing decisions, calculate the full financial impact. Downsizing isn’t always beneficial if the new flat’s location increases transport costs or reduces quality of life.

    Set up sustainable financial support
    How to Help Your Parents Claim All Their Merdeka Generation Benefits Without the Confusion - Illustration 3

    If your parents need regular financial help, structure it properly from the start.

    Many adult children give irregular amounts whenever parents ask. This creates stress on both sides and makes budgeting impossible.

    Instead, establish a fixed monthly support amount based on the income-expense gap you calculated earlier. Transfer it automatically on the same date each month.

    Consider splitting support among siblings fairly. One common arrangement:

    • Each sibling contributes based on their income capacity
    • One sibling handles administrative tasks (appointments, paperwork)
    • Another manages household maintenance and repairs
    • Everyone contributes to major expenses (hospitalisation, home repairs)

    Document everything. Keep records of transfers, major expenses, and shared contributions. This prevents misunderstandings later, especially when dealing with estate matters.

    If you’re worried about your own finances, set boundaries early. You can’t support your parents if you’re drowning in debt or neglecting your own retirement savings.

    Avoid these common financial mistakes

    Mistake Why it hurts Better approach
    Giving lump sums without a plan Money gets spent randomly, parents ask for more Set up structured monthly support
    Ignoring government schemes Leave thousands unclaimed annually Audit all eligibility yearly
    Paying for private healthcare unnecessarily Waste money on services subsidised elsewhere Use CHAS clinics and polyclinics first
    Withdrawing all CPF at 55 Lose guaranteed lifetime income Keep funds in CPF LIFE for monthly payouts
    Not discussing finances openly Make assumptions that lead to poor decisions Have honest conversations about needs and limits

    The common mistakes Merdeka Generation seniors make when claiming benefits often stem from lack of information rather than poor judgment.

    Plan for increasing care needs
    How to Help Your Parents Claim All Their Merdeka Generation Benefits Without the Confusion - Illustration 4

    Your parents’ financial needs will likely increase as they age.

    Healthcare costs typically rise after 75 as chronic conditions worsen and mobility decreases. Budget for this now rather than scrambling later.

    Research eldercare options before they’re needed:

    • Day rehabilitation centres for therapy and social activities
    • Home care services for meal preparation and cleaning
    • Nursing homes for round-the-clock medical care

    Each option has different costs and subsidy schemes. Choosing between ageing-in-place and sheltered housing depends on your parents’ health, your family’s capacity to help, and financial resources.

    ElderShield and CareShield Life provide some coverage for severe disability, but payouts rarely cover full care costs. Plan for the gap.

    Maximise everyday savings

    Small savings add up when you’re on a fixed income.

    Help your parents take advantage of senior discounts:

    Many seniors don’t use these benefits because they don’t know about them or find the application process confusing. Spend an afternoon helping your parents register for everything they qualify for.

    Community centres offer affordable activities that keep seniors active and social. Affordable active ageing programmes cost far less than private gyms or classes while providing similar benefits.

    Handle the emotional side of financial help

    Money conversations with parents can be awkward.

    Many seniors feel embarrassed about needing help or defensive about their financial decisions. Approach these discussions with empathy and respect.

    Frame conversations around their wellbeing rather than their mistakes. Instead of “You’re wasting money on expensive clinics,” try “I found a CHAS clinic nearby that might save you money. Want me to help you register?”

    Let your parents maintain control where possible. If they’re mentally sharp, involve them in all decisions. Offer to handle paperwork and research, but let them make final choices.

    Some parents resist help because they don’t want to burden their children. Reassure them that using available government benefits isn’t charity but their rightful entitlement as citizens who contributed to Singapore’s growth.

    Protect yourself while helping them

    Supporting your parents financially shouldn’t destroy your own financial health.

    Set clear limits on what you can afford. If you have young children, a mortgage, or your own retirement to fund, those obligations come first. You can’t pour from an empty cup.

    Don’t raid your own CPF or retirement savings to support your parents. This creates a cycle where you’ll need support from your own children later.

    If your parents have debt, understand that you’re not legally responsible for it unless you’re a guarantor. Their debt doesn’t transfer to you when they pass away, though it will be settled from their estate.

    For estate planning, help your parents understand what happens to CPF savings when they pass away. Proper nomination prevents delays and disputes.

    When professional help makes sense

    Some situations need expert guidance.

    Consider consulting a financial planner if:

    • Your parents have complex investments or multiple income sources
    • Estate planning involves significant assets or family disputes
    • You’re unsure how to structure support tax-efficiently
    • Healthcare costs are overwhelming and you need to optimise insurance coverage

    Fee-only financial planners (who don’t earn commissions on products they sell) provide unbiased advice. The cost pays for itself if they identify overlooked benefits or optimise your support structure.

    For legal matters like Lasting Power of Attorney or advance medical directives, consult an elder law specialist. These documents protect your parents and simplify decision-making if they become incapacitated.

    Supporting your parents without losing yourself

    Helping elderly parents financially is about more than money transfers and subsidy forms.

    It’s about giving them dignity, security, and peace of mind in their later years. It’s about honouring the sacrifices they made raising you while still protecting your own family’s future.

    Start with the low-hanging fruit. Claim all government benefits your parents qualify for. Optimise their existing income sources. Reduce unnecessary expenses. Only then should you consider direct financial support.

    The goal isn’t to solve every problem immediately. It’s to create a sustainable system that works for everyone involved. Small steps taken consistently beat grand gestures that burn you out.

    Your parents built their lives in an era when retirement planning looked very different. Government support schemes have evolved significantly, creating opportunities they might not recognise. Your role is to bridge that knowledge gap and help them access what they’ve earned.

    Take it one conversation, one form, one benefit at a time. You’ll be surprised how much financial pressure lifts once you’ve claimed everything available and created a clear plan. Your parents will feel more secure, and you’ll feel more confident about supporting them sustainably for years to come.
  • Should You Lease Back Your Flat Under the Lease Buyback Scheme?

    Should You Lease Back Your Flat Under the Lease Buyback Scheme?

    Your HDB flat is probably your biggest asset. But what good is all that locked-up value when you need cash for daily expenses, medical bills, or simply a more comfortable retirement? The HDB lease buyback scheme offers a way to tap into your home equity without moving out. It’s designed specifically for elderly flat owners who want to age in place while boosting their monthly income.

    Key Takeaway

    The HDB lease buyback scheme lets eligible seniors sell part of their flat lease back to HDB for cash while continuing to live there. You’ll receive a lump sum and monthly CPF LIFE payouts, but you must meet age, flat type, and income criteria. This option suits those needing retirement income without relocating, though it permanently reduces your property’s remaining lease and resale value.

    What the HDB lease buyback scheme actually does

    Think of this scheme as selling a portion of your flat’s lease back to the government.

    You don’t sell the whole flat. You sell the tail end of the lease.

    HDB buys back part of your lease, leaving you with a shorter lease of 30 to 35 years. That’s still plenty of time for most seniors to live comfortably in their own home.

    In return, you get cash. Part goes into your CPF Retirement Account to generate monthly payouts. The rest can be withdrawn as cash if you already meet your CPF minimum sum.

    You keep living in the same flat. Nothing changes day to day. You’re still the owner, just with a shorter lease.

    The scheme targets seniors in smaller flats who may not have enough retirement savings. It’s not for everyone, but for the right household, it can mean the difference between scraping by and living with dignity.

    Who can apply for the lease buyback scheme

    Not every flat owner qualifies. HDB has specific criteria.

    Flat type requirements:

    • You must own a 4-room or smaller flat
    • 5-room and executive flats are not eligible
    • The flat must be fully paid up or have minimal outstanding loan

    Age and household criteria:

    • At least one owner must be 65 years or older
    • All owners must be Singapore citizens
    • You must have owned the flat for at least five years

    Income and property limits:

    • Your average monthly household income cannot exceed $14,000
    • You cannot own any other property locally or overseas
    • If you previously owned another property, you must have disposed of it at least 30 months before applying

    If you’re part of the Merdeka Generation, you may find this scheme particularly useful alongside your existing healthcare subsidies and benefits.

    The lease buyback scheme isn’t about giving up your home. It’s about making your home work harder for you in retirement. You’ve paid off your flat. Now let it pay you back.

    How the scheme works step by step

    Here’s what happens when you apply:

    1. Submit your application through HDB’s online portal or at an HDB branch. You’ll need documents proving age, income, and flat ownership.

    2. HDB assesses your eligibility and calculates how much they’ll pay for the lease buyback. This depends on your flat’s market value and remaining lease.

    3. Choose your retained lease between 30 and 35 years. A shorter retained lease means more cash now, but less property value later.

    4. Receive your payout in two parts: CPF Retirement Account top-up first, then any remaining cash balance if you’ve met your CPF minimum sum requirements.

    5. Start receiving monthly payouts from your enhanced CPF LIFE account. The amount depends on how much was topped up and your chosen CPF LIFE plan.

    The entire process typically takes three to four months from application to payout.

    Breaking down the money you’ll receive

    Let’s use real numbers to make this concrete.

    Say you own a 3-room flat valued at $300,000 with 60 years of lease remaining. You choose to retain 30 years of lease.

    HDB might buy back 30 years’ worth of lease for approximately $150,000 (this varies based on location and market conditions).

    From that $150,000:

    • First, HDB tops up your CPF Retirement Account to the current Full Retirement Sum (about $198,800 as of 2024)
    • If the buyback proceeds don’t cover the full amount, you get what’s available
    • Any amount beyond the Full Retirement Sum goes to you as cash

    This CPF top-up immediately increases your monthly CPF LIFE payouts. The exact increase depends on your age and chosen plan.

    For example, topping up $100,000 at age 65 could boost your monthly payout by $700 to $800 for life.

    Comparing your options side by side

    Option Lease buyback scheme Downsizing Staying put
    Keep your home Yes, with shorter lease No, must move Yes, full lease
    Upfront cash Moderate High None
    Monthly income boost Yes, through CPF LIFE Yes, if you invest proceeds Only existing CPF LIFE
    Moving hassle None Significant None
    Future resale value Lower due to shorter lease N/A Maintains current trajectory
    Suitable for Those wanting stability Those willing to relocate Those with adequate savings

    The lease buyback scheme sits between doing nothing and making a major life change. It offers a middle path.

    Common concerns and what actually happens

    “What if I outlive the 30-year lease?”

    You won’t be kicked out. HDB allows you to continue living in the flat even after the lease expires. You won’t own it anymore, but you won’t be homeless either.

    “Can my children inherit the flat?”

    Yes, but only the remaining lease. If you’ve retained 30 years and pass away after 10 years, your beneficiaries inherit a flat with 20 years left. The shorter lease affects resale value significantly.

    “What if I change my mind?”

    Once the transaction completes, you cannot reverse it. This is permanent. That’s why HDB requires all owners to attend a counselling session before approving the application.

    “Will this affect my other benefits?”

    Generally no. Your Merdeka Generation healthcare subsidies and MediShield Life coverage continue as before. The scheme may affect means-tested benefits if the cash payout is large, but CPF top-ups don’t count as assessable income.

    When this scheme makes sense for you

    The lease buyback scheme works best if you:

    • Need more monthly income but want to stay in your familiar neighbourhood
    • Have limited CPF savings and won’t hit the Full Retirement Sum otherwise
    • Don’t plan to leave property inheritance as a priority
    • Feel comfortable with a shorter lease duration
    • Prefer stability over the upheaval of moving

    It’s less suitable if you:

    • Already have adequate retirement income
    • Want to maximise inheritance for your children
    • Might want to sell and upgrade in the future
    • Are considering moving overseas for retirement

    Many seniors also consider downsizing to a smaller flat as an alternative. Both options unlock home equity, but downsizing usually provides more cash upfront while requiring you to relocate.

    Alternatives worth considering

    Before committing to the lease buyback scheme, look at these other options:

    Renting out a room

    If you have spare space, renting out a bedroom provides monthly income without touching your lease. The income is tax-free up to certain limits.

    CPF top-ups from family

    Your children can top up your CPF Retirement Account directly. They get tax relief, and you get higher monthly payouts. No need to touch your property.

    Silver Housing Bonus

    If you’re willing to downsize to a 3-room or smaller flat, this scheme gives you a cash bonus of up to $30,000 on top of your sale proceeds.

    Part-time work

    Safe side hustles and part-time work can supplement your retirement income without any property transactions.

    What to do before you apply

    Don’t rush into this decision. Take these steps first:

    • Calculate your actual monthly needs. Use a realistic budget that accounts for healthcare, utilities, food, and occasional treats. Creating a monthly budget helps you know exactly how much extra income you need.

    • Check your CPF balances. Log into your CPF account and see how much you currently have. This affects how much of the buyback proceeds become cash versus CPF top-ups.

    • Discuss with your family. This decision affects inheritance and your children’s future financial plans. Have honest conversations.

    • Attend HDB’s counselling session. This is mandatory anyway, but treat it seriously. Ask all your questions. Bring your adult children if possible.

    • Get the calculations in writing. HDB will provide projections showing exactly how much you’ll receive and how your monthly payouts will increase.

    Making the most of your lease buyback proceeds

    Once you receive your payout, use it wisely.

    If you get cash beyond the CPF top-up, resist the temptation to spend it all immediately.

    Consider setting aside a portion for:

    • Medical emergencies. Even with MediSave and CHAS subsidies, unexpected health costs can arise.

    • Home maintenance. Your flat still needs upkeep. Aircon servicing, minor repairs, and eventual replacement of appliances add up.

    • Treats and experiences. You’ve worked hard. Budget some money for holidays, meals with family, or hobbies you enjoy.

    The monthly CPF LIFE payouts should cover your regular expenses. The lump sum cash is for everything else.

    Mistakes to avoid with the lease buyback scheme

    Applying without understanding the numbers

    Many seniors sign up based on rough estimates. Get exact figures. Know precisely how much you’ll receive and how it breaks down between CPF and cash.

    Forgetting about estate planning

    A shorter lease affects what you leave behind. Update your will and CPF nominations. Talk to your family about expectations. What happens to your CPF savings when you pass away becomes more complex with lease buyback proceeds.

    Not comparing with downsizing properly

    Run the numbers on both options. Sometimes selling your flat and buying a smaller one generates more total cash, even after moving costs and stamp duty.

    Choosing the shortest possible lease without thinking ahead

    Retaining only 30 years instead of 35 years gives you more money now, but it dramatically reduces your flat’s value sooner. If circumstances change and you need to sell, a flat with 15 years left is much harder to sell than one with 20 years.

    Your next steps

    If the HDB lease buyback scheme sounds right for your situation, here’s what to do:

    Start by using HDB’s online calculator to get a rough estimate of your potential proceeds. You’ll find it on the HDB website under “Lease Buyback Scheme.”

    Gather your documents: NRIC, latest income tax statements, CPF statements, and HDB flat documents.

    Book an appointment at your nearest HDB branch. The officers there can answer specific questions about your situation.

    Bring a family member or trusted friend to the appointment. Two sets of ears catch more details than one.

    Don’t feel pressured to decide on the spot. Take the information home. Sleep on it. Discuss with family. This is a permanent decision that deserves careful thought.

    Making your flat work for your retirement

    The HDB lease buyback scheme isn’t perfect for everyone. But for seniors who need more monthly income and want to stay in their homes, it offers a practical middle ground. You’re not gambling on investments or making drastic life changes. You’re simply converting part of your property’s value into reliable monthly cash flow.

    The key is going in with eyes open. Understand exactly what you’re giving up and what you’re getting. Run the numbers. Talk to your family. Compare alternatives. Then make the choice that fits your specific retirement needs and priorities. Your home has sheltered you for decades. Now it can support you financially too, if you decide that’s the right path forward.

  • How to Apply for a Studio Apartment Under the Silver Housing Bonus Scheme

    How to Apply for a Studio Apartment Under the Silver Housing Bonus Scheme

    Thinking about downsizing your HDB flat to boost your retirement funds? The Silver Housing Bonus (SHB) scheme can put up to $30,000 into your CPF Retirement Account when you move to a smaller home. But many seniors miss out simply because they don’t know the application steps or assume the process is too complicated.

    Key Takeaway

    The Silver Housing Bonus gives eligible seniors aged 65 and above up to $30,000 when they downsize to a smaller HDB flat. You apply through HDB when purchasing your replacement flat, and the bonus goes directly into your CPF Retirement Account. Your household income and property ownership affect your eligibility, and you must meet specific conditions including maintaining a minimum CPF balance after the move.

    Who can receive the Silver Housing Bonus

    Before you start the application, make sure you meet the basic requirements.

    You must be at least 65 years old when you apply. Your spouse, if you’re applying as a couple, must also be 65 or above.

    Your current flat must be a 3-room or larger HDB unit. You’ll be moving to a smaller flat, either a 2-room Flexi or 3-room flat.

    Average gross household income matters. If you’re single, your monthly income must not exceed $6,000. For couples or families, the combined household income cap is $12,000 per month.

    Property ownership affects your eligibility too. You can own only one property at the time of application, which is the flat you’re selling. If you or anyone in your household owns other properties, including private property, you won’t qualify unless the total annual value of all properties stays below $21,000.

    You must not have received the Silver Housing Bonus before. This is a one-time benefit.

    “Many seniors think they don’t qualify because they have some savings or own their flat outright. The scheme actually looks at your monthly income and property ownership, not your total wealth. Don’t rule yourself out before checking the full criteria.” (HDB eligibility guidelines)

    Understanding your bonus amount

    How to Apply for a Studio Apartment Under the Silver Housing Bonus Scheme — image 1

    The Silver Housing Bonus isn’t a fixed sum. Your bonus amount depends on your replacement flat type and your property ownership situation.

    If you’re moving to a 2-room Flexi flat, you can receive up to $30,000. Moving to a 3-room flat gets you up to $15,000.

    But there’s a catch. If you or anyone in your household owns any other property, including private property with annual value, your bonus gets reduced by $1 for every $1 of annual value above $0, up to $21,000.

    Here’s how it works in practice:

    Your situation Replacement flat Maximum bonus
    No other property 2-room Flexi $30,000
    No other property 3-room flat $15,000
    Own property with $10,000 annual value 2-room Flexi $20,000
    Own property with $15,000 annual value 3-room flat $0

    The bonus goes straight into your CPF Retirement Account. You cannot receive it as cash. This ensures the money supports your retirement income through CPF LIFE payouts.

    Checking your CPF balance requirements

    The Silver Housing Bonus comes with a mandatory CPF top-up requirement. This ensures you maintain adequate retirement savings after downsizing.

    After you sell your current flat and buy the smaller one, you must have at least $60,000 in your CPF Retirement Account. This includes the Silver Housing Bonus amount.

    If you’re applying as a couple, each person must meet this $60,000 threshold individually. Your spouse’s CPF balance doesn’t count towards your requirement.

    Let’s say you currently have $40,000 in your CPF Retirement Account. You’re moving to a 2-room Flexi flat and qualify for the full $30,000 bonus. After the sale proceeds are used for the new flat purchase and the bonus is credited, you’d have $70,000. That meets the requirement.

    But if you only have $20,000 in your CPF Retirement Account, even with the $30,000 bonus you’d only reach $50,000. You’d need to top up an additional $10,000 from your sale proceeds to meet the $60,000 minimum.

    Planning ahead helps. Before you commit to selling, calculate your expected CPF balance after the transaction. Factor in your current balance, the bonus amount, and how much of your sale proceeds you’ll need for the new flat purchase.

    Step by step application process

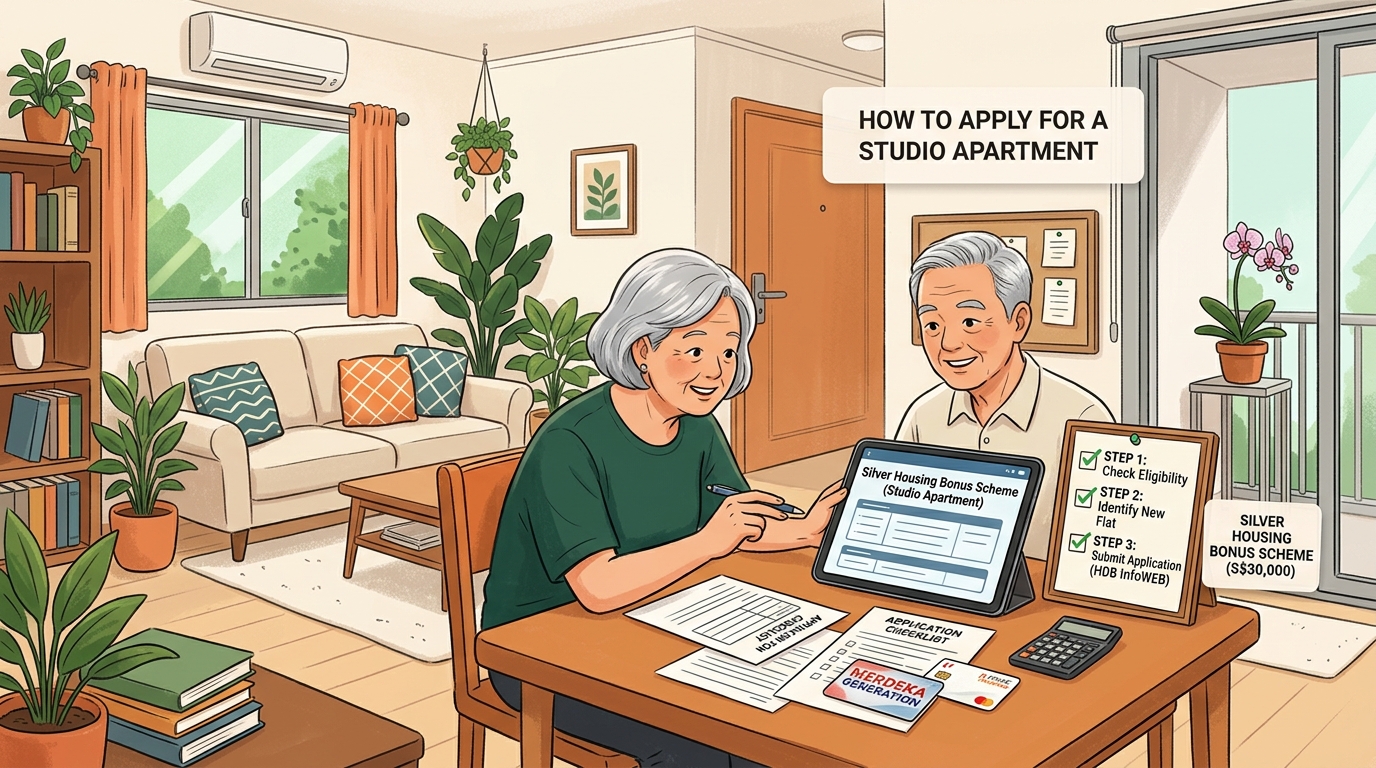
    How to Apply for a Studio Apartment Under the Silver Housing Bonus Scheme — image 2

    The application happens during your flat purchase, not as a separate process. Here’s exactly what to do.

    1. Get your HDB Flat Eligibility letter

    Start by applying for an HDB Flat Eligibility (HFE) letter. You can do this online through the HDB website or at any HDB branch.

    You’ll need your Singpass to log in. The system will ask about your household members, income, and current property ownership.

    Indicate that you want to apply for the Silver Housing Bonus during this HFE application. The system will check your eligibility automatically.

    Processing takes about 3 weeks. You’ll receive a letter stating whether you’re eligible for the scheme and your estimated bonus amount.

    2. Book your replacement flat

    Once you have your HFE letter, you can book a flat. This applies whether you’re buying from HDB directly or from the resale market.

    For new flats, participate in the HDB sales exercise. Your HFE letter confirms your eligibility for priority schemes if applicable.

    For resale flats, find a suitable unit and negotiate with the seller. Your HFE letter remains valid for 6 months, giving you time to search.

    Make sure the flat you’re buying is smaller than your current one. A 2-room Flexi or 3-room flat qualifies.

    3. Submit your resale application

    If you’re buying a resale flat, both buyer and seller submit the resale application through the HDB resale portal.

    During this application, you’ll confirm that you’re applying for the Silver Housing Bonus. The system will calculate your exact bonus amount based on your circumstances.

    You’ll also see the CPF balance requirement clearly stated. The system shows how much you need to set aside in your CPF Retirement Account.

    4. Complete the flat purchase

    Attend the HDB appointment to complete the purchase. Bring all required documents including identification, income proof, and your HFE letter.

    HDB will verify your eligibility again at this stage. They’ll check that your circumstances haven’t changed since your HFE approval.

    Sign all necessary documents. The flat purchase completes, and ownership transfers to you.

    5. Receive your bonus

    After completion, HDB credits the Silver Housing Bonus directly to your CPF Retirement Account. This happens automatically within a few weeks.

    You’ll receive a notification from CPF showing the credit. Check your CPF statement online to confirm the amount.

    The bonus becomes part of your CPF LIFE plan, generating monthly payouts during retirement. You cannot withdraw it as a lump sum.

    Common mistakes that delay applications

    Many seniors run into problems that could have been avoided with better preparation.

    Not checking income limits carefully

    Some applicants forget to include all household income sources. Rental income, part-time work, and regular financial support from children all count. If your total exceeds the cap, you won’t qualify. Calculate accurately before applying.

    Overlooking property ownership rules

    Owning a small investment property or having your name on a family member’s property title can disqualify you. Even if you don’t live there or don’t benefit financially, HDB considers it property ownership. Check all property records before starting your application.

    Selling current flat before securing replacement

    You need to own your current flat when you apply. Some seniors sell first, thinking they can apply later. That doesn’t work. Apply while you still own the flat you’re downsizing from.

    Insufficient CPF balance planning

    Not having enough in your CPF Retirement Account to meet the $60,000 requirement stops many applications. Calculate this before you commit to selling. You might need to set aside more sale proceeds than expected.

    Missing the HFE validity period

    Your HFE letter expires after 6 months. If you don’t find a replacement flat within that time, you need to reapply. Start your flat search early to avoid rushing or missing the deadline.

    Assuming automatic approval

    Meeting the basic criteria doesn’t guarantee approval. HDB reviews each application individually. Provide complete, accurate information and respond to any queries promptly.

    What happens after you receive the bonus

    How to Apply for a Studio Apartment Under the Silver Housing Bonus Scheme — image 3

    Getting the Silver Housing Bonus is just the beginning. Understanding how it affects your retirement planning matters.

    The bonus sits in your CPF Retirement Account and becomes part of your CPF LIFE plan. This means it generates monthly payouts from age 65 onwards.

    For example, if you receive the full $30,000 bonus, this increases your monthly CPF LIFE payout. The exact increase depends on your CPF LIFE plan type and your age when the bonus is credited.

    You cannot withdraw the bonus as cash, even after age 65. It stays locked in CPF LIFE to provide retirement income. This protects you from spending the money too fast.

    If you’re thinking about how this fits with other retirement planning strategies, should you downsize your HDB flat for extra retirement cash covers the broader financial considerations.

    The bonus also counts when calculating your CPF balances for other purposes. If you’re planning to top up your CPF further, should you top up your CPF LIFE after 65 explains how additional contributions work with existing balances.

    Coordinating with other retirement benefits

    The Silver Housing Bonus works alongside other government schemes available to seniors.

    If you’re part of the Merdeka Generation, you already receive healthcare subsidies and other benefits. The Silver Housing Bonus doesn’t affect these. You keep all your existing benefits.

    However, if you’re unsure about your Merdeka Generation eligibility status, how to check if you qualify for the Merdeka Generation Package in 2024 walks through the verification process.

    Some seniors worry about losing benefits when they move. Your CHAS card benefits continue at your new address. The healthcare subsidies don’t change based on your flat size. Learn more about CHAS card benefits explained to understand what remains available.

    Your MediShield Life coverage also stays active. Moving to a smaller flat doesn’t affect your healthcare protection. For details on maximizing this coverage, how to maximise your MediShield Life coverage as a Merdeka Generation senior provides practical strategies.

    Planning your finances after downsizing

    How to Apply for a Studio Apartment Under the Silver Housing Bonus Scheme — image 4

    Downsizing creates a significant financial shift. The Silver Housing Bonus is one part, but you’ll also have cash proceeds from selling your larger flat.

    Most seniors use sale proceeds to pay for the smaller replacement flat. The leftover amount can supplement retirement income or serve as emergency savings.

    Consider how much you need for monthly expenses. Your CPF LIFE payouts, including the boost from the Silver Housing Bonus, provide baseline income. Cash savings cover unexpected costs.

    Healthcare expenses often increase with age. While MediShield Life and CHAS subsidies help, some costs still come out of pocket. Managing healthcare costs in retirement offers strategies for handling medical expenses beyond subsidies.

    Creating a realistic budget helps you live comfortably on fixed income. Creating a monthly budget that works on fixed CPF LIFE and pension income shows how to structure spending when your income doesn’t fluctuate.

    Documents you’ll need throughout the process

    Gather these documents before starting your application to avoid delays.

    • NRIC for all household members applying
    • Recent payslips or income statements covering the last 12 months
    • CPF contribution history printout from the CPF website
    • Current flat ownership documents showing you as the registered owner
    • Property tax statements if you own any other property
    • HDB Flat Eligibility letter once approved
    • Resale flat listing or booking documents for your replacement flat

    Keep both physical and digital copies. Some appointments require original documents, while online applications need scanned versions.

    If you’re missing any documents, request them early. CPF statements take a few days to generate. Property ownership searches through IRAS can take up to a week.

    Getting help with your application

    You don’t have to figure this out alone. Several resources can guide you through the process.

    HDB branches offer face-to-face assistance. Staff can review your eligibility, explain requirements, and help with online submissions. Book an appointment to avoid long waits.

    The HDB hotline answers questions about the scheme. Call 1800-225-5432 during office hours. Have your NRIC ready for identity verification.

    Community centres and senior activity centres sometimes run workshops on housing schemes for elderly residents. These sessions explain the process in simple terms and answer common questions.

    If you prefer written guidance, the HDB website has detailed information pages. Search for “Silver Housing Bonus” to find official guidelines, eligibility criteria, and application instructions.

    For seniors who need help avoiding common pitfalls with government benefits, 5 common mistakes Merdeka Generation seniors make when claiming benefits highlights issues to watch for.

    Making the most of your downsizing decision

    Applying for the Silver Housing Bonus is straightforward when you know the steps. Start by checking your eligibility carefully, especially income limits and property ownership. Get your HFE letter early to allow time for flat hunting. Calculate your CPF balance requirements before committing to sell. Follow the application process during your flat purchase, not as a separate task.

    The bonus boosts your retirement income through higher CPF LIFE payouts. Combined with proceeds from selling your larger flat, downsizing can significantly improve your financial security in retirement. Take time to plan how you’ll use both the bonus and any cash proceeds wisely.

    Don’t let uncertainty stop you from exploring this option. Thousands of seniors have successfully applied for the Silver Housing Bonus and moved to comfortable, more manageable homes. With proper preparation and understanding of the process, you can too.

  • What Happens to Your CPF Savings When You Pass Away? Estate Planning Essentials

    What Happens to Your CPF Savings When You Pass Away? Estate Planning Essentials

    Your CPF account holds decades of savings. But have you thought about where all that money goes when you’re no longer around?

    Most Singaporeans assume their CPF will automatically go to their spouse or children. The reality is more complicated. Without proper planning, your loved ones could face delays, legal complications, and unexpected tax implications. Understanding how CPF distribution works after death isn’t just about ticking boxes. It’s about protecting the people who matter most.

    Key Takeaway

    When you pass away, your CPF savings are distributed either through a CPF nomination or according to intestacy laws. Making a nomination ensures your money reaches your chosen beneficiaries faster and according to your wishes. Without one, the Public Trustee handles distribution, which can take months or years and may not align with what you intended for your family.

    Two Paths for Your CPF After Death

    Your CPF savings follow one of two routes when you die.

    The first path is through a CPF nomination. This is a legal document where you specify exactly who gets your CPF money and how much each person receives. You create this nomination while you’re alive, and it overrides other claims to your CPF.

    The second path applies when you haven’t made a nomination. Your CPF becomes part of your estate and gets distributed according to the Intestate Succession Act or Muslim inheritance law, depending on your religion. The Public Trustee’s Office steps in to manage the distribution.

    The difference between these two paths is significant. One gives you control. The other leaves it to legislation that might not match your wishes.

    Understanding CPF Nominations

    A CPF nomination is your direct instruction to the CPF Board about who should receive your savings.

    You can nominate anyone. Your spouse, children, parents, siblings, friends, or even charitable organisations. There’s no restriction on who qualifies as a nominee. You decide the proportion each person receives, whether that’s equal shares or different amounts.

    The nomination covers all your CPF accounts. This includes your Ordinary Account, Special Account, MediSave Account, and Retirement Account. It also covers any CPF investments you hold and any remaining funds in your CPF LIFE plan.

    Here’s what makes nominations powerful. The money goes directly to your nominees without passing through your estate. This means faster distribution, no probate delays, and no estate duty considerations for CPF savings.

    You can make two types of nominations. A general nomination splits your CPF among your chosen beneficiaries. A revocable nomination allows you to change or cancel it anytime. Once you make a nomination, it stays valid until you revoke it or circumstances change, like getting married or divorced.

    What Happens Without a Nomination

    When you die without a CPF nomination, your savings don’t vanish. But getting them becomes more complicated for your family.

    The CPF Board transfers your savings to the Public Trustee’s Office. From there, distribution follows strict legal rules. For non-Muslims, the Intestate Succession Act determines who gets what. For Muslims, the Syariah Court applies Islamic inheritance law.

    Under intestacy rules, your spouse and children typically receive priority. But the exact split depends on your family structure. If you’re survived by a spouse and children, they share the estate. If you have no spouse but have children, they split everything equally. If you have no children, your parents may receive a share.

    This process takes time. Months, sometimes years. Your family needs to apply to the Public Trustee, provide documentation, and wait for processing. During this period, they cannot access your CPF savings, even if they desperately need the funds for immediate expenses.

    The distribution might not match what you would have wanted. Perhaps you wanted to give more to a child with special needs, or less to someone who’s financially secure. Intestacy laws don’t consider these personal circumstances. They follow fixed formulas.

    How to Make a CPF Nomination

    Creating a CPF nomination is straightforward. You have three options.

    Online through CPF website

    1. Log in to your CPF account using Singpass
    2. Navigate to the “My Requests” section
    3. Select “Nominations”
    4. Fill in your nominees’ details and proportions
    5. Review and submit

    The online method is free and takes about 15 minutes. You need your nominees’ full names, NRIC or passport numbers, and relationship to you.

    At a CPF Service Centre

    Visit any CPF Service Centre with your NRIC. A staff member will help you complete the nomination form. This option works well if you prefer face-to-face guidance or have complex family situations.

    Through a lawyer

    For more complicated estates or if you want legal advice, a lawyer can help draft your nomination. This costs more but ensures everything is properly documented.

    After submission, CPF sends a confirmation letter to your registered address. Keep this document safe. Your nominees don’t receive copies, but you should inform them about the nomination so they know to claim it when the time comes.

    Who Should You Nominate

    Choosing nominees requires careful thought.

    Start with your immediate dependents. Who relies on you financially? Your spouse might need funds to maintain the household. Children pursuing education need support. Elderly parents might depend on your assistance.

    Consider each person’s financial situation. Someone with stable income and substantial savings might need less than a family member facing financial challenges. You can allocate different percentages to reflect these needs.

    Think about special circumstances. A child with disabilities might need more to cover long-term care. A spouse without CPF savings of their own might need a larger share. These personal factors matter more than equal distribution.

    You can nominate minors. If a nominee is under 18 when you die, the Public Trustee holds their share until they reach adulthood. You can also appoint a trustee to manage the funds for young children.

    Don’t forget about updating your nomination. Life changes. Marriages, divorces, births, and deaths all affect who should receive your CPF. Review your nomination every few years or after major life events.

    Common Mistakes to Avoid

    Many people make preventable errors with CPF nominations. Here’s what to watch out for.

    Mistake Why It’s a Problem How to Fix It
    Not making a nomination at all Delays distribution and removes your control Create one today, even a simple version
    Forgetting to update after divorce Your ex-spouse might still receive funds Revoke and create a new nomination immediately
    Using unclear percentages Creates confusion and potential disputes Ensure proportions add up to exactly 100%
    Not informing nominees They might not know to claim the money Tell them about the nomination and where to find documents
    Assuming your will covers CPF CPF nominations override wills Make a separate CPF nomination

    The biggest mistake is procrastination. Many people think they’ll do it later when they’re older. But accidents and illnesses don’t wait for convenient timing. Making a nomination in your 30s or 40s is just as important as doing it at 60.

    The Claiming Process for Beneficiaries

    When you pass away, your nominees need to claim the CPF savings. Here’s how the process works.

    Your family should notify CPF Board of your death. They can do this by submitting a death certificate to any CPF Service Centre or through the CPF website. The board then contacts all nominees listed in your nomination.

    Each nominee receives a notification letter. This letter explains their entitlement and provides claim forms. They need to complete these forms and submit them with supporting documents like their NRIC and proof of relationship.

    If you made a nomination, the process is relatively fast. CPF typically disburses the money within a few weeks after receiving all required documents. The funds go directly to each nominee’s bank account.

    Without a nomination, nominees must wait for the Public Trustee to complete the estate distribution. This can take six months to several years, depending on the estate’s complexity.

    For CPF LIFE members, any remaining balance gets distributed. If you were receiving monthly payouts, these stop upon death. Any funds left in your retirement account after accounting for insurance coverage go to your nominees or estate.

    CPF and Your Overall Estate Plan

    Your CPF nomination works alongside other estate planning tools, not in isolation.

    A will handles your other assets. Your property, bank accounts, investments, and personal belongings all fall under your will’s instructions. But your will cannot override a CPF nomination. These are separate legal instruments.

    Some people use a Lasting Power of Attorney (LPA) for healthcare and financial decisions while they’re alive but incapacitated. An LPA doesn’t affect what happens to your CPF after death. That’s still controlled by your nomination or intestacy laws.

    If you’re planning your retirement finances carefully, consider how your CPF fits into your overall legacy. Perhaps you want to use CPF funds for immediate family needs while leaving other assets for extended family or charity.

    Think about tax implications too. While CPF savings themselves aren’t subject to estate duty in Singapore, they form part of your overall financial picture. Proper planning ensures your beneficiaries receive maximum benefit with minimum complications.

    Special Considerations for Different Life Stages

    Your CPF nomination needs change as you move through life.

    In your 30s and 40s

    You might have young children and a mortgage. Consider nominating your spouse as the primary beneficiary to help maintain the household. Allocate portions to children with trustees managing their shares until adulthood.

    In your 50s and 60s

    Children might be financially independent now. You could adjust proportions to support elderly parents or increase your spouse’s share. This is also when many people review their CPF withdrawal options and need to align nominations with retirement plans.

    After 65

    Your CPF might be in CPF LIFE, providing monthly income. Review your nomination to ensure remaining balances go where you want. Consider how your MediSave needs might affect the amount available for distribution.

    After major life events

    Marriage automatically revokes your existing nomination. You need to create a new one. Divorce doesn’t automatically revoke it, so you must take action. The birth of children or death of a nominee also requires updates.

    Protecting Your Family’s Financial Future

    Beyond making a nomination, take these steps to ensure smooth distribution.

    Keep detailed records. Store your nomination confirmation letter with other important documents. Tell your family where to find these papers. Consider keeping copies in multiple secure locations.

    Communicate with your nominees. They should know they’re listed and understand roughly what to expect. This isn’t about exact amounts but ensuring they’re prepared to claim when necessary.

    Review annually. Set a reminder to check your nomination every year. Ask yourself if the allocations still make sense given current circumstances. Update as needed.

    Consider professional advice for complex situations. If you have multiple marriages, children from different relationships, or substantial assets, a financial planner or lawyer can help structure everything properly.

    Document your reasoning. While not legally required, leaving a note explaining your nomination choices can prevent family disputes. This is especially helpful if you’ve allocated unequal amounts or excluded certain family members.

    Making Your CPF Work Beyond Your Lifetime

    Your CPF represents years of work and careful saving. Making a nomination ensures those savings continue supporting the people you care about after you’re gone.

    The process takes less than an hour but provides lasting peace of mind. You control who benefits from your life’s work. Your family avoids unnecessary delays and legal complications during an already difficult time.

    Don’t wait for the perfect moment. Log in to your CPF account today and create or review your nomination. Your future self and your loved ones will thank you for taking this simple but crucial step in protecting their financial security.

  • What to Do When Your Healthcare Subsidy Claim Gets Rejected

    What to Do When Your Healthcare Subsidy Claim Gets Rejected

    Getting a rejection letter for your healthcare subsidy or insurance claim feels like a punch to the gut. You followed the rules, submitted the forms, and expected the coverage you’re entitled to. Now you’re stuck with a bill and a confusing explanation that doesn’t make sense.

    Key Takeaway

    When your health insurance claim or subsidy gets denied, don’t panic. Most rejections happen due to paperwork errors, missing documents, or misunderstood eligibility rules. You have the right to appeal within specific timeframes. Gather your medical records, understand the exact denial reason, contact your insurer or subsidy provider immediately, and follow their formal appeal process. Many denials get overturned with proper documentation.

    Why healthcare claims and subsidies get rejected

    Understanding the reason behind your rejection is the first step to fixing it.

    Most denials fall into a few common categories. Your claim might have been flagged for incomplete information. Perhaps your doctor’s referral letter didn’t include specific details the insurer needed. Or the treatment code on your bill doesn’t match what your policy covers.

    Timing issues cause plenty of rejections too. You might have submitted your claim after the deadline. Some policies require pre-approval for certain procedures, and going ahead without it triggers an automatic denial.

    Eligibility problems are another major culprit. If you’re applying for Merdeka Generation subsidies but the system shows you don’t meet the age criteria, your claim gets rejected. Sometimes it’s just a database error, but you need to prove your eligibility.

    Here are the most frequent rejection reasons:

    • Missing or incomplete medical documentation
    • Treatment not covered under your policy or subsidy scheme
    • Late submission past the claim deadline
    • Pre-approval not obtained before treatment
    • Eligibility criteria not met or not verified
    • Billing codes that don’t match approved procedures
    • Duplicate claims already processed
    • Policy lapsed or premium payments overdue

    Steps to take immediately after receiving a denial

    What to Do When Your Healthcare Subsidy Claim Gets Rejected - Illustration 1

    Time matters when dealing with rejections. Most appeal windows are tight.

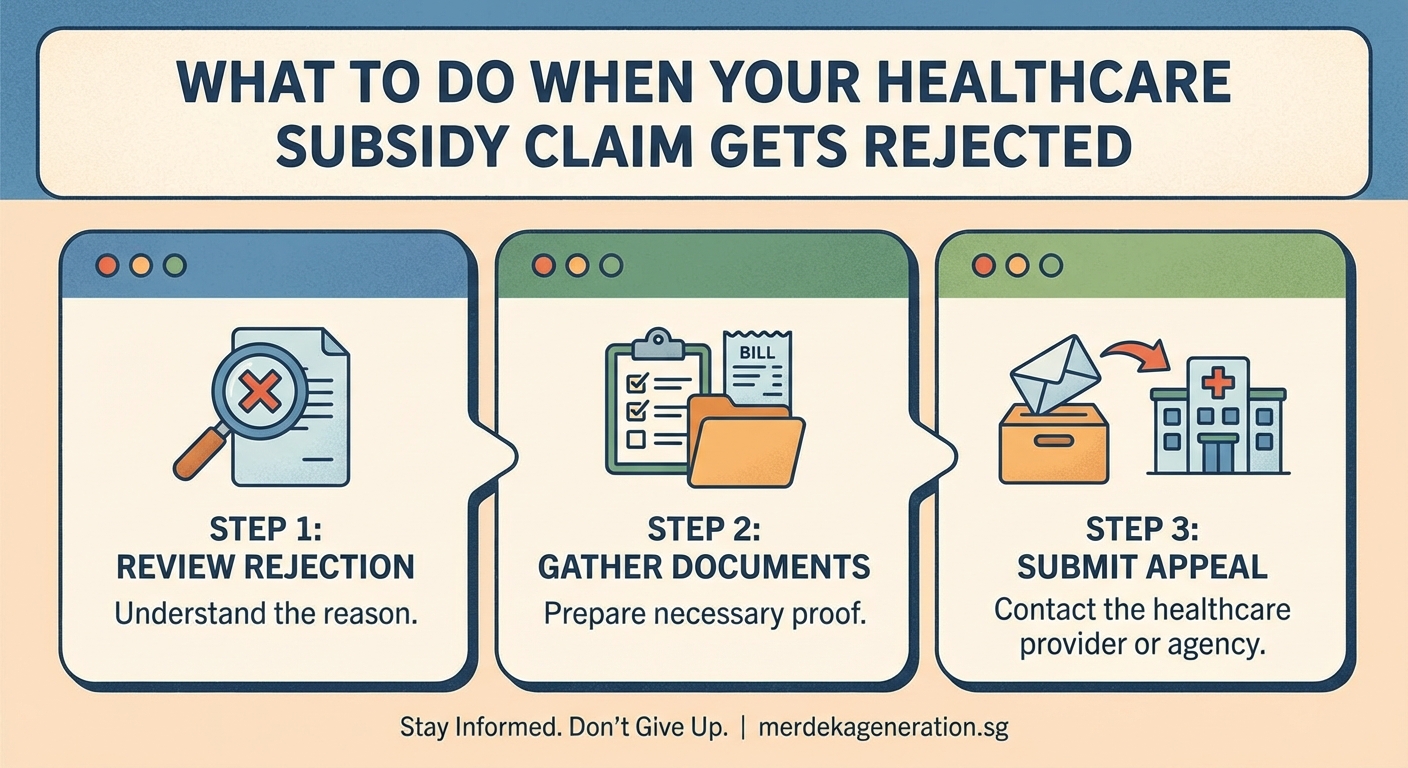
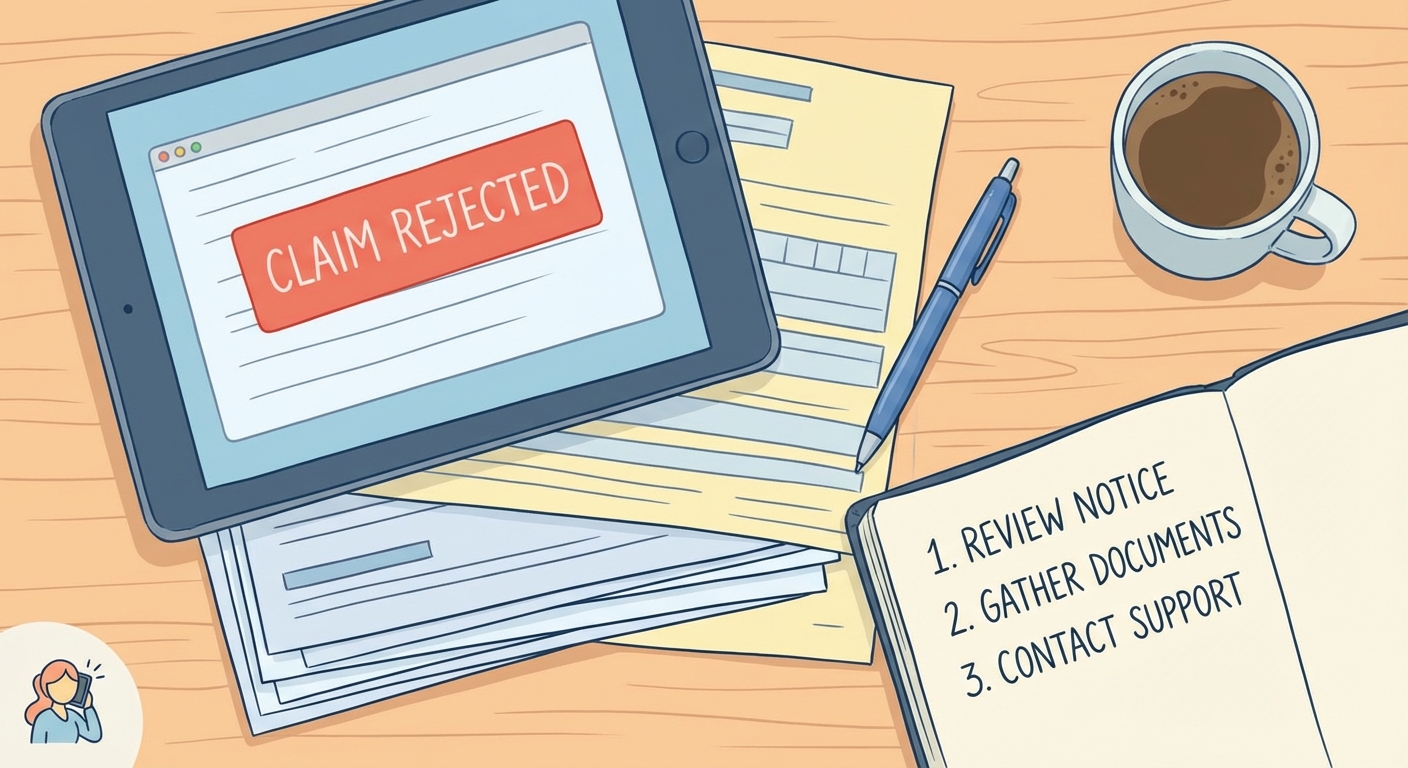
    Step 1: Read the rejection letter carefully

    Your denial notice contains crucial information. Look for the specific reason code or explanation. Check the date by which you must file an appeal. Note the contact person or department handling your case.

    Don’t skip the fine print. Sometimes the letter includes forms you need to complete or documents you must provide.

    Step 2: Contact your provider or insurer right away

    Call the number on your rejection letter. Ask for clarification on anything you don’t understand. Request a detailed explanation of why your claim was denied.

    Take notes during the call. Write down the name of the person you spoke with, the date, and what they told you. This documentation helps if you need to escalate later.

    Step 3: Gather all relevant documents

    Pull together every piece of paper related to your claim. This includes your original application, medical receipts, doctor’s letters, referral notes, and any correspondence with the insurer or government agency.

    If you’re claiming Merdeka Generation subsidies, make sure you have proof of eligibility. Your Merdeka Generation card, NRIC, and any verification letters should be in your file.

    Step 4: Check your policy or subsidy terms

    Go back to your insurance policy document or the official Merdeka Generation Package guidelines. Verify whether the treatment or service should actually be covered.

    Sometimes what seems like an error is actually a legitimate exclusion you missed. Other times, you’ll find clear evidence that the denial was wrong.

    Step 5: Submit your appeal within the deadline

    Most insurers give you 30 to 90 days to appeal. Government subsidy programs have their own timelines. Missing the deadline usually means losing your right to challenge the decision.

    Follow the exact appeal process outlined in your rejection letter. Use the correct forms, submit to the right address or email, and include all supporting documents.

    Step 6: Follow up regularly

    Don’t assume your appeal is being processed just because you sent it. Call or email every week to check the status. Keep records of every interaction.

    Persistence pays off. Many claims get resolved simply because someone kept asking.

    How to write an effective appeal letter

    Your appeal letter needs to be clear, factual, and persuasive.

    Start with your personal details: name, policy number or subsidy ID, claim number, and contact information. State clearly that you’re appealing the denial dated [specific date].

    Explain why you believe the denial was incorrect. Reference specific policy clauses or subsidy guidelines that support your position. Attach copies of all supporting documents.

    “Keep your appeal letter professional and focused on facts. Emotional language rarely helps. Stick to what the policy says, what documentation proves, and why the denial doesn’t align with the terms you agreed to.”

    Include a timeline of events if relevant. For example, if you were told verbally that a treatment was covered, mention that conversation and any follow-up you did.

    End with a clear request: “I am requesting that you reverse the denial and approve my claim for [specific amount] based on the evidence provided.”

    Common mistakes that lead to rejected appeals

    What to Do When Your Healthcare Subsidy Claim Gets Rejected - Illustration 2

    Even people with valid claims lose appeals because of avoidable errors.

    Mistake Why It Hurts Your Case How to Avoid It
    Submitting incomplete documentation Gives the reviewer an easy reason to deny again Create a checklist of required documents before sending
    Missing the appeal deadline Automatic rejection regardless of merit Mark the deadline on your calendar immediately
    Not addressing the specific denial reason Reviewer thinks you didn’t understand the issue Quote the exact denial reason in your appeal
    Using emotional or aggressive language Makes reviewers less sympathetic Stay professional and factual throughout
    Failing to provide medical necessity proof Insurer can claim treatment was optional Get a detailed letter from your doctor explaining why treatment was necessary
    Submitting duplicate or contradictory information Raises red flags about claim validity Review all documents for consistency before submission

    Understanding your rights as a healthcare consumer

    You have more protection than you might realize.

    In Singapore, insurance companies must follow guidelines set by the Monetary Authority of Singapore. They’re required to handle claims fairly and respond to appeals within reasonable timeframes.

    For government subsidies like the Merdeka Generation Package, you can escalate to the relevant ministry if you believe you’ve been treated unfairly. The process is transparent, and officials are required to review your case properly.

    If your insurer repeatedly denies valid claims or fails to follow their own procedures, you can file a complaint with the Financial Industry Disputes Resolution Centre. This independent body helps resolve disputes between consumers and financial institutions.

    For subsidy-related issues, the Ministry of Health has channels for feedback and appeals. Don’t hesitate to use them if you’re not getting answers through normal channels.

    Special considerations for Merdeka Generation subsidies

    Merdeka Generation members have specific benefits that sometimes get confused with general healthcare subsidies.

    Your Merdeka Generation Package includes subsidies for outpatient care, MediShield Life premiums, and long-term care. Each component has different eligibility rules and claim processes.

    If your subsidy claim gets rejected, check whether you’re actually eligible for that specific benefit. For instance, the outpatient care subsidies work differently from the MediShield Life premium subsidies.

    Sometimes rejection happens because the clinic or hospital didn’t properly verify your Merdeka Generation status at the point of service. If you showed your card but the subsidy wasn’t applied, contact the healthcare provider first. They may need to resubmit the claim with correct coding.

    Lost your Merdeka Generation card? That could be why your claim was rejected. Get a replacement before trying to claim subsidies.

    Common Merdeka Generation subsidy claim issues include:

    • Healthcare provider not registered under the scheme
    • Services provided outside the covered categories
    • Failure to present the Merdeka Generation card during visit
    • Database not updated with your eligibility status
    • Confusion between Pioneer Generation and Merdeka Generation benefits

    The differences between Pioneer and Merdeka Generation packages matter. Make sure you’re claiming the right benefits for your generation.

    When to escalate beyond the initial appeal

    Sometimes your first appeal doesn’t work. That doesn’t mean you’re out of options.

    If your appeal gets denied again, request a detailed written explanation. Ask specifically which policy clause or regulation supports their decision. This information helps you decide whether to escalate further.

    For private insurance, your next step is usually an internal review at a higher level within the company. Request this in writing and provide any additional documentation you’ve gathered.

    If internal reviews don’t resolve the issue, external dispute resolution becomes necessary. The Financial Industry Disputes Resolution Centre handles cases where insurers and policyholders can’t reach agreement. There’s a small fee, but it’s worth it for significant claims.

    For government subsidies, escalate to the supervising ministry. Write a formal letter explaining your situation, what you’ve tried so far, and why you believe the rejection is incorrect. Include copies of all correspondence and supporting documents.

    How to prevent future claim rejections

    Learning from a rejection helps you avoid the same problem next time.

    Always verify coverage before receiving treatment. Call your insurer or check the subsidy guidelines online. Get written confirmation if possible.

    Keep meticulous records. Save every receipt, every letter from your doctor, and every form you submit. Take photos of documents before mailing them.

    Submit claims promptly. Don’t wait until the last minute. Early submission gives you time to fix problems if something’s missing.

    Understand your policy inside and out. Read the fine print at least once. Know what’s covered, what’s excluded, and what requires pre-approval.

    For Merdeka Generation benefits, stay updated on any changes to the package. The government occasionally adjusts eligibility criteria or covered services. Checking your eligibility regularly prevents surprises.

    Many seniors make common mistakes when claiming benefits. Learning what these are helps you avoid them.

    Getting help with complex cases

    Some rejections are too complicated to handle alone.

    Patient advocacy services exist to help people navigate insurance and subsidy systems. Some hospitals have patient relations officers who can assist with claim issues.

    Community organizations serving seniors often provide free advice on healthcare subsidies. They understand the Merdeka Generation Package thoroughly and can spot errors in rejections.

    If your case involves significant money or ongoing treatment, consider consulting a lawyer who specializes in insurance disputes. The initial consultation fee might save you thousands in denied claims.

    Financial counsellors can also help, especially if the rejection affects your ability to pay for necessary care. They can suggest alternative funding sources or payment plans while you appeal.

    What to do while waiting for your appeal decision

    Don’t let the appeal process delay necessary treatment.

    If you need ongoing care, continue receiving it. Work out a payment plan with your healthcare provider if needed. Many clinics and hospitals are willing to defer payment while insurance issues get resolved.

    Keep all new receipts and documentation. If your appeal succeeds, you’ll need these to get reimbursed for treatments you paid for out of pocket.

    Stay on top of your appeal status. Set reminders to follow up every week. The squeaky wheel really does get the grease in these situations.

    If financial pressure is mounting, look into additional healthcare subsidies you might qualify for. These can provide relief while your main claim is being resolved.

    Consider whether maximizing your MediShield Life coverage could prevent similar issues in future.

    Making the system work for you

    Rejected claims feel personal, but they’re usually just administrative hiccups.

    The healthcare and insurance systems in Singapore have multiple safety nets built in. Appeals exist because mistakes happen. Reviewers understand that paperwork gets confusing, especially for complex government schemes.

    Your persistence matters more than anything else. People who follow up consistently and provide thorough documentation usually get their legitimate claims approved eventually.

    Don’t let one rejection discourage you from claiming benefits you’ve earned. The Merdeka Generation Package exists to support you. Government subsidies and insurance coverage are your rights as a policyholder and citizen.

    Take it one step at a time. Read the rejection letter, gather your documents, write your appeal, and follow up. Most claims that deserve approval eventually get it.

    Stay organized, stay patient, and don’t give up on money that rightfully belongs to you.

  • Can Your Spouse Enjoy Merdeka Generation Benefits If Only You Qualify

    Can Your Spouse Enjoy Merdeka Generation Benefits If Only You Qualify

    Many married couples assume that government healthcare packages automatically cover both partners. The reality is more nuanced, especially when it comes to the Merdeka Generation Package. If you qualify but your spouse doesn’t, you might be wondering whether they can tap into any of your benefits or if they’re left to manage on their own.

    Key Takeaway

    Merdeka Generation benefits are individual entitlements that cannot be transferred or shared with a spouse. Each person must meet the eligibility criteria independently. However, non-qualifying spouses may access other government schemes like CHAS subsidies or MediShield Life premium support. Understanding these alternatives helps couples plan their healthcare finances more effectively and avoid gaps in coverage.

    Understanding the individual nature of Merdeka Generation benefits

    The Merdeka Generation Package was designed to recognise Singaporeans born between 1950 and 1959 who contributed to nation-building during critical years. The benefits are tied to individual citizenship and birth year, not household status.

    This means your spouse cannot use your Merdeka Generation subsidies, even if you’re legally married and sharing household expenses. The government tracks benefits through NRIC numbers, and each subsidy claim is matched to the qualifying individual’s medical records.

    Here’s what this means in practice. If you visit a CHAS clinic and receive your Merdeka Generation subsidy, your spouse cannot claim that same subsidy tier unless they also qualify. They would need to meet the eligibility requirements on their own merit.

    The same applies to MediSave top-ups, CareShield Life incentives, and MediShield Life premium subsidies. These flow directly into individual accounts and cannot be pooled or transferred between spouses.

    Why spousal transfers aren’t permitted

    Government healthcare schemes in Singapore operate on an individual entitlement basis for several important reasons.

    First, the benefits are structured to reward specific cohorts for their historical contributions. The Merdeka Generation saw Singapore through critical nation-building years, and the package honours that specific group.

    Second, allowing transfers would complicate administration and create potential for abuse. Tracking individual eligibility is straightforward. Tracking household arrangements, divorces, remarriages, and shared benefits would require a much more complex system.

    Third, Singapore’s healthcare financing philosophy emphasises personal responsibility alongside government support. Each citizen is expected to build their own MediSave, CPF, and insurance coverage throughout their working years.

    If you’re checking whether you qualify, remember that your qualification has no bearing on your spouse’s status. Each person stands on their own eligibility.

    What happens when only one spouse qualifies

    Let’s look at a common scenario. Mr Tan was born in 1955 and qualifies for the Merdeka Generation Package. His wife was born in 1961 and does not qualify because she falls outside the birth year range.

    When Mr Tan visits a CHAS GP, he pays around $18.50 after his Merdeka Generation subsidy. Mrs Tan, visiting the same clinic for the same condition, might pay $28.50 with her standard CHAS subsidy (assuming she qualifies for CHAS based on household income).

    At the polyclinic, Mr Tan enjoys an additional 25% discount on top of standard subsidies. Mrs Tan receives only the standard polyclinic subsidy rates.

    For MediShield Life premiums, Mr Tan receives an additional 5% to 10% subsidy. Mrs Tan does not get this extra discount, though she may qualify for other premium subsidies based on income.

    The gap can add up over time, especially if both spouses have chronic conditions requiring regular treatment.

    Alternative schemes your non-qualifying spouse can access

    Even if your spouse doesn’t qualify for Merdeka Generation benefits, they’re not without support. Several other schemes can help reduce their healthcare costs.

    CHAS subsidies are available to all Singaporean citizens based on household income and assessment type. If your spouse has chronic conditions, they can register for CHAS Chronic to receive subsidies at participating clinics.

    MediShield Life premium subsidies are available based on income. Lower-income seniors can receive significant premium support even without Merdeka Generation status.

    Pioneer Generation Package applies to those born in 1949 or earlier. If your spouse qualifies for this instead, they actually receive more generous benefits than the Merdeka Generation Package.

    Silver Support Scheme provides cash payouts to lower-income seniors who didn’t earn much during their working years. This can help offset healthcare costs indirectly.

    ElderShield or CareShield Life subsidies help with long-term care insurance premiums. While Merdeka Generation members get additional incentives, standard subsidies are still available to others.

    How to maximise household healthcare savings

    Since you can’t share Merdeka Generation benefits directly, focus on optimising each spouse’s individual entitlements.

    1. Register both spouses for all schemes they individually qualify for. Don’t assume one person’s benefits cover the household.
    2. Use the qualifying spouse’s Merdeka Generation card consistently at CHAS clinics and polyclinics to maximise subsidies.
    3. Check whether the non-qualifying spouse can access CHAS Chronic subsidies if they have chronic conditions.
    4. Review both spouses’ MediShield Life coverage and premium subsidies annually.
    5. Consider timing non-urgent treatments to take advantage of the qualifying spouse’s better subsidy rates where appropriate.

    Some couples try to work around the rules by having the qualifying spouse collect medication for both people. This doesn’t work. Doctors prescribe medication based on individual consultations and medical records. You cannot legally use someone else’s subsidised prescription.

    Common misunderstandings about spouse coverage

    Many people hold incorrect assumptions about how Merdeka Generation benefits work within marriages. Let’s clear up the most common ones.

    Misunderstanding Reality
    “My spouse can use my Merdeka Generation card at clinics” Cards are individual and tied to NRIC. Clinics verify identity before applying subsidies.
    “We can pool our MediSave top-ups” Top-ups go into individual MediSave accounts. Transfers between spouses follow standard MediSave rules, not special Merdeka Generation rules.
    “If I pass away, my spouse inherits my benefits” Benefits end with the qualifying individual. Spouses don’t inherit ongoing subsidies.
    “Household income affects my Merdeka Generation eligibility” Birth year and citizenship determine eligibility. Income doesn’t disqualify you, though it may affect other schemes like CHAS.
    “My foreign spouse can qualify if married long enough” Only Singapore citizens born 1950 to 1959 qualify. Permanent residents and foreigners are not eligible regardless of marriage.

    What to do if your spouse feels left out

    It’s natural for non-qualifying spouses to feel disappointed, especially when they see their partner receiving better subsidies for similar treatments. Here’s how to address this constructively.

    Acknowledge the feelings. The package creates a real financial gap between spouses born just a few years apart. That frustration is valid.

    Focus on what your spouse does qualify for. Help them register for CHAS, check their MediShield Life subsidies, and apply for any income-based support they’re entitled to.

    Plan your household healthcare budget based on the reality of different subsidy tiers. Don’t assume both spouses will have identical medical costs after subsidies.

    “Couples should view their combined healthcare subsidies as a household resource, even if they come from different schemes. The goal is total household healthcare affordability, not perfect equality between spouses.” – Financial planning perspective

    Consider how other household resources balance out. Perhaps the qualifying spouse’s better subsidies free up money for other family needs that benefit both partners.

    Special situations worth noting

    Some scenarios create unique considerations for married couples and Merdeka Generation benefits.

    Second marriages don’t change anything. If you remarry someone younger or older, their eligibility remains based on their own birth year. Your Merdeka Generation status doesn’t transfer.

    Spousal MediSave transfers follow existing MediSave rules. You can transfer MediSave to pay for your spouse’s medical bills or insurance premiums, but this has nothing to do with Merdeka Generation benefits specifically. The transferred funds don’t carry any special subsidy status.

    Widows and widowers don’t lose their Merdeka Generation benefits if their spouse passes away. Benefits continue for life as long as you remain a Singapore citizen.

    Separated or divorced couples each keep their individual benefits. There’s no provision for transferring benefits as part of divorce settlements because benefits aren’t considered divisible property.

    If you’ve lost your Merdeka Generation card, you can get a replacement, but you still can’t authorise your spouse to use your benefits in the meantime.

    Planning ahead for couples with mixed eligibility

    Long-term planning becomes important when one spouse has better healthcare subsidies than the other.

    Start by calculating the annual difference in healthcare costs between both spouses. If the non-qualifying spouse has chronic conditions, their higher out-of-pocket costs might add up to several hundred dollars yearly.

    Set aside this difference in your household budget. Don’t let it become a surprise expense that strains your retirement finances.

    Review your MediShield Life and private insurance coverage. The non-qualifying spouse might benefit more from upgrading to an Integrated Shield Plan if they face higher baseline costs.

    Keep good records of both spouses’ medical expenses. This helps you track whether the gap is widening and whether you need to adjust your healthcare budget.

    Consider the impact on your CPF planning. Since MediSave top-ups go to the qualifying spouse, think about how this affects each person’s ability to pay for future medical expenses from their own MediSave.

    When to seek personalised advice

    While the rules around Merdeka Generation benefits and spouses are straightforward, your household’s specific situation might warrant professional guidance.

    Talk to a financial planner if you’re struggling to balance healthcare costs between spouses with different subsidy levels. They can help you optimise your overall retirement healthcare strategy.

    Consult the Ministry of Health hotline if you’re unsure about your spouse’s eligibility for other schemes. Sometimes people miss out on subsidies they actually qualify for simply because they didn’t know to apply.

    Speak with a social worker if healthcare costs are becoming unmanageable for your household. Additional assistance programmes may be available based on your specific circumstances.

    Many people make common mistakes when claiming benefits. Getting advice early can help you avoid these pitfalls and ensure both spouses maximise their individual entitlements.

    Making peace with the system

    The Merdeka Generation Package wasn’t designed to cover households or families. It targets a specific generation of Singaporeans who built the nation during formative years.

    This means some couples will have asymmetric benefits. One spouse gets more subsidies, while the other relies on different schemes.

    Rather than viewing this as unfair, treat it as one piece of your household’s total healthcare financing puzzle. Your combined CPF, MediSave, insurance, and government subsidies all work together to keep healthcare affordable.

    The qualifying spouse should use their benefits fully and consistently. The non-qualifying spouse should register for every scheme they’re individually entitled to. Together, these individual entitlements create your household safety net.

    Supporting each other through healthcare decisions

    Healthcare becomes more important as we age. When one spouse has better subsidies, it’s tempting to prioritise their care or delay the other spouse’s treatments to save money.

    Resist this temptation. Both spouses deserve timely, appropriate medical care regardless of who gets better subsidies.

    Instead, use the subsidy difference to inform where you seek care. The qualifying spouse might choose CHAS clinics more often, while the non-qualifying spouse might benefit from polyclinic care where base subsidies are already high.

    Attend medical appointments together when possible. Understanding both spouses’ health needs helps you make informed decisions about household healthcare spending.

    Remember that subsidies exist to make healthcare affordable, not to ration care based on who qualifies for what. If treatment is needed, get it. The subsidies simply determine how much you’ll pay out of pocket.

    Your household healthcare strategy matters more than any single scheme

    No single government package covers every healthcare need for every family member. The Merdeka Generation Package is one tool among many.

    Your non-qualifying spouse isn’t locked out of affordable healthcare. They just access it through different channels. CHAS, MediShield Life subsidies, polyclinic subsidies, and other schemes remain available based on their individual circumstances.

    The key is understanding what each spouse qualifies for individually, then building a household healthcare budget that accounts for both realities. Track your combined medical expenses, use each person’s subsidies fully, and plan for the difference in your retirement budget.

    Healthcare costs will continue rising as both of you age. But with proper planning and full use of each spouse’s individual entitlements, you can keep these costs manageable without relying on benefits that simply aren’t designed to be shared.

  • 5 Common Mistakes Merdeka Generation Seniors Make When Claiming Benefits

    5 Common Mistakes Merdeka Generation Seniors Make When Claiming Benefits

    Thousands of Singaporean seniors leave money on the table every year because they misunderstand how the Merdeka Generation Package works. Some miss deadlines. Others forget to bring the right documents. A few don’t even realise they qualify for subsidies they’ve already paid for through decades of taxes.

    These aren’t small oversights. They can cost you hundreds or even thousands of dollars in healthcare savings.

    Key Takeaway

    Many Merdeka Generation seniors lose out on healthcare subsidies by making five common mistakes: not verifying eligibility, missing auto-enrolment, forgetting their card, misunderstanding MediSave top-ups, and ignoring annual health screenings. Each error can cost hundreds of dollars yearly. This guide shows you how to claim every benefit you’re entitled to without confusion or delays.

    Assuming you’re automatically enrolled in everything

    The Merdeka Generation Package includes multiple benefits, but not all of them activate the moment you turn 60.

    Some subsidies require you to visit a clinic or hospital and present your Merdeka Generation card. Others need you to sign up through HealthHub or call a hotline.

    Many seniors assume that because they received their card in the mail, all benefits are already working. That’s not how it functions.

    Here’s what actually happens:

    • MediSave top-ups are credited automatically to your account once a year.
    • Outpatient subsidies only apply when you show your card at participating clinics.
    • Screen for Life health screenings require you to book an appointment and register.

    If you never activate certain benefits, you’ll pay full price without realising you qualified for a discount.

    “I went to my regular clinic for two years before the receptionist told me I could get extra subsidies with my Merdeka Generation card. I had the card at home the whole time but didn’t know I had to bring it.” — Mrs Lim, 64

    To avoid this mistake, check if you qualify for the Merdeka Generation Package first. Then make a list of every benefit and note which ones need action from you.

    Forgetting to bring your Merdeka Generation card

    Your card is the key that unlocks subsidies at the point of care.

    Without it, clinic staff can’t verify your eligibility. You’ll pay the standard rate and miss out on additional subsidies that could reduce your bill by 25% or more.

    Some seniors leave their card at home because they think their NRIC is enough. It’s not.

    Others worry about losing it, so they keep it locked away. That defeats the purpose.

    Here’s how to make sure you always have it when you need it:

    1. Store it in your wallet next to your NRIC. Treat it like a credit card you use regularly.
    2. Take a photo of both sides and save it in your phone. Some clinics accept digital proof if you forget the physical card.
    3. Set a reminder on your phone before medical appointments to double-check you have your card.

    If you’ve already lost your card, you can find out what happens if you lost your Merdeka Generation card and how to get a replacement without paying a fee.

    Mistake Consequence Solution
    Leaving card at home Pay full price instead of subsidised rate Keep card in wallet with NRIC
    Never received card Miss all subsidies at clinics Call MOH hotline to request reissue
    Card damaged or faded Staff can’t scan barcode Request replacement online via HealthHub

    Misunderstanding how MediSave top-ups work

    Every year, eligible Merdeka Generation seniors receive a MediSave top-up. The amount varies depending on your birth year and when the scheme was announced.

    But many seniors don’t realise the top-up is a one-time annual credit, not a monthly deposit.

    Some check their MediSave balance in February and see no change. They assume they didn’t get the top-up. In reality, it may arrive in March or April.

    Others confuse the Merdeka Generation top-up with other government schemes like Workfare or GST Vouchers. These are separate programmes with different eligibility rules.

    Here’s what you need to know:

    • The top-up goes directly into your MediSave account. You don’t need to apply for it.
    • It happens once per year, usually in the first quarter.
    • You can check your MediSave balance anytime through the CPF mobile app or HealthHub.

    If you don’t see the credit after six months, call CPF at 1800-227-1188 to ask why.

    Don’t assume you’re ineligible just because the timing doesn’t match your expectations.

    Skipping annual Screen for Life health checks

    The Merdeka Generation Package includes subsidised health screenings to catch chronic conditions early.

    These screenings cover diabetes, high blood pressure, high cholesterol, and certain cancers. They’re free or heavily subsidised depending on your income.

    But you have to book them yourself. They don’t happen automatically.

    Many seniors skip these checks because they feel healthy or don’t want to “waste time” at the polyclinic. That’s a costly mistake.

    Catching a condition early can save you thousands of dollars in treatment later. It can also prevent complications that affect your quality of life.

    Here’s how to make the most of your screening benefits:

    1. Log in to HealthHub and search for “Screen for Life” to see which screenings you’re due for.
    2. Book an appointment at your nearest polyclinic or participating clinic.
    3. Bring your Merdeka Generation card to enjoy the full subsidy.

    If you’re unsure which screenings apply to you, ask the clinic staff during your next visit. They can check your eligibility and book future appointments on the spot.

    Not keeping up with scheme updates

    Government schemes change. New benefits get added. Old rules get revised.

    If you only read the original Merdeka Generation Package brochure from 2019, you’re missing out on improvements made since then.

    For example, the government has expanded the list of chronic conditions covered under the Community Health Assist Scheme (CHAS). They’ve also increased subsidy amounts for certain treatments.

    But unless you actively check for updates, you won’t know about them.

    Here’s how to stay informed without getting overwhelmed:

    • Subscribe to MOH email updates so you get notifications when policies change.
    • Check the official Merdeka Generation website once every six months for the latest information.
    • Ask your clinic staff during routine visits if there are any new subsidies you should know about.

    You can also follow trusted Facebook groups or community centres that share updates in plain English. Just make sure the source is reliable and not spreading rumours.

    Common myths that lead to mistakes

    Let’s clear up a few misconceptions that cause seniors to miss out on benefits:

    Myth 1: You need to reapply every year.

    False. Once you’re enrolled, your benefits continue automatically as long as you remain eligible.

    Myth 2: The package only covers government hospitals.

    False. Many private clinics and specialist centres participate in the scheme. Check the CHAS clinic locator to find participating providers near you.

    Myth 3: If you have other subsidies, you can’t use Merdeka Generation benefits.

    False. In most cases, Merdeka Generation subsidies stack on top of existing schemes like CHAS or MediShield Life. You get more savings, not less.

    Myth 4: You lose your benefits if you move to a different address.

    False. Your eligibility is tied to your NRIC and birth year, not your residential address.

    How to fix mistakes you’ve already made

    If you’ve been missing out on benefits for months or even years, don’t panic. You can still recover some of the value.

    Here’s what to do:

    • For missed subsidies at clinics: Ask your clinic if they can retroactively apply the discount to past visits. Some will, especially if you have receipts.
    • For missed MediSave top-ups: Call CPF to confirm whether the credit was issued. If it was, you’ll see it in your transaction history.
    • For missed health screenings: Book your next appointment as soon as possible. The subsidies don’t expire as long as you’re still eligible.

    You can’t turn back time, but you can make sure you don’t repeat the same mistakes going forward.

    What to do right now

    Take these three actions today to avoid future merdeka generation benefits claiming mistakes:

    1. Find your Merdeka Generation card and put it in your wallet. If you can’t find it, request a replacement immediately.
    2. Log in to HealthHub and check your MediSave balance to confirm your top-up was credited.
    3. Book your next Screen for Life appointment if you haven’t had a health screening in the past 12 months.

    These steps take less than 30 minutes but can save you hundreds of dollars every year.

    Making every benefit count

    The Merdeka Generation Package exists because you helped build Singapore into what it is today. You’ve earned these benefits through decades of hard work.

    Don’t let simple mistakes rob you of savings that are rightfully yours. Keep your card handy, stay informed about updates, and use every subsidy available to you.

    Your health and your wallet will thank you.

  • What Happens If You Lost Your Merdeka Generation Card

    Losing your Merdeka Generation card can feel stressful, especially when you rely on it for medical subsidies and outpatient care. The good news is that your benefits remain active even without the physical card. Your eligibility is tied to your NRIC, not the card itself. Still, having a replacement makes accessing services smoother and gives you peace of mind.

    Key Takeaway

    Your Merdeka Generation benefits stay active even if you lose your card. The card is a convenience tool, not a requirement. You can request a replacement by calling the hotline at 1800-650-6060. Clinics can verify your eligibility using your NRIC. Keep your replacement card safe by storing it with your CHAS card or in a dedicated cardholder to avoid future loss.

    Your Benefits Continue Without the Card

    Many people worry that losing the card means losing their subsidies.

    That is not true.

    Your Merdeka Generation status is registered in the national database. Polyclinics, CHAS clinics, and public specialist outpatient clinics can confirm your eligibility using your NRIC number. The card serves as a visual reminder and a convenient reference, but it does not control your access to benefits.

    If you visit a clinic without your card, simply inform the staff that you are a Merdeka Generation member. They will check your NRIC and apply the appropriate subsidies. This process takes a few extra seconds but does not affect your entitlements.

    Your MediShield Life premium subsidies and CareShield Life participation incentives also remain unaffected. These are tied to your identity, not to the physical card.

    How to Request a Replacement Card

    Getting a new card is straightforward.

    Follow these steps:

    1. Call the Merdeka Generation hotline at 1800-650-6060.
    2. Provide your NRIC number and confirm your personal details.
    3. Explain that you need a replacement card due to loss or damage.
    4. The operator will verify your eligibility and arrange for a new card to be mailed to your registered address.
    5. Wait for the card to arrive within two to three weeks.

    There is no fee for the replacement. The government provides this service at no cost because they recognise the importance of the card for daily use.

    If your registered address has changed, update it during the call. This ensures the card reaches you without delay. You can also update your address online through Singpass or at any government service centre.

    Keep your NRIC handy when you call. The hotline operator will need it to verify your identity and process the replacement request efficiently.

    What to Do While Waiting for Your Replacement

    You do not need to pause your medical visits.

    Continue visiting your regular clinics and polyclinics. Inform the reception staff that you are waiting for a replacement Merdeka Generation card. They will verify your status using your NRIC and apply the subsidies as usual.

    Some people prefer to carry a copy of their welcome letter or any previous correspondence from the Merdeka Generation office. This is optional but can speed up verification at clinics that are less familiar with the process.

    If you also have a CHAS card, bring it along. Many CHAS clinics are used to checking eligibility through multiple schemes, and having your CHAS card on hand can make the process smoother.

    Common Concerns About Lost Cards

    Here are the questions most people ask:

    • Will I be charged full price at the clinic? No. Once the clinic verifies your NRIC, you receive the same subsidies as before.
    • Can someone misuse my lost card? The card has no financial value on its own. It cannot be used to withdraw money or access your accounts. It simply identifies you as a Merdeka Generation member.
    • Do I need to report the loss to the police? No. Unlike losing your NRIC or passport, there is no need to file a police report for a lost Merdeka Generation card.
    • What if I find the old card after receiving the replacement? You can keep both. The new card will have the same information. There is no harm in having a spare.

    Comparing Card Loss Scenarios and Solutions

    Different situations require slightly different approaches. This table breaks down the most common scenarios:

    Scenario What Happens Action to Take
    Card lost at home Benefits continue, card may turn up Request replacement if not found within a week
    Card lost outside Benefits continue, unlikely to recover Call hotline immediately for replacement
    Card damaged but readable Benefits continue, card still usable Request replacement if it causes issues at clinics
    Card damaged and unreadable Benefits continue, card not usable Call hotline for replacement right away
    Address changed since receiving card Benefits continue, new card sent to old address Update address before requesting replacement

    Preventing Future Loss

    Once you receive your replacement, take steps to keep it safe.

    Store it in a dedicated cardholder or wallet compartment. Many people keep their Merdeka Generation card together with their CHAS card, since both are used at the same clinics.

    Avoid carrying the card loose in your pocket or bag. It can easily slip out or get damaged.

    If you rarely visit the doctor, consider keeping the card at home in a safe place. Bring it along only when you have an appointment. This reduces the risk of losing it during daily errands.

    Some people take a photo of the card and store it on their phone. While the photo cannot replace the physical card, it provides a reference if you need to recall the card number or other details.

    Understanding the Merdeka Generation Package

    The card is part of a broader support package designed for Singaporeans born between 1950 and 1959. If you are unsure whether you qualify or want to confirm your benefits, you can check if you qualify for the Merdeka Generation Package in 2024.

    The package includes:

    • Additional subsidies at CHAS clinics, polyclinics, and specialist outpatient clinics.
    • Extra MediShield Life premium subsidies to reduce your annual insurance costs.
    • Additional participation incentives for CareShield Life, a long-term care insurance scheme.

    These benefits are automatic. You do not need to apply separately for each subsidy. Once you are registered as a Merdeka Generation member, the subsidies apply whenever you visit a participating clinic or facility.

    What Clinics Need to Know

    Most clinics are familiar with the Merdeka Generation scheme.

    When you visit without your card, the staff will ask for your NRIC. They enter it into their system, which connects to the national database. The system confirms your eligibility and applies the subsidies to your bill.

    This process is the same whether you have the card or not. The card simply speeds up the verification by a few seconds.

    If a clinic is unsure or encounters a technical issue, ask them to call the Merdeka Generation hotline for assistance. The hotline can confirm your status over the phone and guide the clinic on how to proceed.

    Other Cards You Might Confuse With the Merdeka Generation Card

    Some people mix up their Merdeka Generation card with other cards.

    Here are the main differences:

    • CHAS card: This card provides subsidies based on household income and is separate from the Merdeka Generation scheme. You can hold both cards and enjoy subsidies from both schemes at the same time.
    • Pioneer Generation card: This card is for Singaporeans born in 1949 or earlier. It offers similar benefits but is part of a different package. If you were born between 1950 and 1959, you belong to the Merdeka Generation, not the Pioneer Generation.
    • NRIC: Your identity card is essential for all transactions. The Merdeka Generation card is a supplementary card and does not replace your NRIC.

    When to Contact the Hotline

    Call the hotline if:

    • You have not received your replacement card after three weeks.
    • You need to update your address or personal details.
    • You are unsure whether you are eligible for the Merdeka Generation package.
    • A clinic refuses to apply your subsidies even after verifying your NRIC.

    The hotline operates on weekdays from 8am to 8pm and on Saturdays from 8am to 1pm. It is closed on Sundays and public holidays.

    Have your NRIC ready before calling. This speeds up the process and ensures the operator can assist you without delays.

    Why the Card Matters Even Though Benefits Continue

    The card is not mandatory, but it makes life easier.

    It serves as a visual cue for clinic staff. When you present the card, they immediately recognise your eligibility and apply the subsidies without needing to check the system. This saves time, especially during busy clinic hours.

    The card also acts as a reminder of your benefits. Many people forget which subsidies they are entitled to. Having the card on hand helps you remember to claim the full range of support available to you.

    Finally, the card is a symbol of recognition. It acknowledges your contributions to Singapore during the formative years of the nation. Carrying it is a small but meaningful way to connect with that history.

    Keeping Your Benefits Active

    Your Merdeka Generation status does not expire.

    Once you are registered, you remain eligible for life. There is no need to renew the card or reapply for benefits.

    However, you should keep your personal details updated. If you move house, change your phone number, or update your next-of-kin, inform the relevant government agencies. This ensures you continue to receive important updates and correspondence about your benefits.

    You can update your details through Singpass, at any community centre, or by calling the Merdeka Generation hotline.

    Moving Forward With Confidence

    Losing your Merdeka Generation card is inconvenient, but it does not affect your access to subsidies or support. Your benefits remain active, and getting a replacement is simple and free. Call the hotline, verify your details, and wait for the new card to arrive. In the meantime, continue visiting your clinics as usual. Your NRIC is all you need to confirm your eligibility and enjoy the full range of Merdeka Generation benefits. Keep your replacement card safe, and rest assured that your support is always there when you need it.