Category: Senior Living

  • 4 Senior-Friendly Neighbourhoods in Singapore Where Merdeka Generation Can Age Comfortably

    4 Senior-Friendly Neighbourhoods in Singapore Where Merdeka Generation Can Age Comfortably

    Choosing where to live after retirement is one of the biggest decisions you will make. For Merdeka Generation seniors, the right neighbourhood can mean the difference between feeling isolated and enjoying a vibrant, supported lifestyle. Singapore has done a lot to make many estates more age-friendly, but not all areas are equal. In this guide, we will walk you through the qualities of a senior friendly neighbourhood and highlight four places where Merdeka Generation seniors can truly age with comfort and peace.

    Key Takeaway

    Senior friendly neighbourhoods in Singapore share key features: flat walking paths, easy access to public transport (MRT/bus interchanges), nearby polyclinics and community hospitals, plenty of sheltered seating, and active ageing programmes. Four estates that excel in these areas are Bishan, Tiong Bahru, Toa Payoh, and Woodlands. Each offers unique advantages for Merdeka Generation seniors, from healthcare hubs to intergenerational community spaces. Use the table in this article to compare them against your own priorities.

    What Makes a Neighbourhood Truly Senior Friendly?

    Before we name specific estates, it helps to understand the checklist that defines a senior friendly neighbourhood. The Housing and Development Board (HDB), together with the Ministry of Health and LTA, has rolled out many improvements in recent years. Here are the key criteria you should look for:

    • Level walkways and ramps: No steep slopes or uneven pavements. Many HDB precincts now have covered linkways that connect blocks to bus stops and MRT stations.
    • Grab bars and rest points: Benches placed every few hundred metres, especially along park connectors and near market stalls.
    • Healthcare within 15 minutes: A polyclinic, a community hospital, or a CHAS GP clinic near home. This is where your Merdeka Generation outpatient subsidies really save you time and money.
    • Active ageing centres: Spaces like Senior Activity Centres (SACs) and Active Ageing Hubs that offer exercise classes, interest groups, and health screenings.
    • Good public transport connectivity: Being near an MRT station or a bus interchange means you can get around easily even if you stop driving.
    • Affordable daily essentials: Wet markets, NTUC FairPrice, Sheng Siong, and food centres that accept senior discounts and PAssion card perks.

    These elements matter because they reduce dependence on family members and let you maintain independence for longer.

    Four Standout Senior Friendly Neighbourhoods in Singapore

    Each of the four neighbourhoods below has been chosen for its combination of accessibility, healthcare access, community feel, and Merdeka Generation friendly amenities. They are not ranked in any particular order.

    1. Bishan: The Park Connector Paradise

    Bishan is a top pick for seniors who love greenery and staying active. The Bishan Ang Mo Kio Park is a huge draw, with flat walking paths that are easy on the knees. The neighbourhood has a wide variety of facilities:

    • Bishan MRT station on the Circle Line and the upcoming Cross Island Line connection makes it very connected.
    • Raffles Hospital Bishan branch and several CHAS clinics nearby.
    • Bishan Community Club runs many free active ageing programmes.
    • The Bishan Library is senior friendly, with large print collections and comfortable seating.

    For Merdeka Generation seniors, the proximity to Thompson Medical Centre and the Bishan Polyclinic means you can use your https://merdekageneration.sg/chas-card-benefits-explained-what-merdeka-generation-seniors-need-to-know/ without travelling far. Many residents also appreciate the Bishan Junction 8 shopping centre, which has senior discount days at selected retailers.

    2. Tiong Bahru: Heritage, Accessibility, and Community

    Tiong Bahru is one of Singapore's oldest housing estates, but it has been thoughtfully upgraded for ageing in place. Its pre war walk ups are balanced by newer HDB blocks with full barrier free access. What makes Tiong Bahru stand out:

    • Tiong Bahru Market is legendary for cheap and healthy hawker food. Many stallholders offer senior discounts during off peak hours.
    • Tiong Bahru Plaza and the neighbourhood shops are all within a short flat walk.
    • The Outram Park MRT interchange (East West Line, North East Line, and Thomson East Coast Line) is just a few minutes away.
    • Singapore General Hospital and Outram Community Hospital are located at the edge of the estate, giving you world class medical care a stone's throw away.
    • The Tiong Bahru Community Centre runs line dance, tai chi, and sketching classes tailored for seniors.

    For those who still drive, the estate has ample senior priority parking lots near the market. And if you ever need to claim your the nearby CHAS GP clinics are very experienced with Merdeka Generation claims.

    3. Toa Payoh: The Well Planned Heartland

    Toa Payoh was designed as a self contained satellite town, and its layout remains one of the most senior friendly in Singapore. The HDB town centre has wide covered walkways that connect almost every block to the bus interchange and MRT station.

    • Toa Payoh Polyclinic is a major healthcare hub that accepts Merdeka Generation subsidies for specialist referrals.
    • Toa Payoh Community Hospital is collocated with the polyclinic, making follow up visits easy.
    • The HDB Hub area includes a public library with large print books and a senior activity centre on level three.
    • Toa Payoh Central has sheltered seating areas with fans, perfect for morning coffee and catching up with neighbours.
    • The Safra Toa Payoh clubhouse hosts affordable fitness classes for seniors every weekday morning.

    If you are considering downsizing, Toa Payoh offers many 2 room Flexi flats designed for elderly residents, with features like emergency pull cords and slip resistant floors. You can learn more about the financial side of such a move in our guide on

    4. Woodlands: A Growing Hub for Active Ageing

    Woodlands in the north has evolved rapidly and now rivals more central estates in senior friendliness. The Woodlands Regional Centre includes a brand new integrated transport hub with direct undercover access to the MRT, bus interchange, and a shopping mall.

    • Woodlands Polyclinic is one of the largest in Singapore, with a dedicated seniors clinic that streamlines repeat prescriptions.
    • Admiralty Medical Centre and Khoo Teck Puat Hospital are a short bus ride away, offering comprehensive geriatric services.
    • The Woodlands Active Ageing Hub (Causeway Point area) runs free health talks, Zumba Gold, and gardening sessions.
    • Woodlands Galaxy Community Club has a special seniors corner with computers for digital literacy classes.
    • The Woodlands Waterfront Park has a completely flat promenade, ideal for walking or wheelchair use.

    Woodlands also has several wet markets and neighbourhood centres that accept the Merdeka Generation card for selected purchases. For seniors who need to claim several CHAS clinics in the area specialise in dental care for older adults.

    How to Evaluate a Neighbourhood: A Handy Comparison Table

    When you visit a potential neighbourhood, take this checklist with you. It covers the most important aspects from a Merdeka Generation perspective.

    Criteria What to Check Why It Matters for You
    Flat walking paths Are there slopes or steps? Is there a covered linkway from the nearest MRT to your block? Prevents falls and makes daily errands less tiring.
    Healthcare access How far is the nearest polyclinic or CHAS clinic? Does it accept MG subsidies? Reduces out of pocket costs and travel time for regular check ups.
    Food and groceries Is there a wet market or budget supermarket within 500 metres? Keeps your monthly expenses lower and supports a healthy diet.
    Community activities Are there Active Ageing Centres or senior interest groups nearby? Combats loneliness and keeps you engaged.
    Public transport Are there bus stops with benches? Is the MRT station barrier free? Ensures you can get around even if you no longer drive.
    Safety and lighting Are walkways well lit at night? Are there police posts or neighbourhood watch signs? Gives you peace of mind when returning home after dark.

    Take this table with you on your next visit to any of the four neighbourhoods. Tick off each row as you confirm it.

    Financial Tips for Moving to a Senior Friendly Neighbourhood

    Moving house later in life can feel daunting, especially with CPF and housing grants to think about. But Singapore has several schemes that make it easier for Merdeka Generation seniors to shift to a more suitable home.

    • Silver Housing Bonus: If you sell your current flat and buy a three room or smaller resale flat, you can get up to $30,000 in CPF top ups. This works well if you are downsizing from a larger flat in, say, Toa Payoh to a 2 room Flexi unit in the same town.
    • Lease Buyback Scheme: You keep living in your flat but sell part of the lease back to HDB for a stream of income. This is popular with seniors who want to stay put but need extra cash.
    • CPF top ups for housing: You can use your https://merdekageneration.sg/cpf-medisave-for-seniors-how-much-you-need-and-how-to-use-it-wisely/ to pay for renovation costs, like installing grab bars and ramps, under the Enhancement for Active Seniors (EASE) programme.

    Before you move, also check if your new neighbourhood has any grants for retrofitting. Many towns now offer free home improvement assessments for seniors over 60.

    "The best senior friendly neighbourhood is one that lets you age in place without sacrificing your social life. Look for an area where you can walk to the market, the clinic, and the community centre within 15 minutes. That keeps you independent longer." — Tan Bee Lian, senior social worker at a community hospital in Bishan.

    Making the Most of Your Merdeka Generation Benefits in These Neighbourhoods

    Living in a senior friendly neighbourhood is only half the picture. You also need to know how to use your Merdeka Generation Package benefits effectively. Each of the four neighbourhoods has specific resources that can help you stretch your dollar.

    • In Bishan, the Bishan Polyclinic has a dedicated MG counter that helps you claim your https://merdekageneration.sg/how-much-can-you-actually-save-on-polyclinic-visits-with-merdeka-generation-subsidies/ for each visit.
    • In Tiong Bahru, the SGH specialist outpatient clinic allows you to combine your MG subsidies with the https://merdekageneration.sg/does-your-specialist-visit-qualify-for-merdeka-generation-subsidies/ for lower bills.
    • Toa Payoh has several dental clinics that accept CHAS and MG subsidies. Check our https://merdekageneration.sg/6-dental-care-subsidies-merdeka-generation-seniors-can-tap-on-in-2026/ for eligibility.
    • Woodlands has a community health post at the bus interchange that offers free blood pressure checks and helps you enroll in the https://merdekageneration.sg/what-to-do-when-your-healthcare-subsidy-claim-gets-rejected/ if you ever face issues.

    If you are an adult child helping your parents, our guide on https://merdekageneration.sg/how-adult-children-can-help-parents-maximise-merdeka-generation-subsidies/ is a good starting point.

    Your Next Step Towards Comfortable Ageing

    Finding the right senior friendly neighbourhood takes some legwork, but it pays off every single day. Start by visiting one of the four estates we covered. Spend a morning walking around. Check if the walking paths are flat. Look for benches. Pop into a CHAS clinic and ask if they accept MG subsidies. Visit the community centre and see what programmes they run.

    If you are still unsure, write down your top three priorities. Is it healthcare access? Affordability of daily necessities? Or having plenty of green spaces? Match your priority against the strengths of each neighbourhood. You might find that Woodlands fits your love for parks, or that Tiong Bahru suits your need for convenience.

    Do not forget to talk to your family about your decision. They can help you with the paperwork for grants like the Silver Housing Bonus or the Lease Buyback Scheme. And always remember that your Merdeka Generation Package is designed to support you in these neighbourhoods, so use it to its full potential.

    Choosing a place to call home is a personal journey. But with the right information and a clear checklist, you can find a neighbourhood where you will feel safe, happy, and connected for many years to come.
  • How to Retrofit Your HDB Flat for Safe and Comfortable Aging in Place

    How to Retrofit Your HDB Flat for Safe and Comfortable Aging in Place

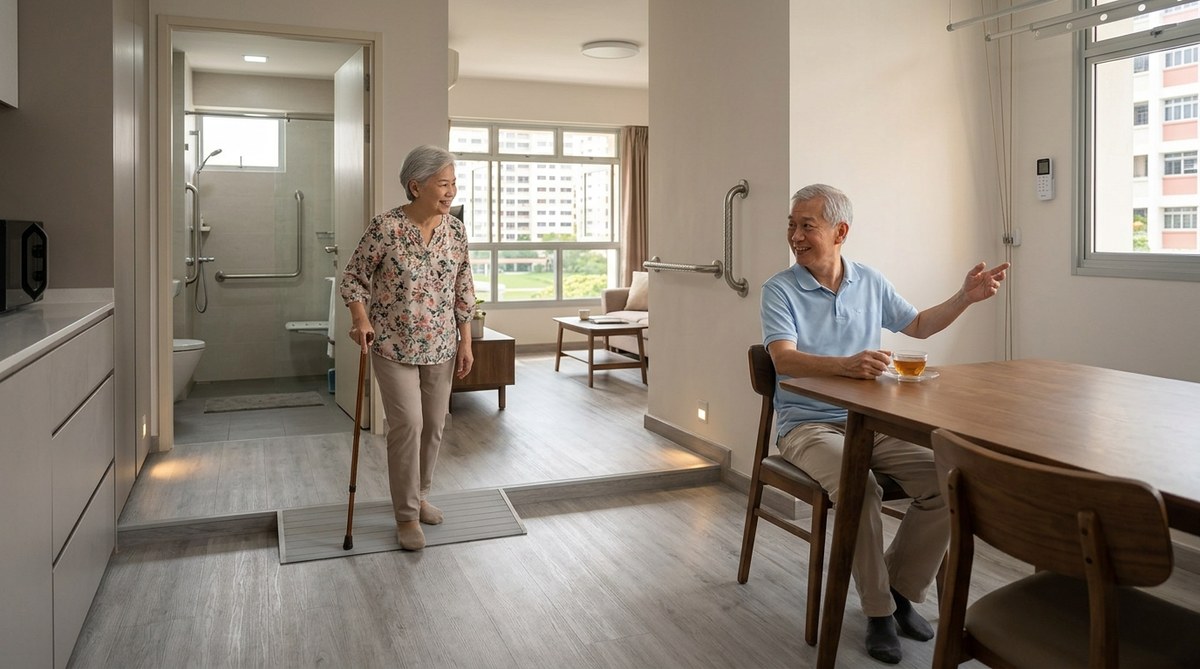
    Your HDB flat has been your home for decades. The children grew up here, you celebrated many CNY dinners in the living room, and the neighbourhood kopitiam knows your regular order. But as you or your parents get older, that same flat can start to feel less safe. The step into the shower feels higher. The corridor to the kitchen seems narrower. The thought of a fall becomes a real worry. The good news is you do not need to move out. With some smart modifications, your existing home can support you safely through the years ahead.

    Key Takeaway

    Retrofitting an HDB flat for aging in place does not have to be expensive or disruptive. Focus on a few high-impact areas: the bathroom, the entrance, and flooring. The Enhancement for Active Seniors (EASE) programme can subsidise up to 95% of costs for eligible households. Plan ahead based on current and future mobility needs, and always engage an HDB-approved contractor to ensure safety and compliance.

    Why Consider an HDB Aging in Place Retrofit

    Aging in place means living in your own home safely, independently, and comfortably, regardless of age or mobility level. For many Singaporean seniors, the Merdeka Generation, moving to a nursing home or a relative’s flat is not appealing. You know your neighbours. You know which lift lobby has the best breeze. Staying put preserves your social connections and your sense of independence.

    Beyond emotional comfort, practical reasons matter. The cost of retrofitting is often far lower than selling and buying a smaller flat or moving into a senior-friendly development. With government support through the your out-of-pocket expenses can be minimal. A retrofit can prevent falls, which are the leading cause of hospitalisation among seniors in Singapore. A safer home means fewer trips to the A&E and more peace of mind for everyone.

    Step 1: Assess Your Current and Future Needs

    Before buying grab bars or removing bathtubs, take stock. Start with a walkthrough of your flat with a critical eye. Better yet, ask a family member or an occupational therapist to help. They spot hazards you might overlook because you are used to them.

    Checklist for a Home Safety Audit

    • Are there any loose rugs or uneven floor tiles that could trip someone?
    • Can you stand and move freely in the bathroom, especially near the toilet and shower?
    • Do doorways allow a walker or wheelchair to pass through comfortably?
    • Is the lighting adequate, especially at night, from bedroom to toilet?
    • Are kitchen counters at a height that avoids excessive bending or reaching?
    • Do you have a step to enter the shower area?

    Use this audit to create a priority list. For example, if the bathroom floor gets slippery when wet, that becomes a high priority. If the kitchen counter height is fine now but may become an issue in five years, you can plan a medium-term fix.

    Step 2: Understand Available Grants and Schemes

    Singapore’s government has several schemes to help seniors retrofit their HDB flats. The most important is the Enhancement for Active Seniors (EASE) programme. HDB offers this subsidy for a fixed set of modifications. Eligible households can receive up to 95% subsidy, depending on income.

    Key Grants at a Glance

    Grant / Scheme What It Covers Subsidy Level Eligibility
    EASE (HDB) Grab bars, slip-resistant flooring, ramps, widening of doorways Up to 95% for lower-income; 87.5% for others Singapore citizen, HDB flat, at least one occupant aged 65+ or 60+ with mobility needs
    Seniors’ Mobility and Enabling Fund (SMF) Assistive devices like walking frames, wheelchairs, commodes Up to 90% subsidy, capped at amounts Singapore citizen, means-tested, referred by healthcare professional
    Ageing-in-Place Programme (AIP) Comprehensive retrofitting beyond EASE (e.g., kitchen, full bathroom remodel) Variable grants depending on flat type and income Must be EASE-eligible and living in selected HDB estates

    “We often tell families to start with the bathroom because that is where most falls happen. Even simple changes like a raised toilet seat and a grab bar can prevent a hip fracture.” – Occupational therapist from a Singapore public hospital

    Do not forget the Merdeka Generation seniors may qualify for additional healthcare subsidies that can cover the cost of consultations or therapy that inform your retrofit plans.

    Step 3: Choose High-Impact Modifications

    You do not need to overhaul the entire flat. Focus on the areas that pose the highest risk. Here is a numbered list of the most effective modifications, ranked by impact on safety.

    1. Install grab bars in the bathroom. Place them near the toilet and inside the shower. Steel or stainless steel grab bars that can support at least 200 kg are ideal. Make sure they are anchored into wall studs or installed with heavy-duty fixings.
    2. Replace slippery flooring. In bathrooms and kitchen, use slip-resistant tiles. For the rest of the flat, avoid high-pile carpets. Flat, non-slip vinyl or laminate is a good choice. Remove any loose rugs.
    3. Widen doorways. Standard HDB doorways can be too narrow for a wheelchair or walker. Widening them to at least 760 mm (about 30 inches) makes a big difference. This can be done during EASE renovations.
    4. Improve lighting. Add night lights along the path from bedroom to toilet. Use motion-sensor lights so you do not have to fumble for a switch. Brighten dark hallways with LED strips.
    5. Create a level entry. If you have a step at the main door or into the bathroom, install a small ramp or reduce the step height. Even a 2 cm difference can be a trip hazard.
    6. Raise toilet seats. A higher toilet seat (about 400–430 mm) reduces the effort to sit down and stand up. Many affordable add-on seats are available.
    7. Add a shower commode chair or fold-down seat. This allows showering while seated, greatly reducing fall risk.

    Step 4: Find a Trusted Contractor

    HDB has a list of approved contractors for EASE works. Stick to them. They understand HDB structural requirements and guarantee workmanship. If you need additional retrofitting beyond EASE (for example, a full kitchen redesign), look for contractors experienced with universal design. Ask for references or photos of past projects.

    What to Ask a Contractor

    • Are you familiar with HDB guidelines for elderly safety modifications?
    • Can you provide a detailed quotation including all materials and labour?
    • Do you help with grant applications or provide the necessary documentation?
    • How long will the work take? What measures do you take to minimise dust and disruption?

    Step 5: Create a Timeline and Budget

    Some retrofitting can happen over a weekend. Other jobs require coordination with neighbours, especially if there is noisy renovation work. Plan around major holidays or family events.

    Sample Budget for a Basic EASE Retrofit

    Modification Estimated Cost before Grant After 87.5% Subsidy (For Homeowner above PCHI threshold)
    Grab bars (set of 3) $400 $50
    Slip-resistant flooring in bathroom & toilet $600 $75
    Ramps for main entrance and bathroom $300 $37.50
    Widening of one doorway $500 $62.50
    Total $1,800 $225

    Numbers are rough estimates and change yearly. Check the https://merdekageneration.sg/scheme-updates-guide/ for current figures.

    Common Mistakes to Avoid

    Even with good intentions, people make errors. Here are pitfalls to watch for, and how to steer clear.

    Mistake Why It Is a Problem Better Approach
    Installing grab bars in wrong location They end up too far to reach or mounted on hollow wallboard Have an occupational therapist mark positions before drilling
    Choosing cheap non-slip mats They can curl up at edges, causing trips Invest in fixed slip-resistant floor tiles or sheets
    Forgetting about lighting Dim corridors remain hazardous even with grab bars Install automatic night lights along the main path
    Overdoing changes too soon Unnecessary expense may reduce resale appeal or aesthetics Prioritise high-risk areas first; leave cosmetic upgrades for later

    Making Your Retrofit Sustainable

    A good retrofit does not just solve today’s problems. It also adapts to future needs. For example, if you install grab bars now, leave space so that a caregiver can assist later. Choose lever handles instead of round doorknobs; they are easier for arthritic hands. Consider a built-in shelf in the shower for toiletries at a reachable height.

    Remember that aging in place is not only about physical safety. It involves social and financial well-being too. The https://merdekageneration.sg/top-senior-friendly-housing-options-in-singapore-for-comfortable-aging/ article explores other housing choices if retrofitting is not enough.

    Final Steps: Putting the Plan into Action

    You now have a clear roadmap. Let us summarise the steps:

    • Perform a home safety audit with a family member or professional.
    • Check your eligibility for EASE and other subsidies.
    • Decide on two or three high-impact modifications to start.
    • Book an approved contractor through HDB.
    • Arrange the work timeline to minimise disruption.
    • Test the changes and adjust as needed.

    A single fall in the bathroom can change your life. A simple grab bar and a night light can prevent that fall. Do not wait until an accident happens. Start planning your retrofit this year.

    If you are also managing other aspects of retirement finances, read our guide on https://merdekageneration.sg/should-you-downsize-your-hdb-flat-for-extra-retirement-cash/ for a broader view of housing choices. And if you need healthcare subsidy support, the https://merdekageneration.sg/how-much-can-you-actually-save-on-polyclinic-visits-with-merdeka-generation-subsidies/ article can help you save more.

    Your home should be your sanctuary, not a hazard. With the right modifications, you can enjoy many more years of comfort, independence, and safety in the flat you love.

  • Top Senior-Friendly Housing Options in Singapore for Comfortable Aging

    Top Senior-Friendly Housing Options in Singapore for Comfortable Aging

    Thinking about where to settle as you grow older in Singapore? Finding the right housing can make aging in place more comfortable, accessible, and filled with community. With a range of options tailored for seniors, Singapore offers solutions that cater to independence, safety, and social connection. Whether you’re considering staying in your current home, moving to a senior-friendly condominium, or exploring government-supported schemes, understanding your choices can empower you to make confident decisions for your retirement years.

    Key Takeaway

    Singapore offers diverse senior-friendly housing options designed for comfort, safety, and community. Combining government schemes, accessible layouts, and active ageing programs helps seniors stay independent and engaged in their golden years.

    Understanding What Makes Housing Senior-Friendly

    Senior-friendly housing in Singapore is more than just accessible layouts. It includes safety features like grab bars, barrier-free designs, and emergency call systems. Many options also foster social interaction, community support, and proximity to healthcare services. The goal is to enable seniors to age gracefully at home or in environments that promote well-being and independence.

    Popular Housing Options for Older Adults in Singapore

    Singapore’s housing landscape caters to seniors in various ways. Here are some of the most common and effective options:

    1. HDB Flats with Senior-Friendly Features

    Many Housing Development Board flats are equipped or can be upgraded with features such as ramps, grab bars, and wider doorways. The government also offers schemes like the Silver Housing Bonus that incentivize seniors to downsize or move into more manageable flats. Some flats are located near amenities and transport links, making daily life more convenient.

    2. Senior Care Apartments and Community Care Facilities

    These are specially designed housing options offering assisted living services. Facilities such as community care apartments blend independence with support, including emergency response systems, health monitoring, and social activities. These residences are ideal for seniors who require some assistance but wish to maintain their privacy and autonomy.

    3. Private Condominiums with Senior-Friendly Amenities

    Many private condos in Singapore now incorporate senior-oriented features. Think wheelchair-accessible pathways, senior activity rooms, and health clinics within or nearby the premises. These properties often attract active seniors looking for a vibrant social scene and amenities like swimming pools, gyms, and gardens.

    4. Executive Condominiums and Assisted Living Residences

    These developments are increasingly catering to the ageing population by integrating age-friendly designs and healthcare services. Some projects even include dedicated nursing care facilities or partnerships with medical providers, making them suitable for seniors planning for future healthcare needs.

    5. Sheltered Housing and Assisted Living Schemes

    The government and private providers offer sheltered housing options that combine affordable rent with accessible features. These are often located within mature estates with easy access to clinics, shops, and transport. They are especially useful for seniors seeking a safe environment with community support.

    How to Choose the Right Senior Housing in Singapore

    Selecting the best housing option involves careful planning. Here’s a simple process to guide your decision:

    1. Assess your needs
      Evaluate your mobility, health status, social preferences, and future care plans. Do you need assistance with daily activities or prefer to stay independent?

    2. Explore available schemes and benefits
      Understand government schemes like the Silver Housing Bonus, Lease Buyback Scheme, and the Merdeka Generation Package. These can alleviate costs or provide additional support.

    3. Visit and compare properties
      Schedule visits to various housing options. Check accessibility features, community environment, proximity to healthcare, and transport links.

    4. Plan your finances
      Review your savings, CPF funds, and potential subsidies. Consider engaging a financial planner to align your housing choices with your retirement income.

    5. Consult with family and professionals
      Discuss options with your loved ones and seek advice from housing officers or eldercare specialists to ensure your choice fits your long-term needs.

    Practical Tips for Aging Comfortably in Singapore

    • Leverage government schemes: The Merdeka Generation Package offers subsidies and healthcare benefits that can ease your living costs. Learn about your eligibility to maximize these benefits.

    • Prioritize safety features: When choosing a home, prioritize accessible layouts, non-slip flooring, good lighting, and emergency response systems.

    • Engage in active ageing programs: Many community centres offer fitness classes, social activities, and health screenings that complement your housing environment.

    • Plan for healthcare access: Proximity to clinics and hospitals simplifies managing health needs. Consider housing options near polyclinics or specialist centres.

    • Stay socially connected: Living in a vibrant community enhances mental health and reduces loneliness. Look for residences that promote social interaction and community events.

    Simplifying Government Schemes for Senior Housing

    Singapore’s government has introduced several initiatives to support seniors in housing:

    Scheme Purpose Key Benefits Common Mistakes Tips
    Silver Housing Bonus Encourage downsizing or moving into more manageable flats Cash incentives and grants Overlooking eligibility criteria Check scheme details early, plan ahead
    Lease Buyback Scheme Monetize your flat while staying in the same home Supplement retirement income Underestimating future needs Consult with HDB officers before opting
    Merdeka Generation Package Healthcare subsidies and benefits Reduced healthcare costs Not applying in time Verify eligibility and apply early
    HDB Priority Schemes Priority for seniors in flat applications Faster approval Missing deadlines Stay updated on application windows

    Always review scheme requirements carefully. Consulting with housing or eldercare experts can help you avoid common pitfalls and make the most of available benefits.

    Building Confidence with Retirement Planning

    Planning your housing is part of a broader retirement strategy. Here are actionable tips:

    • Save regularly and consider supplementing CPF with voluntary top-ups.
    • Use government grants and subsidies to reduce costs.
    • Maintain health through active lifestyles and regular checkups.
    • Consider insurance plans tailored for seniors.
    • Keep emergency contacts and health information accessible.

    Connecting with Resources and Support

    Singapore offers various resources to assist seniors and their families:

    • Eldercare services: Community centres and voluntary welfare organisations provide support, activities, and advice.
    • Financial advice: Retirement planning agencies can help optimise your savings and housing options.
    • Healthcare support: CHAS (Community Health Assist Scheme) and the Merdeka Generation Package help reduce medical expenses.
    • Housing consultations: HDB and private developers offer guidance on suitable flats and schemes.

    Making Your Retirement Home a Reality

    Choosing the right housing for aging in place involves understanding your needs, exploring options, and leveraging available support. By combining accessible layouts, community involvement, and government schemes, you can create a living environment that promotes independence and happiness. Remember to involve your loved ones and seek expert advice to ensure your decision aligns with your long-term wellbeing.

    Start Your Journey to a Comfortable Retirement Home Today

    Taking the time to plan and explore senior-friendly housing options in Singapore can lead to a more fulfilling and independent retirement. With the right environment, community, and support schemes, your golden years can truly be enjoyed to the fullest. Begin your research now, speak with professionals, and involve your family to make confident choices for your future.

  • 7 Affordable Active Ageing Programmes That Accept PAssion Card Discounts

    7 Affordable Active Ageing Programmes That Accept PAssion Card Discounts

    Retirement doesn’t mean sitting at home watching television all day. Many Singaporean seniors want to stay active, learn new skills, and enjoy life without breaking the bank. The PAssion Card offers a range of discounts that make this possible, but many seniors don’t know what’s available or how to access these benefits.

    Key Takeaway

    PAssion Card members aged 55 and above can access transport concessions, activity programme discounts, dining offers, and retail savings across Singapore. The PAssion Silver Concession Card provides additional public transport subsidies. Eligibility is straightforward, and activation takes just a few steps. This guide covers all available passion card senior discounts, how to apply, and practical tips to maximise your savings throughout retirement.

    Understanding the PAssion Card for Seniors

    The PAssion Card is a membership programme run by the People’s Association. It gives Singaporeans access to community clubs, sports facilities, and exclusive merchant discounts.

    Seniors get extra perks.

    Anyone aged 55 and above qualifies for senior benefits automatically once they sign up. The card costs $12 for a two-year membership. That’s just $6 per year for access to hundreds of discounts.

    The card works at over 100 community clubs nationwide. You can book facilities, sign up for classes, and enjoy subsidised rates on activities ranging from line dancing to digital literacy workshops.

    Many seniors confuse the regular PAssion Card with the PAssion Silver Concession Card (PASC). They’re different cards with different purposes. The regular PAssion Card unlocks discounts and activity access. The PASC is specifically for public transport concessions and requires a separate application.

    Who Qualifies for PAssion Card Senior Benefits

    Any Singaporean or Permanent Resident aged 55 and above can apply for the PAssion Card and enjoy senior pricing.

    There’s no income ceiling.

    There’s no medical assessment.

    You don’t need to be part of the Merdeka Generation or Pioneer Generation to qualify, although those groups do get additional healthcare subsidies through separate schemes. If you’re unsure about your eligibility for those programmes, you can check if you qualify for the Merdeka Generation package separately.

    The card is valid for two years from the date of issue. After that, you’ll need to renew it to continue enjoying the benefits.

    How to Apply for Your PAssion Card

    Getting your PAssion Card is straightforward. You have three options.

    Option 1: Apply Online

    1. Visit the OnePA website at onepa.gov.sg.
    2. Click on “Register” if you’re a first-time user.
    3. Fill in your personal details including NRIC, contact information, and address.
    4. Upload a recent passport-sized photo.
    5. Pay the $12 membership fee using credit card, debit card, or PayNow.
    6. Wait for your card to arrive by mail within 7 to 10 working days.

    Option 2: Apply at Any Community Club

    1. Bring your NRIC and a passport-sized photo.
    2. Head to the membership counter at your nearest community club.
    3. Fill out the application form with staff assistance if needed.
    4. Pay the $12 fee in cash or by NETS.
    5. Collect your card on the spot or have it mailed to you.

    Option 3: Apply Through the OnePA Mobile App

    1. Download the OnePA app from the App Store or Google Play.
    2. Register for an account using your SingPass.
    3. Complete the membership application form.
    4. Upload your photo and make payment.
    5. Receive your card by mail.

    Most seniors find the in-person option at the community club easiest because staff can answer questions immediately.

    PAssion Silver Concession Card for Transport Savings

    The PAssion Silver Concession Card is a separate card that gives you discounted public transport fares.

    If you’re 60 and above, you can save up to 50% on bus and train rides during off-peak hours. Peak hours (weekdays before 7.45am) offer lower discounts, but you still save.

    To apply for the PASC:

    1. You must already have a regular PAssion Card.
    2. You must be 60 years old or above.
    3. Apply online at transitlink.com.sg or visit any TransitLink Ticket Office.
    4. Pay the $5 card fee.
    5. Collect your card or have it mailed.

    The PASC is valid for five years. After that, you’ll need to replace it, although the concession continues automatically as long as you remain eligible.

    Some seniors carry both cards. The regular PAssion Card for activities and merchant discounts. The PASC for transport. They serve different purposes and cannot be combined into one card.

    Top Passion Card Senior Discounts You Should Know

    Here are the most valuable discounts available with your PAssion Card.

    Community Club Activities and Courses

    Community clubs offer hundreds of courses each term. Cooking classes, yoga, swimming lessons, art workshops, and language courses all come with member pricing.

    Seniors enjoy additional discounts on top of member rates. A typical course that costs $80 for regular members might cost $50 for seniors.

    Check the PA Course Booklet published every quarter or browse the OnePA app to see what’s available near you.

    Sports Facilities Booking

    Need a badminton court? Want to swim laps at the pool? PAssion Card members get discounted rates when booking sports facilities at community clubs.

    Senior rates are even lower. For example, a badminton court that costs $6 per hour for regular members might cost $4 for seniors during off-peak hours.

    Dining Discounts at Partner Restaurants

    Over 200 restaurants, cafes, and food courts across Singapore accept the PAssion Card for discounts ranging from 10% to 30%.

    Popular chains like PastaMania, Swensen’s, and selected hawker centres participate in the programme. Always ask before ordering whether senior discounts apply on top of regular PAssion Card offers.

    Some merchants cap the discount at certain times or days. Weekend promotions might differ from weekday deals.

    Retail and Grocery Savings

    Selected NTUC FairPrice outlets offer additional discounts for PAssion Card holders on specific days.

    Guardian and Watsons pharmacies sometimes run promotions for cardholders. Check in-store signage or ask the cashier before paying.

    Other participating merchants include optical shops, bookstores, and home improvement retailers. The full list changes quarterly, so keep an eye on the OnePA app for updates.

    Health Screening and Wellness Services

    Some polyclinics and private clinics offer discounted health screening packages for PAssion Card members.

    Dental clinics, traditional Chinese medicine practitioners, and physiotherapy centres also participate.

    These aren’t automatic. You’ll need to show your card and ask if senior rates apply.

    Common Mistakes Seniors Make with PAssion Card Discounts

    Many seniors miss out on savings because they don’t know how to use their card properly. If you want to avoid other common errors when claiming government benefits, read about mistakes Merdeka Generation seniors make when claiming benefits.

    Mistake Why It Happens How to Avoid It
    Not carrying the card Forget to bring it when going out Keep it in your wallet next to your NRIC
    Assuming all merchants accept it Not all shops participate Ask before ordering or check the OnePA app
    Missing renewal deadlines Card expires after two years Set a phone reminder six months before expiry
    Not checking for updated offers Promotions change quarterly Browse the app or visit your community club monthly
    Using expired cards Unaware the card has lapsed Check the expiry date printed on the front

    One senior shared that she missed out on $200 in savings over six months simply because she didn’t realise her card had expired. She kept showing it at restaurants, and staff politely told her the discount didn’t apply, but she thought it was because the promotion had ended.

    Always check your card’s expiry date before heading out.

    How to Maximise Your PAssion Card Savings

    Getting the card is step one. Using it strategically is step two.

    Plan Your Activities Around Discounts

    Community clubs publish their course schedules months in advance. Browse the offerings and sign up early for the best selection.

    Popular classes like Zumba, smartphone photography, and baking fill up fast. Seniors who register during the early bird period sometimes get an extra 5% off.

    Combine Discounts Where Possible

    Some merchants allow you to stack PAssion Card discounts with other promotions. For example, a restaurant might offer 15% off for PAssion Card holders plus an additional 10% off for seniors during weekday lunches.

    Always ask. The worst they can say is no.

    Use the OnePA App to Track Offers

    The app sends notifications when new promotions launch. You can also search for participating merchants near your current location.

    The app includes a digital version of your card, but most merchants still prefer to see the physical card. Carry both just in case.

    Share Tips with Friends

    Many seniors find out about great discounts through word of mouth. If you discover a fantastic deal, tell your friends at the community club or during your morning walk.

    Someone else might return the favour by sharing a discount you didn’t know about.

    “I saved over $600 last year just by using my PAssion Card at the community club gym, attending subsidised tai chi classes, and eating at participating coffee shops twice a week. It’s not just about the money. I feel more connected to my neighbourhood and I’ve made new friends along the way.” — Mrs Tan, 67, Ang Mo Kio resident

    What to Do If Your Card Is Lost or Damaged

    Losing your PAssion Card is frustrating, but replacement is simple.

    1. Report the loss through the OnePA app or by calling the PA hotline at 6225 5322.
    2. Pay the $10 replacement fee.
    3. Collect your new card at any community club or have it mailed.

    Your membership period remains the same. If you had six months left on your original card, the replacement will reflect that.

    If your card is damaged but still readable, you might be able to get a free replacement at your community club. Bring the damaged card and your NRIC.

    For Merdeka Generation members who also have an MG card, losing that card requires a different process. You can find out what happens if you lost your Merdeka Generation card and how to replace it.

    Passion Card vs Other Senior Discount Programmes

    Singapore offers several discount schemes for seniors. Understanding the differences helps you choose the right one for your needs.

    The PAssion Card focuses on lifestyle, activities, and community engagement. It’s ideal for active seniors who want to stay social and try new hobbies.

    The CHAS card provides subsidised healthcare at participating clinics. Merdeka Generation seniors get additional subsidies on top of regular CHAS benefits. Learn more about CHAS card benefits for Merdeka Generation seniors.

    The Pioneer Generation and Merdeka Generation packages focus on healthcare subsidies, including outpatient care, medication, and MediShield Life premiums.

    You can hold multiple cards simultaneously. Many seniors carry a PAssion Card, a CHAS card, and their MG or PG card. Each serves a different purpose.

    Budgeting for Retirement with PAssion Card Savings

    Small savings add up over time.

    If you save $50 per month using your PAssion Card on activities, dining, and transport, that’s $600 per year. Over ten years, that’s $6,000 back in your pocket.

    For seniors on fixed incomes, every dollar counts. Creating a monthly budget that works on CPF LIFE and pension income becomes easier when you factor in these discounts.

    Track your spending for three months. Note every time you use your PAssion Card. Calculate the total savings. You might be surprised how much you’ve saved without even trying.

    Some seniors use those savings to treat themselves to a nice meal once a month or to buy birthday gifts for grandchildren. Others put the money aside for medical expenses or home repairs.

    The choice is yours, but knowing your savings gives you more control over your retirement finances.

    Staying Active and Connected Through Your PAssion Card

    Beyond the financial benefits, the PAssion Card opens doors to community engagement.

    Joining a line dancing class at your community club introduces you to neighbours you might never have met otherwise. Attending a smartphone workshop helps you stay connected with family members overseas through video calls.

    Loneliness is a real issue for many retirees. Having regular activities to attend gives structure to your week and provides social interaction.

    One senior mentioned that after his wife passed away, attending the Monday morning tai chi class at his community club became the highlight of his week. He made friends, stayed physically active, and had something to look forward to.

    The PAssion Card isn’t just about discounts. It’s about staying engaged with life.

    Making the Most of Your Golden Years

    Retirement should be a time of enjoyment, not endless worry about money. The PAssion Card helps stretch your budget while keeping you active and connected.

    Apply for your card today if you haven’t already. Start small by booking one class or trying one discounted meal. See how it feels.

    As you get more comfortable using the card, you’ll discover more ways to save and more opportunities to enjoy your retirement years. The community clubs are filled with friendly faces and helpful staff ready to guide you.

    Your golden years can be golden in more ways than one.

  • Is Senior Activity Centre or Day Rehabilitation Better for Your Needs?

    Is Senior Activity Centre or Day Rehabilitation Better for Your Needs?

    Your mum’s doctor mentioned she needs more structured daytime support after her stroke. Your neighbour suggested a senior activity centre. The hospital discharge planner keeps talking about day rehabilitation. Now you’re sitting at the kitchen table, trying to figure out which one actually helps her regain strength and independence.

    These two options sound similar, but they serve completely different purposes. Choosing the wrong one can mean wasted time, money, and missed opportunities for recovery.

    Key Takeaway

    Senior activity centres focus on social engagement and wellness for independent seniors, while day rehabilitation centres provide medical therapy for those recovering from illness, injury, or surgery. Day rehab requires doctor referral and offers physiotherapy, occupational therapy, and nursing care. Activity centres are community-based, self-referred, and designed for healthy ageing. Your parent’s medical condition, functional ability, and recovery goals determine which option suits them best.

    What senior activity centres actually do

    Senior activity centres are community hubs for older adults who can manage their daily activities independently.

    Think of them as social clubs with health benefits.

    Your parent attends programs during the day and returns home in the evening. No medical treatment happens here. Instead, the focus is on staying active, making friends, and preventing decline.

    Most centres run from 9am to 5pm on weekdays. Some open on Saturdays too.

    Typical activities include exercise classes, art workshops, cooking sessions, and educational talks. Many organise outings to gardens, museums, or hawker centres.

    The goal is simple: keep seniors engaged, active, and connected to their community.

    Staff members are trained in senior care, but they’re not medical professionals. You won’t find physiotherapists or nurses running therapy sessions.

    Seniors attend voluntarily. No doctor’s referral needed.

    Costs vary by centre, but most charge between $50 to $150 monthly. Some offer subsidies based on household income.

    “Senior activity centres work best for parents who are physically well but might be lonely or inactive at home. They need stimulation and friendship, not medical intervention.”

    How day rehabilitation centres operate differently

    Day rehabilitation centres provide medical treatment and therapy.

    Your parent needs a doctor’s referral to attend. The discharge planner or family doctor makes this referral based on specific medical needs.

    These centres treat seniors recovering from strokes, fractures, joint replacements, or chronic conditions affecting mobility and daily function.

    A typical day starts with health checks. Nurses monitor blood pressure, blood sugar, and medication compliance.

    Then comes structured therapy.

    Physiotherapists work on strength, balance, and walking ability. Occupational therapists help your parent relearn daily tasks like bathing, dressing, and cooking safely.

    Some centres offer speech therapy for those with swallowing difficulties or communication problems after stroke.

    Sessions run three to five days weekly, usually for two to three months. Duration depends on your parent’s progress and therapy goals.

    Transport is often provided. Vans with wheelchair access pick up participants from home.

    Meals are included, with special diets available for diabetic or low-salt requirements.

    Medical oversight is constant. Doctors review progress regularly and adjust treatment plans.

    Costs are higher than activity centres, but government subsidies significantly reduce out-of-pocket expenses. CHAS card benefits explained: what Merdeka Generation seniors need to know can help offset some therapy costs.

    Key differences at a glance

    Feature Senior Activity Centre Day Rehabilitation Centre
    Purpose Social engagement and wellness Medical recovery and therapy
    Referral needed No Yes, from doctor
    Staff Activity coordinators, volunteers Therapists, nurses, doctors
    Services Exercise, arts, outings Physiotherapy, occupational therapy, nursing
    Suitable for Independent seniors Seniors recovering from illness or injury
    Duration Ongoing, no time limit 2-3 months typically
    Cost range $50-$150/month Higher, but subsidised
    Transport Usually self-arranged Often provided

    How to decide which option fits your parent’s needs

    Start by assessing their current functional ability.

    Can your parent bathe, dress, and move around the house safely without help? If yes, and they’re just lonely or inactive, an activity centre makes sense.

    If your parent struggles with daily tasks after a recent health event, day rehabilitation is the better choice.

    Ask yourself these questions:

    1. Has your parent been discharged from hospital recently?
    2. Did the doctor mention needing physiotherapy or occupational therapy?
    3. Does your parent have difficulty walking, climbing stairs, or getting in and out of chairs?
    4. Are they at risk of falling due to weakness or balance problems?
    5. Do they need help relearning how to cook, bathe, or manage medications safely?

    Three or more “yes” answers point towards day rehabilitation.

    Talk to your parent’s doctor. They can assess whether medical therapy would help and make the appropriate referral.

    Don’t assume age alone determines the right choice. A 75-year-old recovering from hip surgery needs day rehab. An 80-year-old who’s fit but bored at home benefits more from an activity centre.

    What happens during a typical day at each centre

    At a senior activity centre, your parent might start the morning with tai chi or line dancing. Mid-morning brings a craft session or language class.

    Lunch is communal, often catered or cooked together.

    Afternoons feature games like mahjong, card games, or board games. Some days include health talks by visiting professionals.

    The atmosphere is relaxed. Attendance is flexible. If your parent wants to skip a day for a family outing, that’s fine.

    Day rehabilitation follows a stricter schedule.

    Your parent arrives by 9am. Nurses check vital signs and review any concerns from the previous day.

    Therapy sessions run 45 minutes each, with breaks between. A typical day includes two physiotherapy sessions and one occupational therapy session.

    Lunch comes with medication supervision if needed.

    Afternoon sessions might focus on group activities that reinforce therapy goals, like cooking classes that practice fine motor skills or balance exercises disguised as games.

    Progress is documented daily. Therapists set weekly goals and adjust exercises based on improvement.

    Your parent receives a detailed report at discharge, with recommendations for continuing exercises at home.

    Common misconceptions that lead families astray

    Many families think day rehabilitation is just expensive babysitting.

    It’s not.

    The medical team works towards specific, measurable goals. Your parent should regain function, not just pass time.

    Another myth: senior activity centres are only for very old or frail people.

    Actually, many participants are in their 60s and 70s, active and independent. They attend because they enjoy the company and activities.

    Some caregivers believe their parent is “too sick” for an activity centre but “not sick enough” for day rehab.

    This gap doesn’t really exist. If your parent can’t manage daily activities independently, they need medical assessment. If they can, but lack social connection, an activity centre helps.

    Don’t confuse day rehabilitation with nursing homes or long-term care. Day rehab is temporary, goal-focused, and designed to return your parent to maximum independence.

    How subsidies and financial assistance work

    Day rehabilitation centres accept Medisave for approved therapy services.

    The managing healthcare costs in retirement: beyond MediSave and CHAS subsidies guide explains how to maximise these benefits.

    ElderShield or CareShield Life may cover some costs if your parent meets disability criteria.

    Community Health Assist Scheme (CHAS) subsidies apply to certain therapy services at accredited centres.

    Merdeka Generation seniors get additional subsidies. Check eligibility through how to check if you qualify for the Merdeka Generation Package in 2024.

    Senior activity centres often have their own subsidy schemes. Approach the centre directly to ask about financial assistance based on household income.

    Some centres waive fees entirely for lower-income seniors.

    Don’t let cost alone drive your decision. The wrong choice costs more in the long run through slower recovery or preventable decline.

    Steps to enrol your parent in the right programme

    For senior activity centres:

    1. Visit centres near your parent’s home to observe activities and meet staff
    2. Check operating hours and whether transport assistance is available
    3. Ask about trial sessions so your parent can experience the programme before committing
    4. Complete registration forms and provide emergency contact information
    5. Arrange payment and clarify subsidy eligibility

    For day rehabilitation centres:

    1. Get a referral letter from your parent’s hospital doctor or family physician
    2. Contact the day rehab centre to check availability and waiting times
    3. Attend an assessment appointment where therapists evaluate your parent’s needs
    4. Receive a customised therapy plan with specific goals and expected duration
    5. Arrange transport if the centre doesn’t provide it
    6. Submit subsidy applications and insurance claims

    The assessment for day rehab is thorough. Therapists test strength, balance, mobility, and ability to perform daily tasks. This takes one to two hours.

    Results determine whether day rehab is appropriate or if other options like home therapy suit better.

    What to do when your parent needs both

    Sometimes seniors benefit from transitioning between services.

    Your parent might start with day rehabilitation after a stroke, attend for three months, regain basic function, then move to a senior activity centre to maintain fitness and social connections.

    This progression is common and healthy.

    The day rehab team can recommend suitable activity centres when discharge approaches.

    Some seniors attend both simultaneously. They might go to day rehab three days weekly for therapy and an activity centre two days for social engagement.

    Discuss this with the therapy team. They’ll advise whether your parent has the stamina for both or should focus on one at a time.

    Red flags that mean you’ve chosen the wrong option

    Your parent attends a senior activity centre but keeps falling or struggling with daily tasks. This signals they need medical intervention, not just social activities.

    Request a doctor’s assessment for possible day rehab referral.

    Conversely, your parent attends day rehabilitation but has already regained full function and finds the medical focus unnecessary. They might be ready to transition to an activity centre.

    Watch for signs of boredom or frustration with overly simple exercises.

    If your parent refuses to attend either option, dig deeper. Are they embarrassed? Uncomfortable with the group? Physically struggling more than they admit?

    Sometimes the issue isn’t the programme type but the specific centre’s culture or location.

    Try a different centre before giving up on the concept entirely.

    Making the transition back home successful

    Day rehabilitation should prepare your parent for independence, not create dependency.

    Before discharge, therapists conduct home visits. They assess safety, recommend modifications like grab bars or shower seats, and teach you how to support continued exercises.

    Take this seriously. What to do when your healthcare subsidy claim gets rejected becomes relevant if you need to appeal for extended therapy coverage.

    Ask for written exercise instructions. Videos are even better.

    Schedule a follow-up with the family doctor two weeks after day rehab ends. This catches any decline early.

    For seniors leaving activity centres, the transition is easier since they’ve been managing at home all along. Encourage them to maintain friendships formed at the centre through phone calls or home visits.

    Some centres offer alumni activities or monthly gatherings for past participants.

    When neither option is quite right

    Some seniors need more intensive support than day rehabilitation provides but aren’t ready for residential care.

    Home-based therapy might work better. Therapists visit your parent’s home for one-on-one sessions in their actual living environment.

    Others are too medically fragile for day rehab’s group setting. They need individual nursing care at home.

    A few seniors resist all structured programmes. For them, hiring a companion or helper who encourages activity and provides company might be the practical solution.

    Don’t force a square peg into a round hole. If both options feel wrong after genuine attempts, reassess your parent’s actual needs with their doctor.

    Choosing what actually helps your parent thrive

    The senior activity centre vs day rehabilitation decision comes down to one question: does your parent need medical treatment or social engagement?

    Medical needs always take priority. If your parent can benefit from therapy, start there. Social activities can come later.

    But don’t underestimate the power of community and purpose. A lonely, inactive senior declines faster than you’d expect. Activity centres prevent this decline.

    Visit both types of centres. See the difference in atmosphere, staff expertise, and participant needs. The right choice will become obvious when you observe actual programmes in action.

    Your parent deserves support that matches their current abilities and helps them move forward, whether that’s regaining lost function or maintaining health and happiness. Choose based on where they are now, not where you wish they were or fear they’ll be.

  • Should You Lease Back Your Flat Under the Lease Buyback Scheme?

    Should You Lease Back Your Flat Under the Lease Buyback Scheme?

    Your HDB flat is probably your biggest asset. But what good is all that locked-up value when you need cash for daily expenses, medical bills, or simply a more comfortable retirement? The HDB lease buyback scheme offers a way to tap into your home equity without moving out. It’s designed specifically for elderly flat owners who want to age in place while boosting their monthly income.

    Key Takeaway

    The HDB lease buyback scheme lets eligible seniors sell part of their flat lease back to HDB for cash while continuing to live there. You’ll receive a lump sum and monthly CPF LIFE payouts, but you must meet age, flat type, and income criteria. This option suits those needing retirement income without relocating, though it permanently reduces your property’s remaining lease and resale value.

    What the HDB lease buyback scheme actually does

    Think of this scheme as selling a portion of your flat’s lease back to the government.

    You don’t sell the whole flat. You sell the tail end of the lease.

    HDB buys back part of your lease, leaving you with a shorter lease of 30 to 35 years. That’s still plenty of time for most seniors to live comfortably in their own home.

    In return, you get cash. Part goes into your CPF Retirement Account to generate monthly payouts. The rest can be withdrawn as cash if you already meet your CPF minimum sum.

    You keep living in the same flat. Nothing changes day to day. You’re still the owner, just with a shorter lease.

    The scheme targets seniors in smaller flats who may not have enough retirement savings. It’s not for everyone, but for the right household, it can mean the difference between scraping by and living with dignity.

    Who can apply for the lease buyback scheme

    Not every flat owner qualifies. HDB has specific criteria.

    Flat type requirements:

    • You must own a 4-room or smaller flat
    • 5-room and executive flats are not eligible
    • The flat must be fully paid up or have minimal outstanding loan

    Age and household criteria:

    • At least one owner must be 65 years or older
    • All owners must be Singapore citizens
    • You must have owned the flat for at least five years

    Income and property limits:

    • Your average monthly household income cannot exceed $14,000
    • You cannot own any other property locally or overseas
    • If you previously owned another property, you must have disposed of it at least 30 months before applying

    If you’re part of the Merdeka Generation, you may find this scheme particularly useful alongside your existing healthcare subsidies and benefits.

    The lease buyback scheme isn’t about giving up your home. It’s about making your home work harder for you in retirement. You’ve paid off your flat. Now let it pay you back.

    How the scheme works step by step

    Here’s what happens when you apply:

    1. Submit your application through HDB’s online portal or at an HDB branch. You’ll need documents proving age, income, and flat ownership.

    2. HDB assesses your eligibility and calculates how much they’ll pay for the lease buyback. This depends on your flat’s market value and remaining lease.

    3. Choose your retained lease between 30 and 35 years. A shorter retained lease means more cash now, but less property value later.

    4. Receive your payout in two parts: CPF Retirement Account top-up first, then any remaining cash balance if you’ve met your CPF minimum sum requirements.

    5. Start receiving monthly payouts from your enhanced CPF LIFE account. The amount depends on how much was topped up and your chosen CPF LIFE plan.

    The entire process typically takes three to four months from application to payout.

    Breaking down the money you’ll receive

    Let’s use real numbers to make this concrete.

    Say you own a 3-room flat valued at $300,000 with 60 years of lease remaining. You choose to retain 30 years of lease.

    HDB might buy back 30 years’ worth of lease for approximately $150,000 (this varies based on location and market conditions).

    From that $150,000:

    • First, HDB tops up your CPF Retirement Account to the current Full Retirement Sum (about $198,800 as of 2024)
    • If the buyback proceeds don’t cover the full amount, you get what’s available
    • Any amount beyond the Full Retirement Sum goes to you as cash

    This CPF top-up immediately increases your monthly CPF LIFE payouts. The exact increase depends on your age and chosen plan.

    For example, topping up $100,000 at age 65 could boost your monthly payout by $700 to $800 for life.

    Comparing your options side by side

    Option Lease buyback scheme Downsizing Staying put
    Keep your home Yes, with shorter lease No, must move Yes, full lease
    Upfront cash Moderate High None
    Monthly income boost Yes, through CPF LIFE Yes, if you invest proceeds Only existing CPF LIFE
    Moving hassle None Significant None
    Future resale value Lower due to shorter lease N/A Maintains current trajectory
    Suitable for Those wanting stability Those willing to relocate Those with adequate savings

    The lease buyback scheme sits between doing nothing and making a major life change. It offers a middle path.

    Common concerns and what actually happens

    “What if I outlive the 30-year lease?”

    You won’t be kicked out. HDB allows you to continue living in the flat even after the lease expires. You won’t own it anymore, but you won’t be homeless either.

    “Can my children inherit the flat?”

    Yes, but only the remaining lease. If you’ve retained 30 years and pass away after 10 years, your beneficiaries inherit a flat with 20 years left. The shorter lease affects resale value significantly.

    “What if I change my mind?”

    Once the transaction completes, you cannot reverse it. This is permanent. That’s why HDB requires all owners to attend a counselling session before approving the application.

    “Will this affect my other benefits?”

    Generally no. Your Merdeka Generation healthcare subsidies and MediShield Life coverage continue as before. The scheme may affect means-tested benefits if the cash payout is large, but CPF top-ups don’t count as assessable income.

    When this scheme makes sense for you

    The lease buyback scheme works best if you:

    • Need more monthly income but want to stay in your familiar neighbourhood
    • Have limited CPF savings and won’t hit the Full Retirement Sum otherwise
    • Don’t plan to leave property inheritance as a priority
    • Feel comfortable with a shorter lease duration
    • Prefer stability over the upheaval of moving

    It’s less suitable if you:

    • Already have adequate retirement income
    • Want to maximise inheritance for your children
    • Might want to sell and upgrade in the future
    • Are considering moving overseas for retirement

    Many seniors also consider downsizing to a smaller flat as an alternative. Both options unlock home equity, but downsizing usually provides more cash upfront while requiring you to relocate.

    Alternatives worth considering

    Before committing to the lease buyback scheme, look at these other options:

    Renting out a room

    If you have spare space, renting out a bedroom provides monthly income without touching your lease. The income is tax-free up to certain limits.

    CPF top-ups from family

    Your children can top up your CPF Retirement Account directly. They get tax relief, and you get higher monthly payouts. No need to touch your property.

    Silver Housing Bonus

    If you’re willing to downsize to a 3-room or smaller flat, this scheme gives you a cash bonus of up to $30,000 on top of your sale proceeds.

    Part-time work

    Safe side hustles and part-time work can supplement your retirement income without any property transactions.

    What to do before you apply

    Don’t rush into this decision. Take these steps first:

    • Calculate your actual monthly needs. Use a realistic budget that accounts for healthcare, utilities, food, and occasional treats. Creating a monthly budget helps you know exactly how much extra income you need.

    • Check your CPF balances. Log into your CPF account and see how much you currently have. This affects how much of the buyback proceeds become cash versus CPF top-ups.

    • Discuss with your family. This decision affects inheritance and your children’s future financial plans. Have honest conversations.

    • Attend HDB’s counselling session. This is mandatory anyway, but treat it seriously. Ask all your questions. Bring your adult children if possible.

    • Get the calculations in writing. HDB will provide projections showing exactly how much you’ll receive and how your monthly payouts will increase.

    Making the most of your lease buyback proceeds

    Once you receive your payout, use it wisely.

    If you get cash beyond the CPF top-up, resist the temptation to spend it all immediately.

    Consider setting aside a portion for:

    • Medical emergencies. Even with MediSave and CHAS subsidies, unexpected health costs can arise.

    • Home maintenance. Your flat still needs upkeep. Aircon servicing, minor repairs, and eventual replacement of appliances add up.

    • Treats and experiences. You’ve worked hard. Budget some money for holidays, meals with family, or hobbies you enjoy.

    The monthly CPF LIFE payouts should cover your regular expenses. The lump sum cash is for everything else.

    Mistakes to avoid with the lease buyback scheme

    Applying without understanding the numbers

    Many seniors sign up based on rough estimates. Get exact figures. Know precisely how much you’ll receive and how it breaks down between CPF and cash.

    Forgetting about estate planning

    A shorter lease affects what you leave behind. Update your will and CPF nominations. Talk to your family about expectations. What happens to your CPF savings when you pass away becomes more complex with lease buyback proceeds.

    Not comparing with downsizing properly

    Run the numbers on both options. Sometimes selling your flat and buying a smaller one generates more total cash, even after moving costs and stamp duty.

    Choosing the shortest possible lease without thinking ahead

    Retaining only 30 years instead of 35 years gives you more money now, but it dramatically reduces your flat’s value sooner. If circumstances change and you need to sell, a flat with 15 years left is much harder to sell than one with 20 years.

    Your next steps

    If the HDB lease buyback scheme sounds right for your situation, here’s what to do:

    Start by using HDB’s online calculator to get a rough estimate of your potential proceeds. You’ll find it on the HDB website under “Lease Buyback Scheme.”

    Gather your documents: NRIC, latest income tax statements, CPF statements, and HDB flat documents.

    Book an appointment at your nearest HDB branch. The officers there can answer specific questions about your situation.

    Bring a family member or trusted friend to the appointment. Two sets of ears catch more details than one.

    Don’t feel pressured to decide on the spot. Take the information home. Sleep on it. Discuss with family. This is a permanent decision that deserves careful thought.

    Making your flat work for your retirement

    The HDB lease buyback scheme isn’t perfect for everyone. But for seniors who need more monthly income and want to stay in their homes, it offers a practical middle ground. You’re not gambling on investments or making drastic life changes. You’re simply converting part of your property’s value into reliable monthly cash flow.

    The key is going in with eyes open. Understand exactly what you’re giving up and what you’re getting. Run the numbers. Talk to your family. Compare alternatives. Then make the choice that fits your specific retirement needs and priorities. Your home has sheltered you for decades. Now it can support you financially too, if you decide that’s the right path forward.

  • How to Apply for a Studio Apartment Under the Silver Housing Bonus Scheme

    How to Apply for a Studio Apartment Under the Silver Housing Bonus Scheme

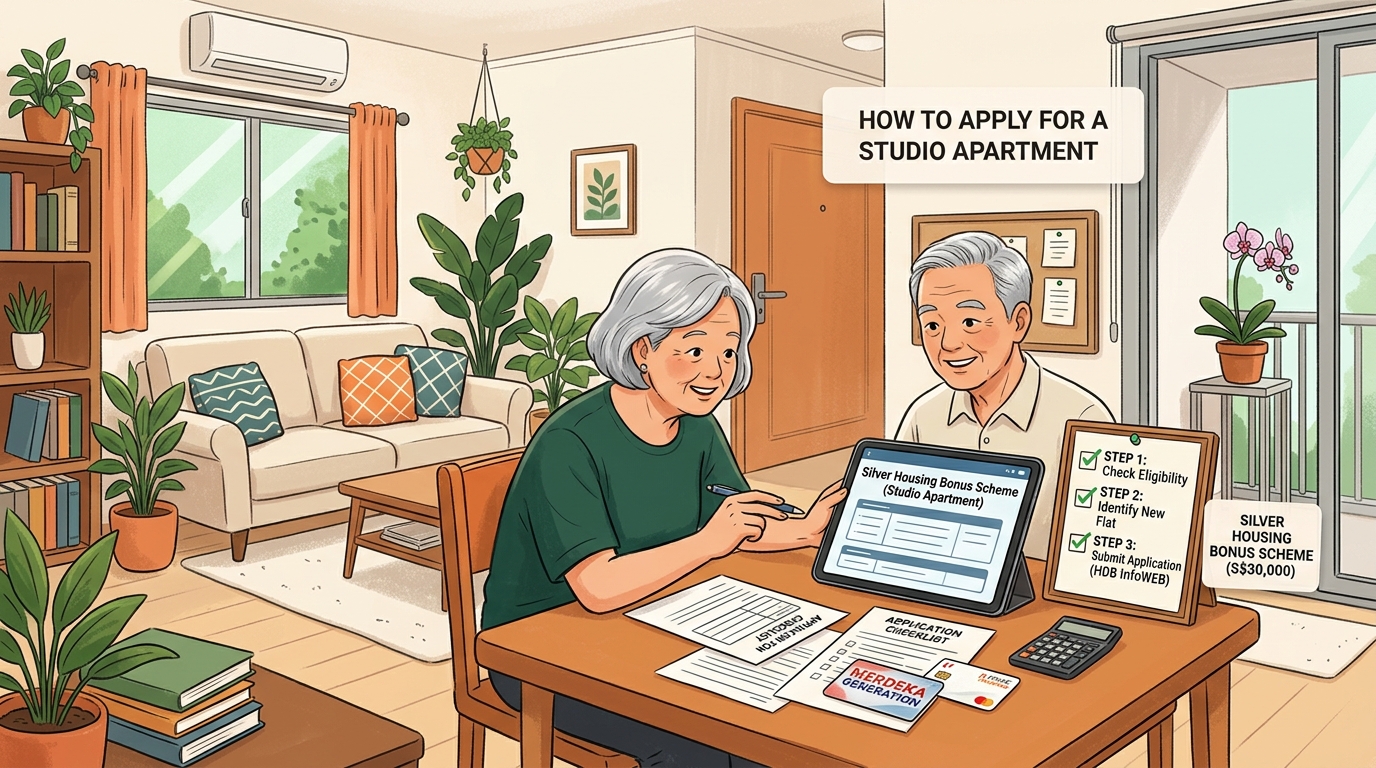
    Thinking about downsizing your HDB flat to boost your retirement funds? The Silver Housing Bonus (SHB) scheme can put up to $30,000 into your CPF Retirement Account when you move to a smaller home. But many seniors miss out simply because they don’t know the application steps or assume the process is too complicated.

    Key Takeaway

    The Silver Housing Bonus gives eligible seniors aged 65 and above up to $30,000 when they downsize to a smaller HDB flat. You apply through HDB when purchasing your replacement flat, and the bonus goes directly into your CPF Retirement Account. Your household income and property ownership affect your eligibility, and you must meet specific conditions including maintaining a minimum CPF balance after the move.

    Who can receive the Silver Housing Bonus

    Before you start the application, make sure you meet the basic requirements.

    You must be at least 65 years old when you apply. Your spouse, if you’re applying as a couple, must also be 65 or above.

    Your current flat must be a 3-room or larger HDB unit. You’ll be moving to a smaller flat, either a 2-room Flexi or 3-room flat.

    Average gross household income matters. If you’re single, your monthly income must not exceed $6,000. For couples or families, the combined household income cap is $12,000 per month.

    Property ownership affects your eligibility too. You can own only one property at the time of application, which is the flat you’re selling. If you or anyone in your household owns other properties, including private property, you won’t qualify unless the total annual value of all properties stays below $21,000.

    You must not have received the Silver Housing Bonus before. This is a one-time benefit.

    “Many seniors think they don’t qualify because they have some savings or own their flat outright. The scheme actually looks at your monthly income and property ownership, not your total wealth. Don’t rule yourself out before checking the full criteria.” (HDB eligibility guidelines)

    Understanding your bonus amount

    How to Apply for a Studio Apartment Under the Silver Housing Bonus Scheme — image 1

    The Silver Housing Bonus isn’t a fixed sum. Your bonus amount depends on your replacement flat type and your property ownership situation.

    If you’re moving to a 2-room Flexi flat, you can receive up to $30,000. Moving to a 3-room flat gets you up to $15,000.

    But there’s a catch. If you or anyone in your household owns any other property, including private property with annual value, your bonus gets reduced by $1 for every $1 of annual value above $0, up to $21,000.

    Here’s how it works in practice:

    Your situation Replacement flat Maximum bonus
    No other property 2-room Flexi $30,000
    No other property 3-room flat $15,000
    Own property with $10,000 annual value 2-room Flexi $20,000
    Own property with $15,000 annual value 3-room flat $0

    The bonus goes straight into your CPF Retirement Account. You cannot receive it as cash. This ensures the money supports your retirement income through CPF LIFE payouts.

    Checking your CPF balance requirements

    The Silver Housing Bonus comes with a mandatory CPF top-up requirement. This ensures you maintain adequate retirement savings after downsizing.

    After you sell your current flat and buy the smaller one, you must have at least $60,000 in your CPF Retirement Account. This includes the Silver Housing Bonus amount.

    If you’re applying as a couple, each person must meet this $60,000 threshold individually. Your spouse’s CPF balance doesn’t count towards your requirement.

    Let’s say you currently have $40,000 in your CPF Retirement Account. You’re moving to a 2-room Flexi flat and qualify for the full $30,000 bonus. After the sale proceeds are used for the new flat purchase and the bonus is credited, you’d have $70,000. That meets the requirement.

    But if you only have $20,000 in your CPF Retirement Account, even with the $30,000 bonus you’d only reach $50,000. You’d need to top up an additional $10,000 from your sale proceeds to meet the $60,000 minimum.

    Planning ahead helps. Before you commit to selling, calculate your expected CPF balance after the transaction. Factor in your current balance, the bonus amount, and how much of your sale proceeds you’ll need for the new flat purchase.

    Step by step application process

    How to Apply for a Studio Apartment Under the Silver Housing Bonus Scheme — image 2

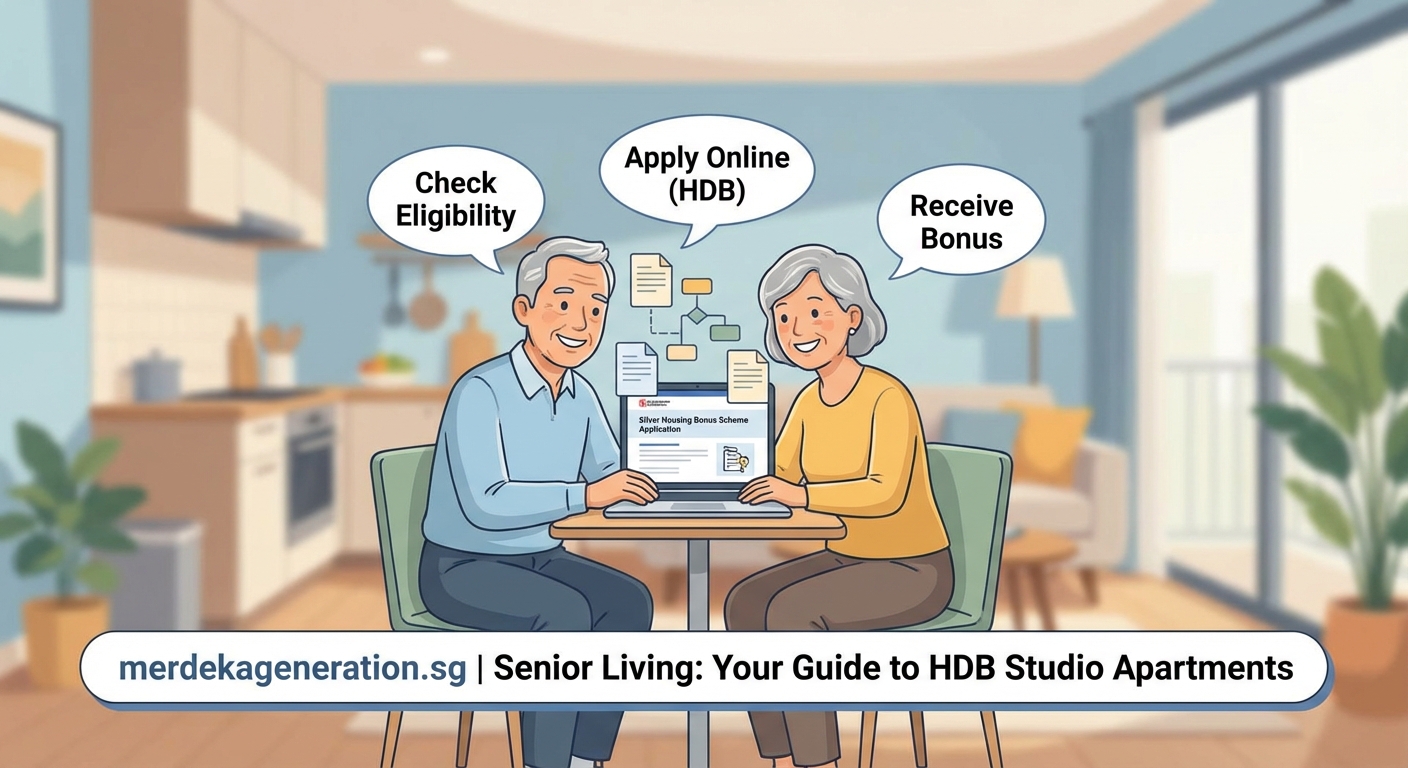
    The application happens during your flat purchase, not as a separate process. Here’s exactly what to do.

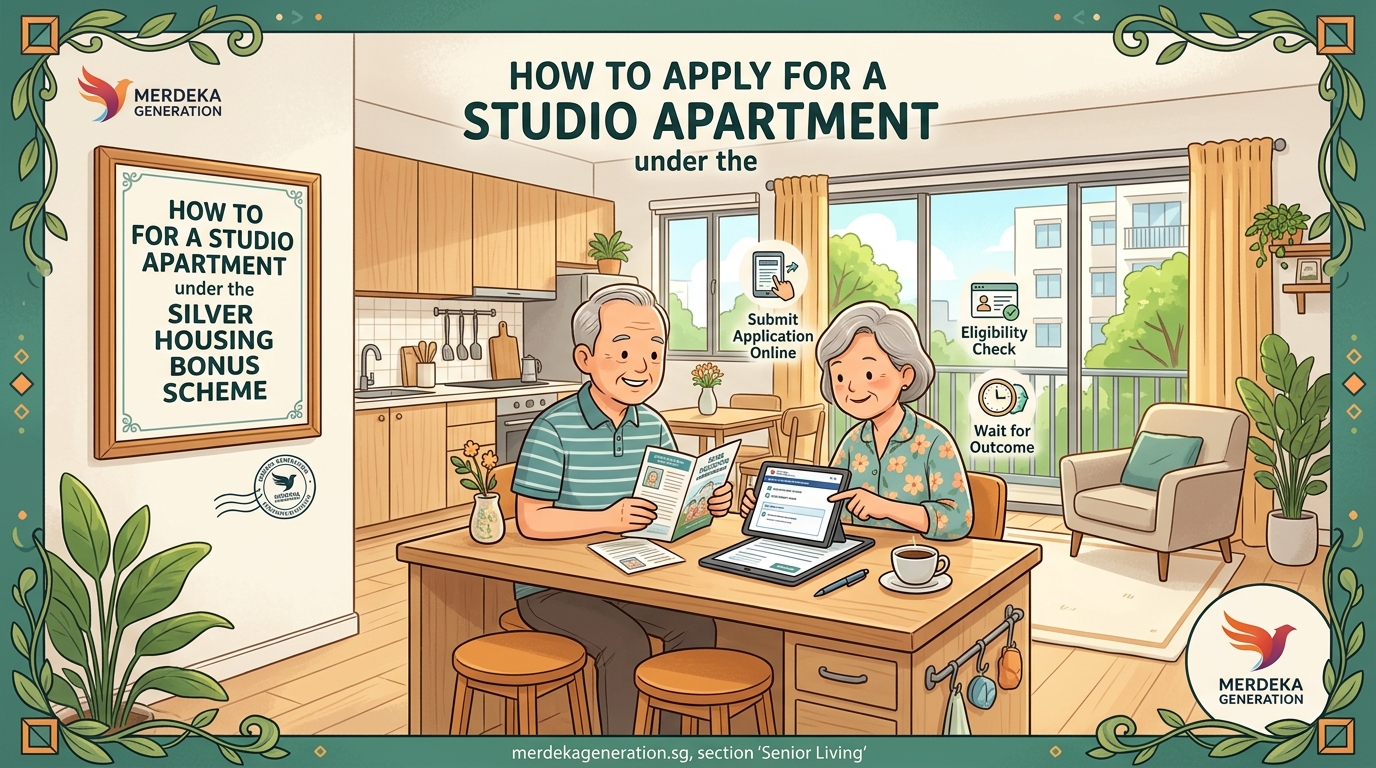
    1. Get your HDB Flat Eligibility letter

    Start by applying for an HDB Flat Eligibility (HFE) letter. You can do this online through the HDB website or at any HDB branch.

    You’ll need your Singpass to log in. The system will ask about your household members, income, and current property ownership.

    Indicate that you want to apply for the Silver Housing Bonus during this HFE application. The system will check your eligibility automatically.

    Processing takes about 3 weeks. You’ll receive a letter stating whether you’re eligible for the scheme and your estimated bonus amount.

    2. Book your replacement flat

    Once you have your HFE letter, you can book a flat. This applies whether you’re buying from HDB directly or from the resale market.

    For new flats, participate in the HDB sales exercise. Your HFE letter confirms your eligibility for priority schemes if applicable.

    For resale flats, find a suitable unit and negotiate with the seller. Your HFE letter remains valid for 6 months, giving you time to search.

    Make sure the flat you’re buying is smaller than your current one. A 2-room Flexi or 3-room flat qualifies.

    3. Submit your resale application

    If you’re buying a resale flat, both buyer and seller submit the resale application through the HDB resale portal.

    During this application, you’ll confirm that you’re applying for the Silver Housing Bonus. The system will calculate your exact bonus amount based on your circumstances.

    You’ll also see the CPF balance requirement clearly stated. The system shows how much you need to set aside in your CPF Retirement Account.

    4. Complete the flat purchase

    Attend the HDB appointment to complete the purchase. Bring all required documents including identification, income proof, and your HFE letter.

    HDB will verify your eligibility again at this stage. They’ll check that your circumstances haven’t changed since your HFE approval.

    Sign all necessary documents. The flat purchase completes, and ownership transfers to you.

    5. Receive your bonus

    After completion, HDB credits the Silver Housing Bonus directly to your CPF Retirement Account. This happens automatically within a few weeks.

    You’ll receive a notification from CPF showing the credit. Check your CPF statement online to confirm the amount.

    The bonus becomes part of your CPF LIFE plan, generating monthly payouts during retirement. You cannot withdraw it as a lump sum.

    Common mistakes that delay applications

    Many seniors run into problems that could have been avoided with better preparation.

    Not checking income limits carefully

    Some applicants forget to include all household income sources. Rental income, part-time work, and regular financial support from children all count. If your total exceeds the cap, you won’t qualify. Calculate accurately before applying.

    Overlooking property ownership rules

    Owning a small investment property or having your name on a family member’s property title can disqualify you. Even if you don’t live there or don’t benefit financially, HDB considers it property ownership. Check all property records before starting your application.

    Selling current flat before securing replacement

    You need to own your current flat when you apply. Some seniors sell first, thinking they can apply later. That doesn’t work. Apply while you still own the flat you’re downsizing from.

    Insufficient CPF balance planning

    Not having enough in your CPF Retirement Account to meet the $60,000 requirement stops many applications. Calculate this before you commit to selling. You might need to set aside more sale proceeds than expected.

    Missing the HFE validity period

    Your HFE letter expires after 6 months. If you don’t find a replacement flat within that time, you need to reapply. Start your flat search early to avoid rushing or missing the deadline.

    Assuming automatic approval

    Meeting the basic criteria doesn’t guarantee approval. HDB reviews each application individually. Provide complete, accurate information and respond to any queries promptly.

    What happens after you receive the bonus

    How to Apply for a Studio Apartment Under the Silver Housing Bonus Scheme — image 3

    Getting the Silver Housing Bonus is just the beginning. Understanding how it affects your retirement planning matters.

    The bonus sits in your CPF Retirement Account and becomes part of your CPF LIFE plan. This means it generates monthly payouts from age 65 onwards.

    For example, if you receive the full $30,000 bonus, this increases your monthly CPF LIFE payout. The exact increase depends on your CPF LIFE plan type and your age when the bonus is credited.

    You cannot withdraw the bonus as cash, even after age 65. It stays locked in CPF LIFE to provide retirement income. This protects you from spending the money too fast.

    If you’re thinking about how this fits with other retirement planning strategies, should you downsize your HDB flat for extra retirement cash covers the broader financial considerations.

    The bonus also counts when calculating your CPF balances for other purposes. If you’re planning to top up your CPF further, should you top up your CPF LIFE after 65 explains how additional contributions work with existing balances.

    Coordinating with other retirement benefits

    The Silver Housing Bonus works alongside other government schemes available to seniors.

    If you’re part of the Merdeka Generation, you already receive healthcare subsidies and other benefits. The Silver Housing Bonus doesn’t affect these. You keep all your existing benefits.

    However, if you’re unsure about your Merdeka Generation eligibility status, how to check if you qualify for the Merdeka Generation Package in 2024 walks through the verification process.

    Some seniors worry about losing benefits when they move. Your CHAS card benefits continue at your new address. The healthcare subsidies don’t change based on your flat size. Learn more about CHAS card benefits explained to understand what remains available.

    Your MediShield Life coverage also stays active. Moving to a smaller flat doesn’t affect your healthcare protection. For details on maximizing this coverage, how to maximise your MediShield Life coverage as a Merdeka Generation senior provides practical strategies.

    Planning your finances after downsizing

    How to Apply for a Studio Apartment Under the Silver Housing Bonus Scheme — image 4

    Downsizing creates a significant financial shift. The Silver Housing Bonus is one part, but you’ll also have cash proceeds from selling your larger flat.

    Most seniors use sale proceeds to pay for the smaller replacement flat. The leftover amount can supplement retirement income or serve as emergency savings.

    Consider how much you need for monthly expenses. Your CPF LIFE payouts, including the boost from the Silver Housing Bonus, provide baseline income. Cash savings cover unexpected costs.

    Healthcare expenses often increase with age. While MediShield Life and CHAS subsidies help, some costs still come out of pocket. Managing healthcare costs in retirement offers strategies for handling medical expenses beyond subsidies.

    Creating a realistic budget helps you live comfortably on fixed income. Creating a monthly budget that works on fixed CPF LIFE and pension income shows how to structure spending when your income doesn’t fluctuate.

    Documents you’ll need throughout the process

    Gather these documents before starting your application to avoid delays.

    • NRIC for all household members applying
    • Recent payslips or income statements covering the last 12 months
    • CPF contribution history printout from the CPF website
    • Current flat ownership documents showing you as the registered owner
    • Property tax statements if you own any other property
    • HDB Flat Eligibility letter once approved
    • Resale flat listing or booking documents for your replacement flat

    Keep both physical and digital copies. Some appointments require original documents, while online applications need scanned versions.

    If you’re missing any documents, request them early. CPF statements take a few days to generate. Property ownership searches through IRAS can take up to a week.

    Getting help with your application

    You don’t have to figure this out alone. Several resources can guide you through the process.

    HDB branches offer face-to-face assistance. Staff can review your eligibility, explain requirements, and help with online submissions. Book an appointment to avoid long waits.

    The HDB hotline answers questions about the scheme. Call 1800-225-5432 during office hours. Have your NRIC ready for identity verification.

    Community centres and senior activity centres sometimes run workshops on housing schemes for elderly residents. These sessions explain the process in simple terms and answer common questions.

    If you prefer written guidance, the HDB website has detailed information pages. Search for “Silver Housing Bonus” to find official guidelines, eligibility criteria, and application instructions.

    For seniors who need help avoiding common pitfalls with government benefits, 5 common mistakes Merdeka Generation seniors make when claiming benefits highlights issues to watch for.

    Making the most of your downsizing decision

    Applying for the Silver Housing Bonus is straightforward when you know the steps. Start by checking your eligibility carefully, especially income limits and property ownership. Get your HFE letter early to allow time for flat hunting. Calculate your CPF balance requirements before committing to sell. Follow the application process during your flat purchase, not as a separate task.

    The bonus boosts your retirement income through higher CPF LIFE payouts. Combined with proceeds from selling your larger flat, downsizing can significantly improve your financial security in retirement. Take time to plan how you’ll use both the bonus and any cash proceeds wisely.

    Don’t let uncertainty stop you from exploring this option. Thousands of seniors have successfully applied for the Silver Housing Bonus and moved to comfortable, more manageable homes. With proper preparation and understanding of the process, you can too.